

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Thiochemicals Market Reaches USD 3,260.5 Million in 2025; Forecast 2026–2032 to Grow at 4.51% CAGR
By pmarketresearch, 2026-07-15
Worldwide Thiochemicals Market — Strategic Insights for 2026 Corporate Decision-Making
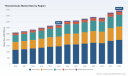
As global commodity and specialty chemical value chains recalibrate for a post-pandemic, energy-transition era, thiochemicals occupy a uniquely strategic niche. PW Consulting’s latest market study shows the global thiochemicals market reached approximately USD 3,260.5 million in 2025 and is expected to strengthen in the near term — reaching roughly USD 3,577.3 million in 2026 — before progressing at a compound annual growth rate (CAGR) of 4.51% over the 2026–2032 forecast window to about USD 4,440.1 million by 2032. For executives planning capex, procurement, or commercial redeployment in 2026, the report delivers the combination of macro clarity and practicable options required to translate market movement into defensible, value-accretive decisions.
Worldwide Thiochemicals Market
What the report delivers — practical, decision-focused outputs
-
Quantified market baseline and directional scenarios: firm 2025 base-year sizing, 2026 short-term outlook, and detailed 2026–2032 trajectories across demand and supply sides.
Worldwide Thiochemicals Market -
Demand-driver intelligence: sectoral demand drivers and stress scenarios that affect product mix priorities without exposing client-level proprietary splits.
Worldwide Thiochemicals Market -
Cost and margin stress-testing: feedstock-price sensitivity matrices (notably sulfur-linked inputs), break-even curves, and margin-protection playbooks for different product classes.
-
Supply-chain and capacity mapping: verification of global manufacturing footprints, debottlenecking opportunities, and logistics risk heatmaps.
-
Competitive benchmarking and capability mapping of leading producers, including technical strengths, footprint advantages, and likely strategic moves.
-
M&A and partnership playbooks: prioritized target archetypes, valuation lenses, and integration risk checklists tuned to 2026 market conditions.
-
Regulatory & sustainability roadmap: compliance cost estimates, low-emission process options, and transition pathways aligned with evolving ESG thresholds.
Why 2026 is a pivotal planning year
Two sets of dynamics converge in 2026 to make near-term strategic action material to medium-term value creation. First, upstream feedstock volatility has returned as a critical margin lever. Elemental sulfur — the primary upstream feedstock that is converted into H2S and methyl mercaptan for downstream thiochemical synthesis — has experienced pronounced price swings. Industry monitoring indicates contract and spot benchmarks moved sharply in late 2025 and into 2026, creating a short-term squeeze that transmits quickly into operating margins for producers. For certain mercaptan producers, sulfur procurement can represent as much as one quarter of cash cost, underscoring the importance of robust procurement and hedging strategies.
Second, demand-side composition is shifting. Traditional applications such as oil & gas and fertilizer-related demand remain material, while specialty uses in animal nutrition, polymer processing, and pharmaceutical intermediates are evolving in quality and regulatory expectations. These dynamics mean that product portfolio choices — commodity versus specialty, volume versus margin — will determine winners and losers as buyers re-price risk and suppliers optimize capacity.
Competitive landscape: capabilities to watch (select overview)
-
Arkema (France) — a global integrator with a broad organosulfur portfolio and multi-continent manufacturing. Recent disclosures and operational moves (including a 2023 debottlenecking program in North America and the company’s 2024 sustainability reporting) signal a strategy combining capacity optimization and ESG positioning.
-
Chevron Phillips Chemical (United States) — leverages refinery and petrochemical integration to supply mercaptans and thiochemical intermediates for industrial and refinery applications; strong technical and feedstock access positions underpin its market relevance.
-
Specialty and regional producers — a cohort of European, Japanese and Chinese firms (including Merck KGaA, Daicel, Toray Fine Chemicals and multiple Chinese manufacturers) competes on high-purity grades, application-specific formulations, and local cost positions. Many of these players target differentiated niches such as pharmaceutical-grade reagents, cosmetic intermediates, and agrochemical inputs.
-
Market structure — the sector shows a moderate level of concentration: a mix of global leaders with broad portfolios and numerous regional specialists. The implication is dual-track competition — scale plays for commodity lines, and technical specialization for higher-margin segments.
Strategic implications for executives in 2026
Our analysis crystallizes seven cross-functional imperatives that should inform board-room deliberations, capital planning and commercial strategy in 2026.
-
Hedge and secure feedstocks proactively. Given sulfur-price volatility and its outsized effect on methyl-mercaptan cash costs, companies should deploy multi-layered procurement approaches: long-term contracts with indexed clauses, strategic spot exposure limits, and evaluation of upstream integration (H2S capture or sulfur recycling) where capex economics permit.
-
Prioritize portfolio clarity: balance volume with margin. Use product-level margin simulation to reallocate R&D and commercialization spend toward higher-margin specialty thiochemicals where technical barriers limit new entrants, while rationalizing low-margin commodity lines through consolidation or tolling agreements.
-
Strengthen manufacturing resilience. Multi-site manufacturing footprints reduce single-point failures; debottlenecking and short-cycle capacity flex (e.g., tolling partnerships or modular units) enable faster response to demand spikes without large fixed investments.
-
Adopt targeted sustainability investments. Low-emission process upgrades and feedstock-efficiency gains can be both differentiation and compliance drivers. Prepare to translate sustainability investments into customer-facing claims that buyers in regulated industries will value.
-
Reassess pricing architectures. Move beyond transactional spot pricing to value-based pricing in specialty channels, and implement clause-driven contracts that share feedstock cost volatility with buyers where trust and market position allow.
-
Scan for M&A and partnership vectors. In a market with clear adjacent capabilities and regional strengths, bolt-on acquisitions, JV manufacturing for local markets, and IP/technology licensing are high-leverage options to accelerate market access without greenfield timelines.
-
Embed advanced analytics into the commercial engine. Demand-sensing using end-market telemetry (e.g., fertilizer and animal feed indicators), combined with cost-to-serve models, enables dynamic allocation of limited production to most valuable channels in short-cycle environments.
Competitive moves to watch in 2026
Several near-term moves will determine market share trajectories through the late 2020s. Watch for:
-
Capacity optimization and debottlenecking by global leaders pursuing incremental tonnage in high-value lines — actions which can temporarily compress spreads but drive longer-term volume leadership.
-
Regional capacity additions in cost-advantaged geographies, particularly from mid-sized Chinese producers that continue to scale production of intermediates and fine sulfur chemicals.
-
Strategic alliances between feedstock holders and specialty producers to lock supply chains and create preferred-supplier ecosystems for sensitive applications (e.g., pharma and high-purity reagents).
-
Regulatory and sustainability-driven product differentiation: expect new grades and processes to be promoted to buyers focused on life-cycle impacts.
How PW Consulting supports 2026 decision cycles
PW Consulting brings a practitioner-first suite of services tailored to the thiochemicals agenda:
-
Scenario-based valuation and capex prioritization — including sulfur-price stress tests and break-even mapping by product family.
-
Commercial playbooks for portfolio shift — from go-to-market segmentation to value-based pricing and distributor redesign.
-
M&A diligence and integration playbooks — target screening by capability archetype, synergies quantification, and post-merger integration sequencing.
-
Procurement optimization — contract design, hedging strategies, and supplier consolidation plans focused on feedstock volatility mitigation.
-
Operational improvement — debottlenecking blueprints, modular capacity options, and OPEX-driven margin recovery programs.
Final note: where to find the data you need
This briefing is a concise distillation of the report’s strategic findings. PW Consulting’s full Worldwide Thiochemicals Market report contains the complete datasets, regional and product-level forecasts, and the granular scenario models that underpin the recommendations summarized here. The report’s methodological frame is anchored on a 2025 base year, historical analysis for 2020–2025, and a forecast period covering 2026–2032 (currency: USD, revenue units in millions). For procurement teams, commercial leaders and corporate strategists preparing 2026 plans, the full report provides the calibrated segment-level intelligence and downloadable models necessary to operationalize the strategic directions outlined above.
To engage PW Consulting for a customized workshop, model adaptation, or acquisition due diligence support tied to the thiochemicals value chain, contact our industry team for a confidential consultation and access to the full dataset.
For detailed analysis of this topic, please visit the official page: Worldwide Thiochemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Aliphatic Polysulfide Market to Expand at a 4.89% CAGR During 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Aliphatic Polysulfide Market — Strategic Preview for 2026 Decision-Makers
Executive summary
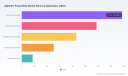
PW Consulting's latest Worldwide Aliphatic Polysulfide Market report (base year 2025, forecast 2026–2032) distills the market forces that will shape capital allocation, product development and go-to-market decisions for the coming cycle. The aliphatic polysulfide market has demonstrated steady recovery and resilience through 2020–2025, with total market revenue rising from the low‑hundreds of millions to USD 428.8 Million in 2025. Our forward view estimates a compound annual growth rate (CAGR) of 4.89% for 2026–2032, projecting a global market approaching USD 599 Million by 2032. For executives planning 2026 investments, this report is designed as a tactical playbook: it identifies value pools, supply‑chain inflection points, regulatory crosswinds, and competitor moves — and translates them into near‑term actions that preserve optionality while accelerating return on invested capital.
Worldwide Aliphatic Polysulfide Market
Why this market matters in 2026
Aliphatic polysulfides occupy a niche but strategically important role where chemical resistance, low permeability and long-term flexibility are critical — from aerospace fuel tank sealants to specialty construction applications and insulating glass. The credibly predictable mid‑single digit CAGR masks meaningful pockets of re‑rating driven by regulatory substitution, formulation innovation and supply‑side consolidation. The market concentration is material: the top three and top five global players command a dominant share of supply, underscoring the strategic importance of partnership, capacity planning and differentiated product strategies for new entrants and incumbents alike.
Worldwide Aliphatic Polysulfide Market
Market trajectory and what it means for 2026 planning
-
Historical momentum and near‑term outlook: After a volatile 2020–2022 period, the market stabilized and expanded to USD 428.8 Million in 2025. Our base‑case scenario projects growth at roughly 4.9% annually across the 2026–2032 horizon, reaching nearly USD 599 Million by 2032.
Worldwide Aliphatic Polysulfide Market -
Investment horizons: For corporate strategists, the implication is clear — the market is large enough to justify targeted R&D and process investments, yet concentrated enough that scale and channel relationships will determine commercial success.
-
Timing and optionality: 2026 represents a window to lock in feedstock contracts, advance regulatory‑compliant formulations and pilot higher‑performance aliphatic grades that address specific end‑use pain points (e.g., improved chemical resistance at low temperatures, or epoxy‑terminated offerings for coatings and adhesives).
Dynamics reshaping the competitive landscape
Three dynamics deserve elevated attention in 2026 corporate planning: raw material volatility and regional feedstock asymmetries; regulatory substitution and environmental compliance; and differentiated product launches from leading suppliers.
-
Raw material dynamics: Ethylene dichloride (EDC), a key precursor in aliphatic polysulfide manufacture, shows meaningful regional price dispersion that alters feedstock economics and localized competitiveness. As of Q4 2025 market checks, EDC prices were materially lower in North America relative to key Asian and European markets. These disparities influence sourcing strategies, incremental margin by plant location and the arithmetic of new capacity investments.
-
Regulatory substitution: Ongoing restrictions on legacy lead‑based curing agents across RoHS and REACH jurisdictions — and the practical dominance of manganese dioxide‑cured systems in many advanced markets — are shifting formulation roadmaps. Companies that can accelerate lead‑free curing chemistries and demonstrate compliance under evolving effluent and waste standards will secure privileged access to aerospace, construction and glass OEM supply chains.
-
Environmental and discharge standards: U.S. EPA guidance under 40 CFR Part 414 continues to frame capital outlays for treatment and pretreatment in facilities handling organic chemicals and related processes. Anticipating these compliance costs is a non‑trivial component of new project economics and M&A diligence in 2026.
Competitive picture — capabilities, moves and implications
The market is characterized by a small set of technically sophisticated producers and several regional players that serve localized demand patterns. Key profiles and strategic implications include:
-
Nouryon: As the most prominent global producer of liquid polysulfide polymers under the Thioplast® umbrella, Nouryon's recent introduction of an epoxy‑terminated aliphatic grade designed specifically for harsh environments signals a deliberate pivot up the value chain. For competitors and customers alike, this accentuates the importance of formulation partnerships and co‑development agreements that can leverage the enhanced chemical resistance and low‑temperature flexibility of next‑generation aliphatic grades.
-
Toray Fine Chemicals: The sole Japanese manufacturer of polysulfide polymers offers mercaptan‑terminated base polymers that remain integral to high‑performance sealants in construction and civil engineering. Toray's positioning underscores the relevance of reliable domestic supply for geographies with elevated import risk and the premium buyers are willing to pay for regional sourcing, traceability and tailored technical support.
-
Kazan Synthetic Rubber Plant (KSRP): A major producer with a diversified customer base, KSRP emphasizes chemical‑resistant elastomers and demonstrates how regional players defend niches by optimizing cost‑to‑performance tradeoffs. For multinationals evaluating entry or expansion, regional incumbents offer lessons in pricing, distribution and technical service models that win in cost‑sensitive segments.
-
PPG Industries (PRC‑DeSoto): PPG’s application‑focused polysulfide formulations for aerospace highlight a recurring strategic theme: high‑margin, specification‑driven applications (aerospace sealants, fuel‑system components) remain the most defensible revenue streams. Partnerships with OEMs, rigorous qualification cycles and proven supply reliability are barriers to entry that favor incumbent suppliers.
What the report contains — practical, transaction‑ready intelligence
PW Consulting’s report is structured to inform decisions across commercial, technical and corporate functions without requiring readers to wade through raw data dumps. Highlights include:
-
Market sizing and scenario forecasts (2026–2032) with sensitivity analyses that isolate the impact of feedstock shocks, regulatory tightening and demand shifts in key end uses.
-
Supply‑chain risk maps and sourcing playbooks that quantify the tradeoffs of regional production footprints under realistic feedstock pricing and permit regimes.
-
Competitor profiles and capability matrices that go beyond product catalogs to assess technical service, qualification lead times, and aftermarket support — the intangible assets that translate to higher win rates in specification‑driven markets.
-
Regulatory and environmental compliance checklists tailored for plant operations, R&D laboratories and commercial teams to streamline permit planning and minimize time‑to‑qualification for lead‑free curing systems.
-
M&A and JV decision frameworks including valuation sensitivities tied to concentration metrics and barriers to entry — essential for boards and corporate development teams considering bolt‑on acquisitions in 2026.
Actionable recommendations for 2026
Based on our analysis, PW Consulting recommends a prioritized set of actions for companies with exposure to aliphatic polysulfides:
-
De‑risk feedstock exposure: Negotiate multi‑year EDC contracts with price collars or pursue integrated procurement arrangements where feasible. For firms evaluating greenfield capacity, model scenarios using region‑specific EDC economics and include EPA compliance capex in early stage NPV runs.
-
Accelerate lead‑free formulation roadmaps: Convert R&D roadmaps into qualification pipelines with target OEMs. Early demonstration of manganese dioxide‑cured systems or alternative curing agents will be a decisive commercial advantage, particularly in RoHS/REACH jurisdictions.
-
Prioritize specifications over commodities: Move up the value chain by developing formulation IP for demanding end uses (aerospace, insulating glass) and align commercial incentives with aftermarket service and qualification support.
-
Use concentration dynamics strategically: For smaller suppliers, consider capacity consolidation or selective partnerships with incumbent global manufacturers to broaden market access. For larger firms, evaluate bolt‑on acquisitions to secure feedstock access and shorten qualification cycles.
-
Embed regulatory cost into pricing models: Ensure that sales and commercial teams understand the capital and operating costs of effluent control and chemical‑handling compliance — these are no longer peripheral but core to margin management.
How to use this intelligence in boardroom deliberations
An effective 2026 board deck should separate three decision layers: (1) short‑term supply and contract actions to stabilize margins over the next 12 months; (2) medium‑term product and qualification investments to capture high‑value segments; and (3) long‑term portfolio moves including M&A and vertical integration. PW Consulting’s report supplies the data templates, risk matrices and scenario outputs that map directly to these decision gates, enabling CFOs and strategy leaders to translate market outlooks into executable commitments.
Conclusion — the strategic dividend of focused insight
The aliphatic polysulfide market is neither explosive nor stagnant; it is a measured growth market with concentrated supply and substantial regulatory and feedstock‑driven inflection points. For 2026, the most valuable corporate responses will be those that convert regulatory pressure and feedstock dispersion into competitive advantage — through lead‑free formulations, disciplined sourcing strategies and specification‑led commercialization. PW Consulting’s Worldwide Aliphatic Polysulfide Market report provides the practical, transaction‑ready intelligence to make those calls with confidence.
Call to action
This release is intended as a strategic preview. For full segment‑level analysis, granular regional forecasts, supplier benchmarking, and the complete set of operational playbooks and financial models referenced above, please consult the full PW Consulting Worldwide Aliphatic Polysulfide Market report. Access to the complete dataset and model templates will enable teams to run bespoke scenarios tailored to their cost base, product mix and investment horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Aliphatic Polysulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rare Disease CRO Service Market to Reach USD 12,829 Million by 2032 on 10.2% CAGR
By pmarketresearch, 2026-07-15
Rare Disease CRO Service Market: Strategic Imperatives for 2026
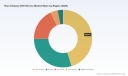
PW Consulting’s new market research brief on the Rare Disease Contract Research Organization (CRO) Service Market synthesizes commercial, regulatory and operational intelligence that will shape outsourcing decisions through 2026 and beyond. Built on a detailed base year of 2025 and a 2026–2032 forecast horizon, the study combines rigorous market-sizing with actionable playbooks for sponsors, CROs, investors and policy teams. Key macro signals — including a projected compound annual growth rate (CAGR) of 10.2% and an escalating total market that more than doubles over the forecast period — make 2026 a pivotal planning year for firms that must balance capacity, capability and compliance in complex, low-volume development programs.
Rare Disease CRO Service Market
Market Trajectory in Context
Between 2020 and 2025 the rare disease CRO market experienced a sustained expansion, reflecting accelerating investment in orphan-drug pipelines, advanced therapies and trial models tailored to dispersed patient populations. Our base-year analysis (2025) anchors the study and the 2026–2032 forecast quantifies the continuation of that momentum: at a 10.2% CAGR the market is expected to more than double from its early‑decade scale by the end of the forecast window. This growth reflects both a rising number of programs in gene, cell and RNA modalities and the premium per‑patient economics that rare disease trials entail.
Rare Disease CRO Service Market
Why 2026 Is an Inflection Year
-
Regulatory harmonization and flexibility: Initiatives such as the FDA’s Rare Disease Innovation Hub and the Rare Disease Evidence Principles (announced in 2025) are lowering traditional evidentiary barriers for ultra‑rare conditions, but they also place a premium on adaptive statistical planning and specialized regulatory strategy.
Rare Disease CRO Service Market -
Guidelines and operational adaptation: ICH E6(R3) finalized in 2025 emphasizes risk‑based monitoring and flexible trial designs, accelerating adoption of decentralized assessments, remote endpoints and hybrid models — all of which require CROs to retool platforms and talent pools in 2026.
-
Data privacy and cross‑border complexity: Cross‑border genomic data flows continue to be constrained by GDPR, HIPAA and related regimes. Sponsors must reconcile global recruitment ambitions with data governance plans that protect patient privacy without compromising analytic utility.
-
M&A and capability consolidation: Recent sector moves and announced transactions show buyers prioritizing endpoint‑data integration, specialized patient recruitment networks and Centers of Expertise. These trends create both scale opportunities and integration risks for acquirers and targets alike.
Competitive Structure and Strategic Players
The market remains moderately concentrated: the top three and top five vendor groups capture meaningful shares of activity and capacity, yet a diverse array of specialized and regional players continues to compete for protocol‑specific mandates. Market concentration metrics embedded in the report highlight a landscape where leading full‑service CROs coexist with niche specialists focused on biomarker analytics, decentralized execution and ultra‑rare recruitment strategies.
Key organizations profiled in the study include established global CROs and specialized firms that represent distinct strategic archetypes:
-
Medpace — an end‑to‑end clinical development partner with deep neuroscience, metabolic and ophthalmology expertise and hundreds of rare disease studies informing standardized playbooks for complex protocols.
-
Precision for Medicine — a biomarker- and lab-integrated specialist that brings “Rarefied Thinking” to cell and gene programs through tight lab-clinic integration across multiple indications.
-
Parexel and ICON — large global CROs offering integrated clinical, regulatory and access consulting able to support gene and nucleic acid therapy trials at scale.
-
PPD (Thermo Fisher) and IQVIA — data- and endpoint-focused players investing in systems to reduce per-patient operational friction and to accelerate go/no‑go decisions.
-
Specialists such as TFS HealthScience, Ergomed, Allucent, Fortrea and Veristat — firms that combine tailored patient-finding, operational agility and therapeutic‑area centers of excellence to serve ultra‑rare and pediatric programs.
-
Worldwide Clinical Trials and other mid‑market firms — consolidators that expand capability sets through acquisitions to penetrate adjacent therapy areas and functional service platforms.
The competitive profiles in the report balance quantitative benchmarking with qualitative decision heuristics — allowing clients to compare capability gaps and partnership fit without divulging commercially sensitive segment-level metrics in this public summary.
Operational and Commercial Dynamics That Will Drive Decisions in 2026
-
Cost per patient remains materially higher in ultra‑rare Phase III programs, driven by specialized navigators, bespoke endpoint collection and geographically dispersed cohorts. Sponsors must decide whether to internalize rare disease competencies or to form longer-term strategic partnerships with CROs that have embedded rare-disease infrastructures.
-
Patient recruitment sophistication is now a competitive moat: firms that combine patient‑registry analytics, advocacy partnerships and decentralized enrollment solutions reduce screen‑fail rates and compress timelines.
-
Endpoint data integration and electronic source systems are no longer optional. Recent announced integrations in the sector reflect buyer demand for data harmonization across lab, imaging and wearable streams.
-
Regulatory strategy and evidence planning must be front‑loaded. Adaptive designs, registry‑based controls and natural history alignment require early engagement with regulators and payers to maximize the value of limited patient data.
What the PW Consulting Report Delivers — Practical, Executable Assets
This study was developed for executives who need to convert market intelligence into program-level decisions in 2026. Deliverables include:
-
Robust market sizing and a transparent methodology tied to a 2020–2025 historical base and a 2026–2032 forecast, enabling scenario analysis under multiple adoption paths and reimbursement outcomes.
-
Vendor capability maps and a decision matrix that rank potential CRO partners against protocol archetypes (e.g., gene therapy, pediatric metabolic, neuromuscular trials) — presented as playbooks rather than raw market slices.
-
Operational playbooks for patient recruitment, decentralized assessments, endpoint device integration and risk‑based monitoring that can be implemented within 90–180 days.
-
M&A and partnership assessment frameworks including integration checklists, value‑capture levers and a regulatory due diligence template focused on data governance and cross‑border compliance.
-
Payer and evidence-generation pathways aligning rare disease approval strategies with post‑launch access planning — essential for aligning clinical design to commercial outcomes.
How Executives Should Use This Intelligence in 2026
-
Prioritize capability investments. Use the report’s capability heatmaps to decide whether to buy, build or co‑develop rare‑disease competencies — including biomarker labs, patient recruitment hubs and decentralized trial platforms.
-
Calibrate partnership horizons. Longer program timelines and high per‑patient costs favor multi‑year strategic alliances over transactional engagements for sponsors running multiple rare indications.
-
Screen targets with a technical lens. The report’s M&A scoring tool helps acquirers evaluate targets based on operational fit, evidence-generation speed and regulatory readiness rather than headline revenue multiples alone.
-
Stress test data governance. 2026 is the year to codify genomic and patient-level data flows into contracts and systems that are resilient to GDPR/HIPAA constraints while preserving analytic value.
-
Integrate regulatory and commercial planning. Use the report’s evidence-principles playbook to align adaptive trial features with likely payer evidence requirements, reducing post‑launch reimbursement risk.
Why This Report Is a Strategic Asset — Not Just a Dataset
We designed the study to be executional. Beyond headline market growth figures and vendor lists, the report translates macro growth into the micro decisions teams face when standing up rare‑disease programs: how to price FSP engagements for ultra‑rare cohorts, how to staff advanced‑therapy trial teams, how to structure global data governance, and how to operationalize adaptive designs in ways that satisfy regulators and payers. The public summary you are reading deliberately omits granular regional and service‑type splits to preserve the proprietary segmentation and scenario outputs that are available in the full deliverable. That “teaser” approach reflects our view: strategic advantage accrues to leaders who pair public signals with privileged, actionable frameworks.
Next Steps for 2026 Decision Makers
If your 2026 agenda includes reprioritizing development portfolios, sizing M&A pipelines, or rethinking outsourcing models for orphan and ultra‑rare programs, PW Consulting’s Rare Disease CRO Service Market report is built to accelerate those decisions. The full report contains the detailed segmentation, vendor scorecards and executable playbooks you will need to operationalize the strategic directions outlined here.
To obtain the full analysis, detailed splits and downloadable tools referenced in this release, access the PW Consulting report page or contact our advisory team for a briefing tailored to your program portfolio.
For detailed analysis of this topic, please visit the official page: Rare Disease CRO Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Digital Olfactory Market Set to Climb from USD 185.5 Million in 2025 to USD 310.5 Million by 2032 at a 7.63% CAGR — E‑Nose Sensors Lead, North America Tops, Top‑5 Hold 48%
By pmarketresearch, 2026-07-15
Digital Olfactory Technology Market: Strategic Imperatives for 2026 — PW Consulting Highlights from Our New Market Report
Executive snapshot
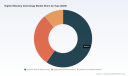
PW Consulting’s latest market study on Digital Olfactory technology provides a forward-looking, operationally oriented assessment designed to influence enterprise strategy in 2026. The report, based on a 2025 base year with historical coverage from 2020–2025 and a detailed forecast out to 2032, synthesizes primary research, vendor interviews, regulatory mapping, and a proprietary market model. At a macro level, the market is on a sustained growth trajectory driven by advances in sensor microfabrication, AI-enabled signal processing, and emergent commercial use cases — reflected in a compound annual growth rate of 7.63% for the forecast period and a projected market expansion from an estimated USD 185.5 Million in 2025 to approximately USD 310.5 Million by 2032.
Digital Olfactory technology Market
Why this matters to corporate decision-makers in 2026
-
Timing and scale: With mid-single-digit to high-single-digit CAGR and a near-term inflection in commercialization activity, executives must decide now whether to invest in internal capability, partner with specialist vendors, or remain a fast follower. The market is large enough to matter for product differentiation, yet still fragmented enough to allow for strategic entry points.
Digital Olfactory technology Market -
Technology stack bets: The interplay between sensor hardware, signal-conditioning electronics, and machine-learning analytics creates multiple levers for value capture. Choices made in 2026 about which layer to own will determine margin profiles and exit options three to five years out.
Digital Olfactory technology Market -
Regulatory and standards design: Ongoing efforts to create interoperability and medically compliant devices are moving from academic debate into regulatory practice. Firms considering clinical or safety-critical applications must align product development and clinical validation strategies with evolving standards.
Key market dynamics — what the report reveals
-
Commercial momentum: Investment in scale-up, patenting activity, and go-to-market infrastructure has accelerated. Notably, several market participants have advanced from R&D demonstrations to manufacturing and commercial deployments within the last 18 months, signaling a shift from experimentation to industrialization.
-
Concentration and competitive structure: The market shows moderate concentration. The top three firms account for roughly one-third of market activity, with the top five approaching roughly half — a structure that supports both competitive rivalry and partnership opportunities for challengers.
-
Standards and certification as adoption levers: ISO and industry-specific certification pathways are increasingly determining procurement decisions in regulated segments such as healthcare and environmental monitoring. Compliance is becoming a market-entry gatekeeper.
-
Hardware bottlenecks persist: Sensor drift, environmental sensitivity (temperature, humidity), and calibration overhead remain primary technical constraints that affect long-term reliability and operational cost. These are the issues procurement and engineering teams must solve in parallel with algorithmic improvements.
Competitive landscape — where incumbent and emerging vendors stand
The report includes a disciplined vendor assessment of core players shaping the ecosystem. Below we summarize strategic positioning without disclosing granular market splits.
-
Osmo (Elizabeth, NJ, USA) — Positioned as an AI-first digital olfaction company, Osmo has combined model-led scent mapping with a commercialization push. Recent actions include major patenting activity and the opening of a large headquarters and manufacturing facility in 2026, signaling an aggressive move to scale production and commercial deployment of an “Olfactory Intelligence” platform. For product teams, Osmo represents a vertically oriented competitor with strong IP and manufacturing intent.
-
Ainos, Inc. (Houston, TX, USA) — Ainos’ full-stack AI Nose platform and recent commercial module launch reflect a strategy of selling turnkey sensor modules plus cloud analytics via a SmellTech-as-a-Service model. Their emphasis on MEMS sensor integration and ppb-level sensitivity makes them a direct competitor for industrial and semiconductor use cases where detection limits and integration simplicity matter.
-
Aryballe Technologies (Grenoble, France) — With a focus on biomimicry, optics, and ML, Aryballe is notable for solutions oriented toward industrial monitoring and healthcare analytics. Their technology roadmap prioritizes robustness in noisy environments — a differentiator for quality-control buyers.
-
Alpha MOS (Toulouse, France) — A long-standing player in electronic noses and tongues, Alpha MOS brings deep domain expertise in sensory profiling and quality control. Large food and beverage firms continue to view Alpha MOS as a reliable partner for sensory analysis workflows.
-
Olorama Technology (Spain) — Focused on scent synthesis and multisensory experiences, Olorama targets entertainment and immersive media. Their patented synthesizer library and work in VR/AR position them as a leader for CX teams exploring olfactory augmentation.
-
Aroma Bit (Japan) — Known for odor-imaging sensor chips, Aroma Bit is a technology supplier for integrators seeking compact, low-power solutions.
-
The eNose Company (Netherlands) — With aeoNose and devices oriented to medical breath analysis, this firm illustrates the route to clinical validation and certification; they have redesigned products to comply with medical device standards and hold ISO 13485.
-
AIRSENSE Analytics GmbH (Germany) — Specializes in portable analyzers for environmental and industrial odor monitoring; a partner of choice for environmental compliance applications.
Regulatory, standards and ecosystem events to watch in 2026
-
Medical device frameworks: Regulatory classifications for olfactory diagnostics (for example, pathways equivalent to Class II devices in some jurisdictions) will materially affect time-to-market and evidence requirements. Clinical validation plans must be integrated early for any company pursuing healthcare applications.
-
Standards work: Ongoing international efforts are addressing sensor performance, calibration, and interoperability — developments that will reduce buyer friction but will also raise technical compliance costs for vendors that do not anticipate them.
-
Conferences as market accelerants: Industry forums and symposia scheduled in 2026 will catalyze alliances, standards progress, and early commercial partnerships. These venues are strategic touchpoints for business development and talent recruitment.
What the PW Consulting report delivers — practical, decision-ready content
Beyond market sizing and trend narrative, the report is explicitly constructed as a toolkit for corporate strategy teams. Key operational deliverables include:
-
A transparent market model with scenario sensitivity to inputs such as sensor cost declines, algorithm licensing fees, and regulatory time-to-approval — enabling CFOs to test capex vs. opex strategies.
-
Technology maturity and risk matrix mapping hardware, firmware, and AI components to deployment readiness for different industry verticals.
-
Vendor due-diligence playbooks and an RFP template for procurement teams evaluating sensor modules, synthesis systems, or analytics platforms.
-
Compliance and clinical pathway maps for organizations targeting medical or safety-critical certifications, including recommended evidence packages and typical timelines.
-
Use-case playbooks that include commercial models, unit-economics benchmarks, and go-to-market roadmaps for representative applications (quality control, diagnostics, CX/entertainment, and environmental monitoring).
-
A curated supplier and partner directory with capability profiles and suggested partnership archetypes (integrator, technology licensor, manufacturing partner).
Strategic recommendations for executives in 2026
-
Define the value boundary: Decide early whether to compete on hardware, software, or a combined platform. Owning the data layer — while outsourcing commodity sensing — often delivers the highest software-margin upside.
-
Invest in calibration and lifecycle management: Given sensor drift and environmental sensitivity, allocate R&D and operations resources to calibration-as-a-service, remote maintenance, and automated revalidation.
-
Build regulatory-first roadmaps for clinical and safety use cases: Integrate quality systems, clinical validation, and regulatory filing effort into product timelines rather than treating them as afterthoughts.
-
Pursue strategic partnerships: Co-development with specialists — for instance, a sensor OEM with a ML analytics provider — can compress product timelines and share validation burdens.
-
Hedge supply-chain risk: Secure alternative sources for core sensor components and consider localized manufacturing where certifications or scale require it.
-
Monitor IP landscapes and patent activity closely: Aggressive patenting has become a competitive lever; align IP strategy with business model options (licensing vs. exclusivity).
How to use this report in board-level conversations
We designed the report to be directly usable in executive decision cycles. Use the market scenarios to stress-test investment proposals, the vendor playbooks to structure procurement and partnership discussions, and the regulatory maps to estimate compliance-related capex and time-to-revenue. For strategy teams, the report’s actionable templates can reduce sourcing cycle time and improve the quality of go/no-go investment decisions.
Conclusion — a strategic preview, not the whole film
Digital olfaction is transitioning from laboratory curiosity to an industrially relevant technology stack with measurable market momentum. PW Consulting’s analysis shows a market that is growing meaningfully, with identifiable commercial pathways and practical engineering obstacles that can be mitigated with the right choices. This release is intended as a strategic preview: it signals the scale and direction of opportunity, profiles leading players, and offers a playbook for executives. For the granular market splits, vendor scorecards, and the operational templates that powers tactical decisions, access the full report and accompanying datasets on the PW Consulting site.
For detailed analysis of this topic, please visit the official page: Digital Olfactory technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Body Comfort System Market Reaches USD 100.26 Billion in 2025; Set to Expand at 7.11% CAGR to USD 162.19 Billion by 2032
By pmarketresearch, 2026-07-15
Worldwide Automotive Body Comfort System Market — Strategic Outlook for 2026 Decisions
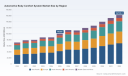
PW Consulting’s latest market study on the Worldwide Automotive Body Comfort System market establishes a clear, actionable foundation for corporate strategy in 2026. Using 2025 as the base year and a consistent historical window (2020–2025), the report quantifies an upswing from roughly USD 71.2 billion in 2020 to about USD 100.3 billion in 2025. Looking ahead, our 2026–2032 forecast models a compound annual growth rate (CAGR) of 7.11%, projecting the market to surpass USD 162.2 billion by 2032. These headline figures set the stage for a deeper, operationally focused discussion about where leadership and investment must land in the coming 12–18 months.
Worldwide Automotive Body Comfort System Market
Why this report matters for 2026 decision cycles
- Prioritizing R&D and product roadmaps: The growth profile and technology tailwinds identified in the study help OEMs and Tier‑1s prioritize development of thermal comfort, active seating, and sensor‑enabled occupant monitoring features that will meaningfully differentiate next‑generation vehicles.
- Strategic sourcing and supplier selection: The report arms procurement and sourcing teams with supplier scorecards, technology fit analyses, and risk indexes so they can rationalize vendor portfolios and negotiate from informed positions.
- M&A and partnership screening: Investors and corporate development teams receive a short list of capabilities that will unlock near‑term value (software platforms, domain controllers, low‑power communications, precision actuators) together with scenario analyses for consolidation plays.
- Regulatory and compliance planning: We map regulatory triggers—particularly those impacting occupant monitoring and electronics architectures—to product release schedules and certification milestones to avoid costly rework.
- Sustainability and materials transition: The report offers material substitution pathways and cost impact models tied to industry targets for recycled and renewable plastics, enabling procurement and engineering to operationalize sustainability goals without margin erosion.
Data-driven signals: what the numbers reveal (and what they intentionally leave to the report)
At headline scale, the market’s steady compound growth through 2032 is not uniform; it is being driven by a convergence of structural and tactical forces. Electrification increases the importance of HVAC and seat thermal management as battery‑powered vehicles reshape load management and comfort‑energy tradeoffs. Software‑defined vehicle architectures are creating new monetization vectors for comfort features (OTA updates, feature‑as‑a‑service), while new in‑cab sensors and control units turn what were mechanical features into software and electronics plays.
Worldwide Automotive Body Comfort System Market
Regulatory and standards developments are amplifying integration complexity. For example, the EU General Safety Regulation’s emphasis on Driver Monitoring Systems is accelerating the embedding of occupant monitoring functions into broader body and comfort electronics architectures. Likewise, next‑generation communications and transceiver standards (e.g., CAN FD SIC implementations aligned to the latest ISO edition) are enabling lower‑power modes and richer in‑vehicle sensor fabrics, which in turn influence module architecture and supplier selection.
Worldwide Automotive Body Comfort System Market
Material supply and sustainability targets are another near‑term focus. OEMs and suppliers are pushing to increase recycled and renewable plastics in interior trim and comfort components—programs we model explicitly to show both cost delta and carbon benefit across alternative sourcing scenarios. Taken together, these forces create both upside opportunities (new features, higher ASPs for software‑enabled comfort) and risks (component lead times, raw material price volatility, regulatory rework).
Competitive landscape — strengths, gaps and strategic moves
The market remains competitive but not hyper‑concentrated. Our concentration metrics indicate a market in which the top three players account for roughly one‑third of global share, and the top five approach the mid‑40s percentage range—enough scale for incumbents to influence standards and supply chains, but also enough fragmentation to enable specialist challengers and vertical integrators.
- Gentherm (United States): A specialist in seat thermal management and active cooling, Gentherm’s strong IP base in thermal comfort positions it well for OEM programs seeking differentiated HVAC/seat bundles. Expect continued investment in thermoelectric and active cooling modules and in licensing arrangements for platformized thermal systems.
- Lear Corporation (United States): Lear’s complete seating systems and integration capability—combining mechanical architectures with electronics for massage, lumbar and dynamic adjust—make it a natural partner for OEMs seeking turnkey seating solutions. The company’s scale supports system‑level integration and margin capture on electrical architectures.
- Adient plc (Ireland): Adient has doubled down on ergonomic and safety‑linked comfort features, releasing new seating solutions that integrate safety pretensioners and smart airbags. Their August 2025 product introduction highlights a strategy that blends occupant protection with comfort as a combined differentiation vector.
- FORVIA (Faurecia), Magna, Continental, Bosch, Denso, Valeo: These diversified Tier‑1s leverage broad portfolios—seat systems, HVAC, body electronics, and sensing—to offer integrated packages that align with OEM consolidation strategies. Their advantage lies in systems integration, global manufacturing footprint, and relationships across powertrain and electronics domains.
- Toyota Boshoku, Kongsberg, Alfmeier Präzision: These players bring focused capabilities—precision actuators, pneumatic components, and seat manufacturing expertise—that are critical to modular architectures and cost optimization strategies.
Recent industry commentary underscores strategic urgency. A March 2026 BCG industry study highlighted interior and body systems as high‑leverage areas for OEM differentiation, reinforcing the timing for investment decisions. Against this backdrop, the market’s concentration dynamics suggest acquisition opportunities for firms seeking either to add software/electronics capability or to broaden product portfolios into adjacent comfort domains.
What the report contains — practical, executable deliverables
- Validated market sizing & scenario‑based forecasts: A baseline and three alternate scenarios (conservative, base, upside) for 2026–2032 with sensitivity to EV penetration, regulatory timing and material price shocks.
- Supplier & capability heatmaps: Comparative profiles across electrical control units, actuators, sensors, and thermal systems covering technology readiness, margin bands, IP ownership and partnership fit.
- Technology and architecture playbooks: Recommended reference architectures for body control and comfort subsystems, including CAN FD/ethernet edge tradeoffs, domain controller partitioning and software update paths.
- Cost and materials models: Bottom‑up BOM and cost‑to‑serve models, plus scenarios for recycled‑content adoption and alternate sourcing strategies that show total landed cost and CO2 implications.
- Regulatory impact matrices: Time‑phased maps linking regulations and standards to required product features, testing regimes, and certification windows.
- Commercial & go‑to‑market frameworks: Pricing strategies for feature bundles (hardware + software), subscription monetization options, and channel strategies for Tier‑1/OEM partnerships.
- Actionable M&A signal lists: Capability gaps where targeted acquisitions would improve time‑to‑market, plus diligence checklists aligned to performance and technology metrics.
To honor the “trailer” principle and preserve the strategic value of our granular analyses, detailed regional and application splits, supplier share tables, and per‑segment revenue figures are reserved for the full report and bespoke client deliverables.
How executives can act in 2026 — six prioritized moves
- Rebase product roadmaps on software and systems integration: Reallocate R&D budgets to control software stacks, OTA capability and domain controllers that host comfort features, rather than only on mechanical upgrades.
- Hedge supply risk with dual‑sourcing and localized content: Identify single‑sourced precision components and secure secondary suppliers or near‑shore capacity for critical actuators and control modules.
- Embed sustainability targets into sourcing contracts: Negotiate recycled‑content clauses and long‑term offtake agreements to smooth price and certification risks tied to polymer supply.
- Accelerate partnerships for occupant sensing: Integrate driver/occupant monitoring early with body electronics roadmaps to meet regulatory windows and to unlock occupant‑aware comfort features.
- Use M&A to fill software/electronics gaps: Target small‑to‑mid cap specialists with proven domain controller IP or sensor fusion stacks to compress time‑to‑market for higher‑margin software services.
- Operationalize cost‑to‑feature tradeoffs: Use our BOM models to assess where premium comfort features can be adopted with minimal margin impact (e.g., modularizing heating and ventilation across vehicle platforms).
Final note — how PW Consulting’s intelligence translates into decisions
For 2026 planning cycles, the combination of validated headline market growth (a multiyear compound expansion at ~7.11% CAGR), regulatory accelerants, and technology inflection points makes the body comfort domain a high‑priority investment area. Executives who align product roadmaps, supplier strategies and M&A activity to the signals in this study will create disproportionate optionality: from new revenue streams enabled by software to lower operational risk through smarter sourcing.
PW Consulting’s full report contains the granular segmentation, regional and application detail, and supplier share tables required to operationalize these recommendations. Clients who need immediate decision support can request tailored briefings, scenario workshops, and due diligence packages that map directly to program timelines and capital allocation cycles for 2026.
For access to the complete dataset, supplemental models, and to schedule a strategic briefing, please refer to the PW Consulting report page or contact our Automotive Practice team.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Body Comfort System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Oblong Jar Market to Expand at a 5.85% CAGR During 2026–2032, New Report Finds
By pmarketresearch, 2026-07-15
Worldwide Oblong Jar Market — Strategic Preview for 2026 Decision Makers
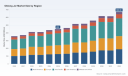
PW Consulting’s newest market study on the Worldwide Oblong Jar Market (base year 2025) delivers an actionable intelligence package for senior executives, corporate strategists, and investment committees preparing plans and capital allocations in 2026. The market has demonstrated steady expansion through the recent cycle and—based on our scenario modelling—enters the 2026 decision window with a clear, investible trajectory: after rising from the early‑2020s level to an estimated USD 450 million in 2025, the market is projected to continue growing at a compound annual rate of approximately 5.85% across the forecast horizon (2026–2032).
Worldwide Oblong Jar Market
Why this report matters for 2026 strategies
-
Timing: 2026 is the inflection year for packaging players facing simultaneous cost, regulatory and sustainability pressures. The report isolates actionable moves that fit a 12–36 month execution cadence—precisely the window in which boardroom decisions made now will begin to show impact.
Worldwide Oblong Jar Market -
Commercial focus: We translate market momentum into commercial priorities—how to pivot product portfolios, where to capture margin through design and procurement, and what partnership models accelerate market access.
Worldwide Oblong Jar Market -
Risk‑calibrated planning: Our supply‑side stress tests and scenario sets let leaders recalibrate CAPEX and sourcing strategies against raw material spikes, changing trade flows and Extended Producer Responsibility (EPR) regimes.
Executive snapshot — macro picture and concentration
The oblong jar market is mature but dynamic. After a period of steady recovery and product substitution trends in the early 2020s, total industry revenue stood close to USD 450 million in 2025 and—under our central forecast—moves toward a materially larger market by 2032. Market structure remains fragmented: the three‑firm and five‑firm concentration ratios are low, underscoring a competitive landscape where national and regional players retain strong negotiating power with large consumer goods customers. That fragmentation creates both opportunity for value consolidation and risk for firms that fail to differentiate.
What’s inside the full report (practical deliverables)
-
Market sizing and 7‑year forecast (2026–2032) built from bottom‑up SKU and channel modelling, with sensitivity bands tied to raw material and regulatory scenarios.
-
Go‑to‑market playbooks for manufacturers and converters that include pricing frameworks, assortment rationalization templates, and retail pack‑out optimization checklists.
-
Supplier risk matrix and near‑term mitigation tactics (dual sourcing, strategic inventory, contract clause templates) calibrated to volatility observed across glass and plastics supply chains.
-
Sustainability and compliance toolkit: practical steps to meet looming EPR obligations, a roadmap for recycled content implementation, and a supplier audit checklist to verify recyclability claims.
-
Scenario planning engine and M&A screening filters that identify target profiles most likely to accelerate scale or capability (e.g., circularity tech, automation in thermoforming, specialized neck finish tooling).
-
Commercial benchmarking and margin levers for packaging buyers—detailing where to capture 1–3% incremental margin through specs simplification, fill‑line harmonization and closure standardization.
Competitive landscape — strategic implications for 2026
The market’s leading suppliers and distributors occupy distinct roles across scale, channel focus and technical capability. PW Consulting’s assessment of key firms surfaces tactical plays buyers and competitors should anticipate.
- Berlin Packaging (United States): a high‑volume supplier specializing in warehouse‑retailer formats. Their scale orientation makes them a natural partner for CPG players seeking margin‑effective packaging at high throughput; competitors should expect continued emphasis on integrated service offerings (warehousing + packaging) that blur the supplier/customer line.
- The Cary Company (United States): known for industrial‑grade plastic oblong jars with functional features (handles, wide mouths). Their strength is niche product engineering—an area ripe for premiumization and industrial OEM partnerships.
- Parkway Plastics (Parkway Jars) (United States): legacy expertise in reusable and recyclable plastics. Parkway’s long heritage positions them to lead on circular packaging pilots, especially where brand customers demand both reuse and recycled content options.
- SKS Bottle and Packaging (United States): a broad catalog provider across glass and plastics; their value rests in fast SKU availability and finishing options, serving mid‑market formulators that prioritize speed to shelf.
- O.Berk (United States): established for pharmaceutical and specialty personal‑care jars—expect continued traction where compliance and traceability matter most.
- Silgan Plastics (United States): strong in food and condiment segments; their manufacturing depth makes them a key supplier for large food processors adapting to changing service levels and sustainability targets.
- FH Packaging (United States): global reach across glass and plastic jar formats; their strategic playbook centers on bundling design, compliance and logistics for multinational customers.
- Illing Company (United States): focused on industrial application containers; their portfolio is attractive to B2B customers needing technical resin expertise and custom tooling.
For buyers, the strategic takeaway is clear: partner selection in 2026 will be a choice between scale/value (cost and logistics), technical differentiation (closures, engineered features), and circularity (recycled content, reuse models). Suppliers should align one of these value propositions as a core competency and build partnerships to fill gaps.
Regulatory and raw‑material dynamics that will shape 2026 moves
-
Extended Producer Responsibility (EPR): multiple U.S. states have implemented EPR regimes that shift end‑of‑life costs onto producers. California’s phased recycling targets (30% by 2028, 40% by 2030, 65% by 2032) are a bellwether—brands and packagers must embed compliance costs into 2026 price models and product roadmaps.
-
Raw material pressures: industry indicators point to continued pressure in glass manufacturing inputs (for example, producer price indices are elevated), and mass‑produced soda‑lime jars trade at commodity FOB ranges that compress low‑margin converters. Our stress tests model both short spikes and prolonged price regimes to indicate when cost pass‑through is viable versus when product redesign is necessary.
-
Policy uncertainty: states continuing to consider EPR (and new policy layers) will create asynchronous compliance burdens—favour those supplier relationships that include compliance support and flexible contract terms.
Concrete 2026 playbook—five priority actions
-
Re‑baseline packaging economics: update costing models to include EPR liabilities, realistic recycled content premiums, and a 12–18 month raw‑material stress surcharge schedule. Tie these models directly into commercial negotiations.
-
Prioritize a three‑to‑five SKU rationalization: small reductions in SKU complexity can unlock outsized savings on tooling, fill‑line changeover and freight. Our benchmarking shows this is one of the fastest ways to crystallize margin improvement in the near term.
-
Accelerate circular pilots with measurable KPIs: design 6–12 month pilots for recycled content and reuse programs with grocery or direct‑to‑consumer partners—embed obligations and exit criteria up front.
-
Lock strategic supply options: enter selective medium‑term purchase agreements that incorporate indexed pricing, capacity reservation, and optionality for material substitution between PET, polypropylene and glass where technically feasible.
-
Scan for bolt‑on M&A: prioritize targets that add automation, secondary finishing capabilities (neck/thread tooling), or downstream recycling aggregation—these generate the quickest ROI in a fragmented supplier market.
What we withhold—and why
In this preview we have deliberately showcased frameworks, strategic recommendations and headline market trajectories to help you prioritize boardroom attention in 2026. To preserve the integrity of ongoing commercial negotiations and to ensure our clients derive proprietary advantage, we do not publish the detailed sub‑segment revenue splits and region/application percentiles in public summaries. The full report contains the granular breakdowns, channel and SKU‑level forecasts, and supplier scorecards that undergird the strategic guidance above.
How to access the full intelligence
For companies making procurement, portfolio or investment decisions in 2026, accessing the full data pack is the difference between an informed hedge and a surprised balance sheet. PW Consulting offers the comprehensive report, downloadable datasets, and bespoke briefing sessions with our senior analysts. Contact your PW Consulting representative or visit our report page to arrange a tailored walk‑through and to obtain the confidential appendices (including SKU‑level demand curves, supplier scorecards, and the scenario modelling workbook).
PW Consulting’s Worldwide Oblong Jar Market study is designed to convert market insight into boardroom action. If your 2026 plan touches packaging, procurement, sustainability compliance or M&A in this space, this is the intelligence you should be building your decisions on.
For detailed analysis of this topic, please visit the official page: Worldwide Oblong Jar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Bandage Contact Lenses Market to Expand from USD 656.15 Million in 2025 to USD 1,019.65 Million by 2032 at a 6.5% CAGR
By pmarketresearch, 2026-07-15
Worldwide Bandage Contact Lenses Market — Strategic Briefing for 2026 Decisions
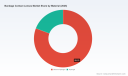
As healthcare systems reset priorities following a period of accelerated surgical throughput and evolving reimbursement protocols, the bandage contact lens market is entering a phase of sustained expansion. Our new PW Consulting report, using 2025 as the base year, models the market through 2032 and shows the global opportunity growing at a compound annual growth rate (CAGR) of approximately 6.5%. Measured in USD (Million), the total market expands from mid‑2020s levels into a near‑billion dollar opportunity by the end of the forecast window. For commercial leaders, clinical strategy teams, and corporate development executives planning in 2026, this trajectory requires calibrated choices across regulatory positioning, product portfolio, go‑to‑market execution, and potential inorganic moves.
Worldwide Bandage Contact Lenses Market
Why this market matters for 2026 strategy
-
Therapeutic and protective lenses are no longer a narrow adjunct to ophthalmic surgery — they are a distinct clinical intervention with defined reimbursement pathways and regulatory precedent. Market growth is being driven by a combination of procedure volumes, expanded therapeutic indications, and material science advances that improve patient comfort and wear duration.
Worldwide Bandage Contact Lenses Market -
Consolidation and incumbent strength characterize the competitive landscape. The top three and top five players together account for a substantial majority of market revenue, producing a market structure that favors scale, distribution reach, and regulatory footprints. For new entrants and mid‑sized participants, this concentration shapes achievable strategies — from niche specialization to M&A‑enabled scale.
Worldwide Bandage Contact Lenses Market -
Regulatory clarity for therapeutic indications and predictable reimbursement coding create an environment where differentiated product claims (oxygen transmissibility, moisture retention, wear time) can translate to commercial advantage — provided clinical and real‑world evidence programs are aligned with payer expectations.
Key market signals captured by the report
-
Robust historical growth and forward momentum: Our model tracks the market from 2020 through 2025 and projects through 2032, reflecting steady expansion driven by clinical adoption and new product entries. Stakeholders should interpret this as an opportunity window for investment in both incremental innovation and scale plays.
-
Regulatory and reimbursement tailwinds: Silicone hydrogel lenses with established therapeutic indications have benefitted from clear regulatory pathways and are typically cleared via 510(k) mechanisms for Class II classification. Reimbursement constructs exist — coding such as CPT 92071 for fitting of contact lenses for ocular surface disease, and supply reporting via ancillary codes (for example, commonly used supply codes depending on payer) — which create a viable commercial model for therapeutic lenses when claims and documentation are properly aligned.
-
Material and technology differentiation: High Oxygen Transmission (Dk/t), moisture‑locking polymer chemistry, and comfort technologies are the technical levers that matter. These attributes influence not only clinical preference but also extended wear protocols and downstream patient outcomes — important inputs for pricing and payer conversations.
-
Competitive dynamics and recent regulatory events: The market continues to see product clearances and catalog extensions that expand the baseline of therapeutic options. Notable regulatory clearances in late 2025 expanded the pool of FDA‑cleared silicone hydrogel options for therapeutic wear, and product catalog updates broadened both human and veterinary bandage offerings. Such events alter the competitive calculus for market entry timing and positioning.
Competitive landscape — what incumbents and challengers mean for your strategy
-
Global leaders with therapeutic portfolios bring brand trust, clinician relationships, and regulatory footprints that make them formidable in hospital and ASC channels. These companies have product families that are explicitly indicated for corneal protection, pain relief, and post‑surgical healing, underpinned by longstanding clinician familiarity and distribution networks.
-
Specialist manufacturers and regional players are frequently more agile on product customization, alternative materials, and veterinary or first‑aid niches. Their strengths lie in responsiveness to clinician feedback, flexible manufacturing, and targeted channel strategies — attributes that can be amplified with the right partnerships or targeted capital.
-
Clinical adoption patterns favor products with clear therapeutic labeling, evidence of safety for extended wear, and operational ease for fitting and follow‑up. Companies that combine these elements with clear reimbursement support materials (coding guides, documentation templates) shorten the sales cycle in clinical environments.
-
Competitive snapshots in our report profile global incumbents, specialist manufacturers, and emerging entrants, mapping their clinical claims, regulatory status, distribution reach, and recent product or regulatory developments. This intelligence is presented to help executives assess acquisition targets, partnership candidates, and white‑space product opportunities without disclosing proprietary segment allocations in this executive summary.
What PW Consulting's report delivers — practical content for action in 2026
-
Integrated market model: A granular, downloadable financial model covering 2020–2032 with base year 2025 normalization, scenario toggles (conservative / base / aggressive), and sensitivity analyses for price, volume, and reimbursement uptake. This is the primary tool for sizing investment cases and forecasting returns on product launches or acquisitions.
-
Regulatory and reimbursement playbook: A consolidated matrix of regulatory pathways, device classification implications, recent 510(k) precedents, and payer coding guidance (including practical advice on documentation and claim submission strategies) tailored to clinical use cases such as post‑operative care and ocular surface disease.
-
Commercial go‑to‑market toolkits: Field‑tested launch plans for hospital, ambulatory surgery centers, specialty retailers, and dental/medical cross‑referral channels; clinician education blueprints; and a payer engagement framework that translates clinical benefit into reimbursable value propositions.
-
Competitive and M&A intelligence: Company profiles, capability matrices, valuation heuristics for mid‑market acquisitions, and an M&A heatmap that highlights where consolidation and bolt‑on opportunities are likely to create near‑term scale advantages.
-
Supply chain and manufacturing risk analysis: Assessment of critical raw materials, capacity constraints, and regulatory compliance implications for sterile contact lens manufacturing — with mitigation pathways for near‑term disruptions and long‑term capacity expansion planning.
-
Clinical evidence roadmap: Recommended study designs, endpoints aligned with payer expectations (pain scores, epithelial healing rates, re‑intervention reduction), and real‑world evidence strategies to accelerate label expansion and market uptake.
Strategic imperatives and recommended actions for 2026
-
Prioritize regulatory clarity and label strategy: For companies planning new therapeutic claims or entering key markets, securing the appropriate regulatory pathway early reduces commercial friction. Invest in pre‑submission engagements and build dossiers that map clinical endpoints to payer value statements.
-
Align evidence generation with reimbursement mechanics: Demonstrating not only safety and performance but also economic value (reduced clinic visits, faster recovery, lower complication rates) materially strengthens negotiations with payers and hospital procurement teams.
-
Consider selective M&A to overcome scale barriers: Given the market’s concentration profile, inorganic moves can rapidly add distribution, regulatory clearances, or material technology. Use the report’s M&A heatmap to identify targets that close capability gaps without duplicative overlap.
-
Differentiate on clinician support and commercial enablement: Provide turnkey documentation for coding and reimbursement, training modules for fitting and follow‑up, and bundled offers for ASC and hospital contracts to lower barriers for clinician adoption.
-
Design product roadmaps that target operational simplicity: Ease of fitting, clear labelling for therapeutic wear, and supply formats that integrate with existing ophthalmic workflows improve uptake in busy surgical environments.
Why PW Consulting’s report is the right decision support for 2026
Our report translates market momentum into executable options. It combines a rigorous, auditable forecast with tactical playbooks — enabling executives to prioritize spend across R&D, market access, and commercial channels in a way that is both defensible to boards and actionable in the field. Importantly, our approach follows the “trailer” principle: we present the strategic logic, the tools you need to evaluate opportunities, and the operational templates to act — while reserving the full dataset and interactive model for report subscribers and clients who require the primary inputs for transaction or launch planning.
Next steps
-
For executives seeking to stress‑test product launches, evaluate acquisition targets, or define 2026 P&L impacts, the full PW Consulting report and accompanying model provide the necessary primary data and scenario capabilities. Access to the complete dataset includes regional, application, and material segment breakdowns, as well as company revenue estimates and deal comparables.
-
Contact our team to arrange a briefing or to license the full report and financial model. We can deliver a tailored workshop to convert insights into a prioritized 90‑day action plan aligned with your commercial and clinical objectives for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Bandage Contact Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Wearable Power-Assisted Exoskeleton Robots Market Poised to Grow at 24.85% CAGR, Reaching USD 2.285 Billion by 2032
By pmarketresearch, 2026-07-15
Wearable Power-Assisted Exoskeleton Robots Market — Strategic Briefing for 2026 Corporate Decision-Makers
Market snapshot and near-term runway
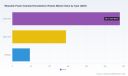
By PW Consulting's assessment, the global market for wearable power-assisted exoskeleton robots reached an estimated USD 482.5 Million in 2025 (base year). With a robust compound annual growth rate (CAGR) of approximately 24.85% projected through our 2026–2032 forecast window, the market is set to scale into the low‑billions by the end of the decade. This trajectory is being driven by converging forces — accelerating clinical validation, expanding industrial adoption for ergonomic augmentation, and stepped-up product innovation in lightweight materials and embedded AI control.
Wearable Power-Assisted Exoskeleton Robots Market
Why this report matters to 2026 strategy
- Timing: 2026 is a pivot year when trial evidence, regulatory precedents and early reimbursement decisions coalesce into investable commercial pathways. Senior leaders who translate these signals into focused pilots and strategic partnerships now will capture disproportionate learning and customer mindshare.
- Prioritization: With limited deployment budgets and competition for clinical trial and industrial pilot slots, the report helps executives prioritize segments, use-cases and customer cohorts that convert fastest to recurring revenue.
- Risk-adjusted planning: The growth profile is steep, but capital intensity, integration complexity and regulatory hurdles remain. Our analysis provides scenario-based stress-testing to align investment pacing with program milestones and cash‑flow tolerances.
What PW Consulting’s Wearable Exoskeleton Report delivers
This is not a high-level market memo — the report is designed to be a go‑to operational playbook for commercial, clinical and corporate development teams preparing choices in 2026. Key deliverables include:
Wearable Power-Assisted Exoskeleton Robots Market
- Market sizing and demand curves: a detailed top‑down and bottom‑up assessment anchored to 2025 base metrics, with transparent assumptions and sensitivity checks for uptake rates, reimbursement adoption and unit economics.
- Adoption path maps: staged adoption frameworks for medical rehabilitation, industrial augmentation and defense uses, identifying typical buyer journeys, procurement cycles and integration points with existing workflows.
- Go‑to‑market playbooks: tailored commercial strategies for OEMs, startups and system integrators — covering channel models, pricing approaches, pilot design templates, and outcome‑based contracting constructs.
- Regulatory and reimbursement roadmaps: pragmatic guides through regulatory classifications, key safety controls, and payer engagement sequences; includes a repository of precedent decisions and payer coverage language templates.
- Technology and supply‑chain diagnostics: component cost drivers, sourcing risk heatmaps, and engineering benchmarks — including material and actuator trends that materially affect device mass, battery endurance and per‑unit cost.
- Vendor capability matrices and M&A playbook: in‑depth profiles, capability gaps, integration risks and a transaction scoring tool to evaluate buy vs. partner vs. build choices.
- Commercial KPIs and ROI models: downloadable financial models and clinical outcome-to-revenue conversion calculators designed for board-level decision support.
Competitive landscape — who to watch and why
The industry remains concentrated among specialized robotics and medtech firms, with the leading players capturing a substantial share of established commercial and clinical deployments. Rather than publish a static leaderboard, the report analyzes competitive vectors — technology stack, clinical evidence depth, distribution reach and channel partnerships — to show where each rival is positioned to win specific use-cases.
Wearable Power-Assisted Exoskeleton Robots Market
- German Bionic (Augsburg, Germany): pushing AI-enabled worker assistance solutions with a focus on dynamic, task‑aware support. Recent trade‑show activity and product showcases underline a strategy of close collaboration with large industrial employers to demonstrate safety and productivity gains.
- Wandercraft (Paris, France): differentiates with self‑balancing control architectures targeted at early mobilization and complex rehabilitation scenarios. Active clinical pilots in intensive care and mobility rehab mark it as a company to monitor for downstream hospital adoption.
- Ekso Bionics (San Rafael, USA): with bifurcated product lines across medical and industrial spaces, Ekso is an archetype of a firm seeking to translate rehabilitation clinic credibility into broadened enterprise solutions for worker augmentation.
- Lifeward / ReWalk (Israel / USA): remains a clinical poster‑child for personal mobility exoskeletons, with recent long‑term safety data strengthening reimbursement conversations and adoption among spinal cord injury beneficiaries.
- CYBERDYNE (Japan), Ottobock (Germany), B‑Temia (Canada), Parker Hannifin (Indego), Auxivo (Switzerland), Fourier Intelligence (Singapore): collectively these firms illustrate varied strategic postures — from bioelectric signal control to lightweight industrial devices — and form the competitive fabric that buyers evaluate for reliability, service coverage and evidence packages.
Recent, company‑level developments (e.g., clinical enrollments, trade show showcases, and the publication of long‑term safety datasets) are flagged in the report and mapped to prospective procurement triggers — enabling procurement and clinical leaders to time pilots and submissions for maximum impact.
Regulatory, reimbursement and materials dynamics
Three non‑market forces will shape 2026 decisions:
- Regulation: Established device classifications and special controls are reducing approval uncertainty in rehabilitation use-cases. Our regulatory playbook translates classification precedents into product development requirements and testing priorities.
- Reimbursement: Early payer approvals for personal exoskeletons are changing the calculus on total addressable market and unit economics. The report includes tracer cases showing how outcome metrics were translated into coverage decisions and the negotiation levers that mattered.
- Materials & components: Advances in composites, actuator designs and energy density are reducing device weight and improving usability — the report quantifies the performance thresholds (for example, contemporary engineering targets for per‑leg mass and battery endurance) that unlock broader end‑user acceptance, and maps supplier landscapes where sourcing constraints could bottleneck scale.
Technology, service and integration imperatives for 2026
Our fieldwork and interviews highlight three imperatives for winning deployments in 2026:
- Outcome‑centric device design: buyers (clinicians and industrial safety managers alike) prioritize demonstrable improvements in functional outcomes, not just technical specs. Embedding robust data capture and standardized outcome measures into devices reduces procurement friction.
- Service and ecosystem play: successful vendors are those that combine hardware with training, integration services and outcome-based contracting. Early adopters value vendors who can deliver predictable onboarding and measurable productivity or functional improvement within defined time horizons.
- Interoperability and standards: as installations grow, interoperability with electronic health records, workforce management systems and industrial safety platforms becomes a competitive differentiator. Our recommendations include concrete API and data standards adoption paths to minimize integration cost.
Actionable recommendations for executives planning 2026 moves
To convert growth projections into durable market positions, boards and executive teams should consider the following prioritized actions this year:
- Run 2–3 high‑quality pilots that embed clinical or productivity endpoints into contracts; design pilots to produce publishable evidence within 9–12 months to accelerate payer and enterprise credibility.
- Secure strategic supplier agreements for critical lightweight components to de‑risk time to scale and protect margins as demand accelerates.
- Negotiate outcome‑linked pilot terms with early enterprise customers to share upside and reduce buyer resistance; pair pilots with training and service guarantees to shorten the path to renewal.
- Invest in a centralized data and analytics capability to capture usage, safety and outcomes; these data will be the currency in payer conversations and enterprise renewals.
- Use M&A selectively to fill capability gaps (service networks, clinical trial expertise, or key IP) rather than as a substitute for building in‑house commercialization capabilities.
Why PW Consulting’s report is a unique tool for 2026
PW Consulting has combined primary interviews with device manufacturers, payers and early adopter customers, granular supply‑chain analysis, and a transparent financial model calibrated to observed procurement behaviors. The result is an executable intelligence product — not merely forecasts. Companies will find in it the templates, scenario models and negotiation playbooks needed to convert the market’s rapid growth into profitable, defensible revenue streams.
Next steps and how to access the full intelligence
This briefing is a strategic précis — the full report contains the granular segmentation, proprietary scenario models, company scorecards and downloadable financial tools that your commercial, clinical and corporate development teams can use immediately. For executives preparing board memos, pilot funding requests or M&A diligence in 2026, the report shortens time‑to‑decision and reduces execution risk.
To request a copy of the full report or to schedule a briefing with PW Consulting’s exoskeleton practice team, please follow the link on our official distribution page where you can also access executive summaries and sample model extracts.
For detailed analysis of this topic, please visit the official page: Wearable Power-Assisted Exoskeleton Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com