

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting Forecast: Worldwide Signature Verification Market to Grow at 22.01% CAGR — From USD 2,405.96 Million in 2025 to USD 9,684.03 Million by 2032
By pmarketresearch, 2026-07-15
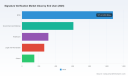
Worldwide Signature Verification Market — Strategic Outlook for 2026: PW Consulting Reveals Actionable Intelligence for Decision-Makers
PW Consulting’s latest market research, the Worldwide Signature Verification Market report (base year: 2025), delivers a pragmatic roadmap for executives, product leaders, compliance officers, and investors preparing strategic choices in 2026. The market’s rapid expansion — underpinned by a 22.01% compound annual growth rate and a multi‑billion dollar trajectory from 2025 into the latter half of the decade — is creating both near‑term opportunities and structural strategic challenges. This release summarizes the report’s operational value and highlights the key competitive and regulatory dynamics that will shape decision‑making next year. For full segment tables, vendor scorecards, and interactive models, please consult the source report.
Worldwide Signature Verification Market
Why 2026 Is a Strategic Inflection Point
The signature verification market has moved beyond niche forensic services into mainstream enterprise infrastructure. By the close of the report’s base year, the market had scaled into a sizeable multi‑million dollar industry and is forecast to accelerate materially in 2026 and beyond. This growth is being driven by accelerating digitization in heavily regulated verticals, expanding adoption of biometric and behavioral analytics, and heightened regulatory scrutiny that raises the bar for auditability and traceability of electronically executed agreements.
Worldwide Signature Verification Market
-
Consolidating demand from regulated industries: New and updated regulations in both Europe and the U.S. are compelling regulated actors to strengthen signature verification architectures as part of larger digital identity programs.
Worldwide Signature Verification Market -
Technology maturation: AI/ML, cloud platforms, and biometric capture technologies are moving verification from deterministic rule sets to probabilistic, continuous‑assurance models that scale across customer journeys.
-
Market structure: The market exhibits moderate concentration — the top three vendors control a meaningful but not dominant share, and the top five consolidate a clear majority — a structure that signals both room for scale‑ups and continued specialist innovation.
What This Report Helps You Do in 2026
PW Consulting designed this report as a decision‑ready toolkit. It goes well beyond surface metrics to deliver practical frameworks you can apply immediately:
-
Investment prioritization: Scenario‑based revenue and cost models that quantify outcomes for organic R&D vs. inorganic growth (M&A, partnerships) under conservative, base, and aggressive adoption scenarios.
-
Product roadmaps and RFP templates: Feature‑level prioritization matrices derived from buyer demand signals across regulated verticals to accelerate product‑market fit.
-
Compliance playbooks: Step‑by‑step adoption checklists aligned to updated eIDAS 2.0 requirements and U.S. regulatory guidance, enabling legal and compliance teams to fast‑track validated deployment plans.
-
Operationalization blueprints: Integration checklists and sample API design patterns for embedding verification services into transaction flows, with estimated implementation timelines and change management risks.
-
Procurement and vendor evaluation: Side‑by‑side vendor profiles, capability heatmaps, proof‑of‑concept scoring rubrics, and negotiable commercial terms to reduce buyer procurement cycle times.
-
Fraud and fraud‑loss modeling: Use‑case specific analytics to quantify potential improvements in loss prevention and KYC throughput when moving from legacy manual review to automated verification pipelines.
Regulatory and Technology Drivers: What to Watch in 2026
-
eIDAS 2.0 and interoperable wallets: Europe’s move to qualified trust services and mandatory digital identity wallets is creating a compliance imperative and integration opportunity for vendors that can prove chain‑of‑trust and wallet interoperability.
-
FDA and sectoral audit demands: Finalized guidance on electronic records and signatures in clinical investigations heightens demand for high‑assurance audit trails in the life sciences sector, accelerating enterprise deployments of advanced signature verification.
-
Biometric and dynamic verification: Dynamic signature verification — which captures behavioral biometric markers such as speed, pressure, and stroke order — is projected to lead technology adoption, representing the preferred approach for high‑security authentication in many enterprise use cases.
-
Software and cloud dominance: Software‑centric verification solutions, buoyed by AI and cloud integration, are expected to command a significant majority of new deployments due to scalability, rapid iteration, and centralized governance.
Competitive Landscape — Who’s Shaping the Market
The market’s competitive map is a mix of large platform incumbents, specialized analytics providers, and emerging biometric innovators. PW Consulting’s vendor analysis synthesizes strategic positioning, go‑to‑market motion, technology differentiation, and M&A posture to provide a clear view of where each vendor fits into buyer architecture patterns.
-
Platform incumbents (examples): These firms bring broad document and agreement ecosystems; they win where customers value integrated workflows, deep partner networks, and enterprise contracts. Their value is in scale, ecosystem integration, and trust services.
-
Security and identity specialists: Firms with deep PKI, identity verification, and biometric capabilities target regulated buyers that require rigorous proof of identity and long‑term auditability. They are winning head‑to‑head where compliance is non‑negotiable.
-
AI/ML and capture innovators: Startups and mid‑sized vendors focused on advanced signature analytics and real‑time fraud detection continue to compete on the quality of behavioral models and the ability to embed into payment and onboarding flows.
Recent market activity underscores these dynamics. In 2025, leading vendors expanded portfolios to emphasize cloud‑based platforms and AI‑driven verification. Strategic funding rounds and product launches further bolstered capabilities in image and signature analytics. Meanwhile, regulatory clarifications — notably FDA guidance and regional trust‑service mandates — have catalyzed enterprise procurement cycles in life sciences and public sector contracts.
Strategic Implications and Recommended Actions for 2026
For executives planning 2026 moves, PW Consulting recommends a bifurcated approach: accelerate compliance‑driven adoption where near‑term revenue is visible, and build longer‑term defensible differentiation by investing in data, models, and ecosystem partnerships.
-
For product leaders: Prioritize dynamic signature capabilities and SDK/API ergonomics to simplify integration into customer journeys. Invest in model explainability and forensic tools to satisfy auditors and legal teams.
-
For go‑to‑market teams: Tailor propositions by industry—particularly regulated verticals such as healthcare, financial services, and public sector—and craft outcome‑based commercial models (e.g., trial‑to‑transaction pricing, SLA‑backed performance metrics).
-
For corporate development: Consider tuck‑ins that close capability gaps in biometric capture, explainable AI, or regional trust services. The market’s concentration levels indicate that targeted acquisitions can meaningfully move share without triggering incumbent countermeasures.
-
For risk and compliance officers: Use the report’s compliance playbooks to map gaps to eIDAS 2.0 and FDA expectations and to prioritize remediation efforts that are highest impact for audit readiness.
-
For investors: Favor businesses with clear pathways to recurring revenue, verticalized go‑to‑market strategies, and demonstrable compliance credentials; the underlying growth profile supports multiple expansion for winners that demonstrate scale and stickiness.
Report Deliverables — Practical Assets Included
To support rapid execution in 2026, the PW Consulting report bundles a set of deployable assets:
-
Interactive market models with scenario toggles and sensitivities for ARR, CAC, and payback across multiple adoption curves.
-
Vendor scoring matrix with technical and commercial attributes, plus a shortlist of recommended partners by use case.
-
Implementation playbooks, RFP templates, and pilot evaluation frameworks to reduce time‑to‑production risk.
-
Regulatory readiness checklist aligned to eIDAS 2.0, FDA guidance, and other jurisdictional requirements.
-
Customer success and ROI calculators to make the business case for procurement committees and boards.
Conclusion — From Insight to Action
In 2026, signature verification will be a core attribute of secure digital commerce and regulated digital workflows. The market’s strong growth fundamentals create clear opportunities, but winners will be those that convert regulatory pressure and technology advances into defensible, enterprise‑grade products and services. PW Consulting’s Worldwide Signature Verification Market report provides the requisite combination of strategic oversight and operational detail to support decisive action next year.
To access the full dataset, vendor scorecards, and download the deployable playbooks referenced here, visit the official report page. The granular segment tables and appendices — intentionally withheld from this summary to preserve the integrity of our exclusive analytical assets — are available in the full report.
For detailed analysis of this topic, please visit the official page: Worldwide Signature Verification Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Digital Printed Cartons Market Poised to Reach USD 7.85 Billion by 2032, Growing at a 15.63% CAGR
By pmarketresearch, 2026-07-15
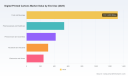
Worldwide Digital Printed Cartons Market — Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Worldwide Digital Printed Cartons Market report (base year 2025). This advisory brief highlights the macro dynamics, competitive implications, and near‑term strategic choices that senior executives, investors, and supply‑chain leaders must address in 2026. The full report contains the granular segmentations, proprietary scenario models, and deal‑level intelligence that underpin the recommendations below — intentionally withheld here to preserve the depth of our paid intelligence.
Worldwide Digital Printed Cartons Market
Market at a Glance: Rapid Growth, Strategic Inflection
The market for digitally printed folding cartons is entering a sustained growth phase. Our analysis shows the market was valued at USD 2,840.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 15.63% through the forecast horizon. By the end of the forecast period, the market is expected to be multiple billions in size, reflecting the accelerating adoption of digital print technologies across packaging converters and brand owners.
Worldwide Digital Printed Cartons Market
Two structural forces drive this trajectory: the economics of customization and the regulatory push toward recyclable, mono‑material constructions. The confluence of these forces is transforming both demand patterns (shorter runs, variable data, personalization) and supply economics (lower plate costs, reduced inventory obsolescence). For 2026, companies that align investment, commercial and sustainability strategies to these forces will capture disproportionate value.
Worldwide Digital Printed Cartons Market
Why This Report Matters for 2026 Decisions
-
Capital allocation under uncertainty — We provide scenario‑based investment cases for digital press adoption versus hybrid roll‑to‑sheet capacity, enabling CFOs to compare payback, utilization and margin outcomes under realistic throughput and substrate cost volatility assumptions.
-
Go‑to‑market playbooks — Brand teams and converters receive tactical frameworks for pricing personalization, structuring short‑run contracts, and integrating digital print capabilities into omnichannel packaging strategies.
-
M&A and partnership intelligence — Our M&A heatmaps and capability gap analysis indicate where acquisitive scale or technology partnerships will best accelerate market entry or extend geographic footprints.
-
Risk and resilience planning — The report models raw material sensitivity, regulatory risk (including emerging EPR schemes) and supply chain shocks to stress‑test sourcing strategies and long‑term contracts.
Report Contents — Practical, Actionable, Confidential
-
Executive summary and 3‑point strategic imperatives for corporate boards and private equity investors.
-
Market sizing and econometric forecast model (2026‑2032) with interactive scenarios to test pricing, substrate inflation and demand shocks.
-
Competitive landscape, including capability mapping, CR3/CR5 concentration analysis, and supplier scorecards for technology vendors and converters.
-
Technology adoption roadmap outlining when inkjet, electrophotographic and hybrid solutions are preferred relative to run length, print fidelity and substrate constraints.
-
Operational playbooks for converters: digital prepress, color management, inventory reduction tactics and labor skills transition plans.
-
Case studies and primary interviews with C‑suite executives, converters, and OEMs demonstrating real‑world outcomes.
Competitive Landscape: Who Matters and Why
The vendor and converter universe is a mix of global packaging champions and digitally native converters. Market concentration data points to a moderately consolidated market: the top three players account for a material share and the top five demonstrate nearly half of industry revenue, indicating scale matters for high‑volume converting and integrated retail contracts. This concentration creates both barriers and opportunities for nimble entrants.
-
Smurfit Westrock (Ireland / United States) — Leverages scale and integrated supply chains to offer short‑run digital cartons alongside traditional folding cartons and corrugated solutions. Their sustainability narrative and retail relationships make them a preferred partner for omnichannel consumer goods brands seeking rapid SKU rotations.
-
Graphic Packaging International (United States) — Strong in high‑volume converting with significant investments in digital printing capability for food and beverage applications. Their positioning benefits from deep relationships with high‑frequency CPG customers and high‑efficiency converting plants.
-
Mayr‑Melnhof Karton AG (MM Group) (Austria) — Premium cartonboard and print quality expertise positions them well for pharmaceutical, luxury and barrier‑sensitive food packaging — segments where print fidelity and material performance command a premium.
-
DS Smith Plc (United Kingdom) — Focuses on circular economy solutions and short‑run digital printing for e‑commerce and FMCG. Their strengths lie in sustainable material systems and retailer collaborations.
-
Amcor plc (Switzerland) — A global packaging incumbent offering hybrid approaches that blend digital printing with flexible and paperboard substrates for multi‑category customers, enabling cross‑portfolio sales synergies.
-
CCL Industries Inc. (Canada) and ePac Holdings (United States) — Both represent converters with strong digital print and label expertise, delivering high‑impact decorative and short‑run cartons for brands focused on rapid shelf turns and promotional activity.
-
THIMM Group, Stora Enso Oyj and Mondi Group — European specialists with complementary strengths in digital displays, renewable fiber materials and customized print solutions. Their integrated capabilities in fiber sourcing and converting are increasingly valuable as sustainability rules tighten.
Latest Industry Movements and Strategic Implications
-
Trade shows such as WEPACK 2026 demonstrated live production lines and accelerated OEM roadmaps toward faster, higher‑quality digital presses. For 2026, executives should plan evaluation pilots with OEMs showcased at these events to compress adoption timelines.
-
Converter case examples (e.g., transitions to Xeikon technology) highlight immediate benefits in production efficiency and quality. These real‑world deployments serve as templates for how to manage changeover costs and skill retraining.
-
Recent plant investments in Europe for pharma‑grade digitally printed folding cartons underline the sectoral pull for compliant, traceable, and low‑volume high‑mix production — a clear signal for focused capability investments for players targeting healthcare customers.
Material, Regulatory and Cost Dynamics
Three structural inputs will shape margins and strategy in 2026:
-
Raw material variability — Paperboard and recovered fiber markets remain subject to pricing volatility. Lightweighting trends reduce per‑unit material consumption, but converters must balance weight reduction against print surface requirements and barrier needs.
-
Regulatory pressure — Europe's Packaging and Packaging Waste Regulation and expanding EPR schemes (regionally accelerating in North America and parts of Asia) are pushing brands toward recyclable mono‑material designs. Digital printing’s plate‑less workflows support rapid SKU variation without the waste associated with traditional prepress, creating a strategic advantage for converters who master recyclable substrate solutions.
-
Operational shifts — Digital adoption reduces minimum economical run lengths and enables variable data. Procurement and commercial teams must revise costing models, SKU rationalization approaches, and inventory policies to capture full value.
Strategic Imperatives for 2026
-
Prioritize hybrid capacity investments where customer mix shows both high‑frequency short runs and selective long runs. Use our scenario model to calculate when inkjet or electrophotography purchases become accretive to margin versus outsourced digital conversion.
-
Embed sustainability as a business model: design for recyclability, document lifecycle benefits of digital workflows, and align with EPR reporting requirements to protect customer relationships and preclude regulatory penalties.
-
Develop commercial offers that monetize personalization — limited editions, localization, and serialized authenticity — with clear ROI metrics for customers based on conversion lift and reduced obsolescence.
-
Build strategic partnerships with OEMs and substrate suppliers to de‑risk supply and secure access to qualified recyclable boards optimized for digital inks and print processes.
-
Use M&A selectively to acquire capabilities (color management, prepress automation, last‑mile finishing) rather than scale alone — the marginal value of specialized digital expertise is high during this transition.
Next Steps — How PW Consulting Supports Your 2026 Playbook
PW Consulting’s full report delivers the models, competitive scorecards, and confidential appendices that boards and investment committees require to move from strategic intent to executable plans. We pair the syndicated forecast with bespoke advisory — from build vs. buy decision workshops to due‑diligence on target converters and implementation roadmaps for production and sales teams.
If your 2026 planning cycle includes capital allocation, channel reshaping or compliance upgrades in packaging, our report will materially shorten your decision timeline and reduce execution risk. For access to the complete data tables, interactive forecast model, and confidential competitive exhibits, please consult the PW Consulting report portal — the in‑depth intelligence is purposely gated to preserve the commercial value of the analysis.
PW Consulting — translating market motion into boardroom action for the digital carton era.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Printed Cartons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mechanical Anti‑Corrosion Lubricating Oil Market to Reach USD 3,250 Million in 2025, Projected to Grow at a 5.2% CAGR Through 2032
By pmarketresearch, 2026-07-15
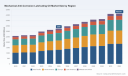
Worldwide Mechanical Anti-Corrosion Lubricating Oil Market — Strategic Imperatives for 2026 (PW Consulting Preview)
Executive summary
PW Consulting’s upcoming Worldwide Mechanical Anti-Corrosion Lubricating Oil Market report synthesizes five years of historic market behavior (2020–2025) and presents an actionable forecast across 2026–2032. The market has expanded from approximately USD 2,580 million in 2020 to an estimated USD 3,250 million in 2025, and is projected to grow at a steady compound annual growth rate of 5.2% over the forecast window. By 2032 the sector is expected to be materially larger than it was at the 2025 base, reflecting recovery in industrial demand, continued investment in corrosion protection across value chains, and the gradual adoption of next‑generation chemistries and services.
Worldwide Mechanical Anti-Corrosion Lubricating Oil Market
Why this preview matters for senior decision-makers in 2026
-
Timing and resource allocation: The market’s steady mid-single‑digit CAGR signals a transition from stabilization into selective expansion — an environment in which capital deployment should prioritize differentiated portfolios and resilient supply chains rather than broad capacity builds.
Worldwide Mechanical Anti-Corrosion Lubricating Oil Market -
Tactical pricing and procurement: Raw material trajectories that softened in late 2025 into early 2026 have created a window to reset procurement strategies and margin targets. Firms that lock favorable input costs into multi-tier contracts and couple them with dynamic pricing can capture immediate margin upside and strengthen customer retention.
Worldwide Mechanical Anti-Corrosion Lubricating Oil Market -
Innovation leverage: The intersection of sustainability expectations and equipment reliability requirements means product innovation (bio‑based blends, high‑performance synthetics, and advanced additive packages) will be a primary driver of premiumization — and of competitive advantage.
-
Consolidation and partnerships: With market concentration moderate (the top three suppliers account for a material share and the top five for a majority of the structured commercial market), 2026 is likely to see targeted M&A, co‑development and channel partnerships rather than broad, headline acquisitions.
Report practicalities — what PW Consulting delivers (selected)
-
Proven market-sizing and forecasts to 2032 with scenario and sensitivity models that let you test price, demand and raw material shocks against revenue and margin outcomes.
-
Supplier benchmarking and capability matrices that evaluate formulation technology, additive stacks, global supply footprint, aftermarket channels and service capabilities.
-
Commercial playbooks for OEM/aftermarket segmentation, go‑to‑market tactics, tender and contract design, and margin optimization across distribution tiers.
-
Procurement and raw material intelligence including drivers of base oil and additive cost cycles, inventory dynamics and risk mitigation strategies.
-
Regulatory and sustainability impact assessment covering biodegradability, VOC restrictions, end‑of‑life considerations and claims substantiation for green product lines.
-
Investment and M&A thesis suite: target screening, valuation sensitivities, and integration blueprints focused on bolt‑ons that accelerate specialty chemistry and channel reach.
Market dynamics that will define 2026 decisions
-
Input-cost volatility but an easing window: After elevated base‑oil cycles earlier in the period, market conditions softened into late 2025 and early 2026, driven by weaker lubricant demand in some end markets and replenished inventories. This has reduced immediate cost pressure for formulators but increases the importance of flexible procurement and hedging frameworks to guard against renewed spikes.
-
Premiumization vs. volume competition: Growth is concentrated in higher‑value synthetics and specialty additive‑intensive formulations that offer longer protection windows, multi‑mode corrosion inhibition, and compatibility with modern surface treatments. Price‑driven volume plays remain viable in mature channels but are increasingly margin‑constrained.
-
Sustainability and disclosure as commercial enablers: Customers and procurement teams are raising the bar for sustainability claims, life‑cycle evidence and supplier transparency. Companies that can combine performance with credible environmental credentials will unlock new procurement pools and justify premium pricing.
-
Service and digitalization: Lubrication is moving from a commodified product sale to a service bundle — condition‑based maintenance, inventory as a service, and data‑backed corrosion risk assessments become differentiators for B2B buyers seeking total cost of ownership reductions.
Competitive landscape — where incumbents and specialists are focusing
The competitive map blends global integrated oil majors, specialty lubricant manufacturers, additive houses and niche corrosion protection companies. Integrated energy firms bring scale in base oils and distribution; specialty players bring formulation expertise and customer intimacy; corrosion‑focused providers bring niche technologies for storage, transporation and OEM protection.
-
Integrated majors (e.g., ExxonMobil, Shell, TotalEnergies): Leverage global supply chains, extensive distribution networks and customer relationships in transportation and heavy industries. Their strategic play is broad coverage — from commodity anti‑rust fluids to higher‑value preventive lubricants — and bundling with other energy/product offerings to defend share.
-
Specialty formulators (e.g., FUCHS Group, Klüber Lubrication): Focus on R&D‑led, application‑specific chemistry and technical service. They excel in working with OEMs on spec development and in delivering performance guarantees that allow higher margin capture.
-
Additive and specialty chemistry providers (e.g., Afton Chemical, Lubrizol, DuPont/MOLYKOTE): Act as critical leverage points for formulators. Their ability to deliver advanced corrosion inhibitors and multifunctional additive packages determines product differentiation and speed to market for next‑generation blends.
-
Niche corrosion players (e.g., ZERUST/EXCOR, Cortec, Daubert): Dominate protection in asset storage, shipment and specific industrial use cases. Their focused value propositions around VpCI/VCI chemistries are attractive targets for partnerships or bolt‑on acquisitions by larger formulators seeking to broaden portfolio depth.
-
MRO and aftermarket brands (e.g., CRC Industries, WD‑40 Company, Jet‑Lube): Capture frequent small‑ticket purchases and brand‑led loyalty among maintenance teams. Their strength is reach and recognition within commercial maintenance workflows.
Actionable strategies for 2026
-
Prioritize product tiering and margin capture: Design a three‑tier portfolio (value, performance, premium‑sustainability) and align pricing to total cost of ownership messaging. For customers with critical uptime requirements, sell service bundles rather than liters.
-
Lock in flexible raw material arrangements: Move from fixed‑term purchase commitments to a blended mix of spot, indexed and hedged contracts. Short‑term base‑oil softness presents an opportunity to secure favorable terms for 2026 while building contingency clauses for upside risk.
-
Invest selectively in bio‑based and low‑VOC formulations: Accelerate qualification programs with strategic OEMs and tier‑1 distributors. Even if adoption ramps slowly, being first‑to‑market with certified solutions pays dividends in procurement cycles that prioritize sustainability.
-
Exploit distribution and aftermarket channels: Strengthen relationships with MRO distributors and inspection/maintenance service providers to convert product sales into recurring service contracts. Consider consignment models to reduce customer procurement friction.
-
Pursue targeted M&A and partnerships: Focus on bolt‑ons that add formulation IP, additive capabilities or niche corrosion protection technologies. Integration playbooks should prioritize rapid commercialization and cross‑sell into existing accounts.
-
Operationalize digital services: Pilot condition‑based lubrication programs and deploy simple IoT‑enabled monitoring for high‑value assets to prove service economics and reduce churn.
Risk matrix — what to watch in 2026
-
Raw material rebound: Although prices eased recently, a supply disruption or stronger-than‑expected rebound in automotive/industrial demand could re‑inflate costs and compress margins for low‑value segments.
-
Regulatory tightening: Emerging restrictions on certain solvents and additives could accelerate reformulation costs and create temporary supply bottlenecks for approved chemistries.
-
Channel disruption: Direct procurement strategies by large OEMs and maintenance integrators could squeeze traditional distributor margins — prompting the need for new commercial models.
-
Reputational risk: Unsupportable sustainability claims or failure to substantiate biodegradability can lead to lost contracts and brand damage; invest in third‑party testing and traceability.
How to use this preview and the full PW Consulting deliverable
This preview is intended to inform 2026 planning conversations — budget allocation, procurement cycles, portfolio roadmaps and M&A screening. The full PW Consulting report contains the granular segmentation, supplier scorecards, a downloadable price‑sensitivity model, and proprietary scenario outputs (including break‑even and NPV analyses for strategic investments). We intentionally withhold detailed regional/application splits and proprietary supplier scores in this public summary; the complete data set and executive slide pack are available through the report portal.
Closing: immediate next steps for executives
-
Run a rapid portfolio review against the three‑tier product framework and identify two SKUs to reposition as “service‑anchored” offerings in H1 2026.
-
Open a disciplined procurement window to capture the current easing in base materials, but include clauses to protect against upside volatility.
-
Engage with one specialty additive partner and one niche corrosion technology provider for joint pilots that can generate validated case studies by Q4 2026.
PW Consulting’s full Worldwide Mechanical Anti‑Corrosion Lubricating Oil Market report is the operational toolset for 2026 — combining validated market sizing, competitive intelligence, risk scenarios and go‑to‑market playbooks that translate market trends into executable actions. For the complete segmentation, supplier scorecards and downloadable models, please visit the report page.
For detailed analysis of this topic, please visit the official page: Worldwide Mechanical Anti-Corrosion Lubricating Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Sodium Ferrocyanide Market Set to Expand at 3.8% CAGR in 2026–2032 — Report
By pmarketresearch, 2026-07-15
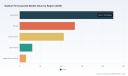
Worldwide Sodium Ferrocyanide Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting’s latest market study on the Worldwide Sodium Ferrocyanide market presents a focused, decision‑ready view for executive teams preparing plans and capital allocations in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the report places the market within a clear macro frame: the global market reached approximately USD 510.5 Million in the base year 2025, is projected to expand into 2026, and follows a compound annual growth rate (CAGR) of 3.8% through the forecast window—reaching a materially larger market by 2032. Market concentration is notable: the top three suppliers account for close to half of global capacity, while the top five collectively control well over sixty percent of the market. These structural characteristics, combined with evolving regulatory and upstream dynamics, create both predictable pathways and strategic inflection points for firms active in 2026.
Worldwide Sodium Ferrocyanide Market
Why this report matters for 2026
-
Timing: 2026 will be the first full planning year after several regulatory and product quality shifts reached market momentum in 2024–2025; companies that align sourcing, product development and commercial tactics now will capture the ensuing demand uptick.
Worldwide Sodium Ferrocyanide Market -
Clarity on supply concentration: with a market that exhibits mid‑to‑high concentration, procurement and strategy teams must understand supplier concentration risk and the levers suppliers can use to influence price, lead time and contractual terms.
Worldwide Sodium Ferrocyanide Market -
Regulatory inflection: recent authorisations and the persistence of existing food‑additive regimes materially alter addressable demand pools (notably feed and food applications), making regulatory surveillance a board‑level priority.
-
Actionability: the report is deliberately operational — beyond trends it delivers procurement playbooks, price scenario models, supplier scorecards and M&A lenses designed to support 2026 spend, sourcing and investment decisions.
What the report delivers (practical contents)
-
Executive dashboard with market size trajectory, growth drivers and downside risks calibrated to the 2026 planning cycle.
-
Supply chain and cost‑build analysis that traces inputs from upstream cyanide feedstocks through conversion routes, highlighting where margin is created and where cost shocks propagate.
-
Regulatory matrix covering food and feed authorisations, regional compliance regimes and the practical requirements for product registration and purchasing in regulated markets.
-
Commercial playbooks for procurement and sales: sourcing diversification strategies, contracting templates for long‑term supply, and channel approaches for industrial vs food‑grade buyers.
-
Competitive benchmarking: vendor scorecards comparing production capabilities, quality grades, geographic coverage, regulatory credentials and distribution reach.
-
Price and scenario models: three policy/market scenarios (baseline, accelerated regulation uptake, and supply‑constrained) with downloadable model files for user sensitivity testing.
-
M&A and partnership thesis: target screening criteria, integration risk checklists and valuation sensitivities for 2026 transactional activity.
-
Field‑tested recommendations for R&D and formulation teams to preserve product performance while reducing exposure to feedstock price swings.
Market dynamics shaping 2026 choices
Three broad dynamics will determine where value is created and lost in 2026: regulatory shifts, upstream feedstock volatility, and portfolio/route‑to‑market execution.
-
Regulatory shifts. In 2025 the European Commission issued a formal authorisation that re‑shaped feed market access, and longstanding food‑additive regimes remain in force with defined purity and use conditions. These outcomes expand and stabilise addressable demand in regulated markets but also raise the bar for supplier compliance documentation and traceability, which affects supplier selection and commercial lead times.
-
Upstream volatility. Sodium ferrocyanide’s industrial synthesis depends on upstream cyanide derivatives and iron salts; those upstream markets continue to show material price and regional cost differentials. Procurement strategies that fail to account for volatility or that over‑index on lowest initial cost may face margin erosion when feedstock surges occur.
-
Channel execution. End‑use markets — from anti‑caking applications to pigment production and metal finishing — have different service and purity requirements. Companies that match product grade and compliance posture to channel needs while maintaining flexible sourcing and safety stock will outperform peers on service levels and margin preservation.
Competitive landscape — who matters and why
The market features a mix of large integrated producers, regional specialists and global distributors. The top vendors combine scale, regulatory credentials and route‑to‑market capabilities:
-
Hebei Chengxin Co., Ltd. operates as one of the larger vertically integrated producers in China, offering strong cost position and volume capability. For buyers seeking scale and reliable bulk supply, suppliers with this profile remain foundational.
-
Shaanxi United Chemical Co., Ltd. has been moving to differentiate on grade and purity, with a recent product announcement underscoring availability of near‑99.7% high‑purity food‑grade material. This type of product positioning matters for food and feed formulators that must meet tight regulatory purity requirements.
-
Gentrochema BV and Evonik Industries AG offer complementary value propositions in Europe: REACH‑registered, in‑stock distribution and specialty regulatory support for food applications. European buyers that prioritise certification, lead times and regulatory documentation often prefer suppliers with these footprints.
-
Muby Chemicals , Hangzhou Keying Chem and regional distributors such as Wego Chemical Group play critical roles in serving niche industrial needs, export markets and the mid‑market, offering flexible lot sizes and distribution solutions that larger integrated players may not prioritise.
The concentration metrics in our study (top three suppliers approach half the market; top five well above sixty percent) signal that strategic supplier relationships, rather than spot purchasing, will be central to operational resilience in 2026.
Strategic implications and recommended 2026 actions
For corporate leaders building plans for 2026, the report yields the following actionable implications and recommended steps:
-
Procurement and supply chain: Move from transactional spot purchases to layered sourcing: combine a foundation of long‑term agreements with high‑credit suppliers, a secondary regional supplier for optionality, and a third channel distributor for agility. Insist on contract clauses that account for upstream feedstock pass‑through mechanisms and force majeure contingencies.
-
Regulatory and compliance: Treat feed and food authorisations as non‑negotiable gating criteria. Require full regulatory dossiers (REACH/EFSA/other applicable regimes) as part of bidder evaluation and include traceability SLAs in supplier contracts.
-
Commercial and product strategy: Reassess product segmentation: maintain premium lines for regulated food/feed customers, while optimizing industrial grades for cost efficiency. Invest in formulation flexibility to substitute grades or adjust dosing in response to price movements.
-
Risk management: Use the PW Consulting scenario models to stress‑test budgets against alternate price and supply outcomes; establish a hedging posture or fixed‑price procurements where volatility is most likely to impair margins.
-
M&A and partnerships: Evaluate targets that provide regulatory certification, geographic market access, or feedstock integration. Pay particular attention to assets that fill distribution gaps in regulated markets or that bring high‑purity production know‑how.
-
Operations and capex planning: Delay irreversible capacity expansion pending 12–18 month demand confirmation unless the investment secures feedstock access or regulatory compliance advantages that materially de‑risk the project.
How PW Consulting supports your 2026 planning
Our study is deliberately designed as a practical toolkit for 2026 decision‑makers. It contains a calibrated market model, supplier scorecards, regulatory gap analysis and downloadable scenario files that executives can incorporate into budgeting, procurement and M&A processes. To preserve competitive advantage, this press summary surfaces strategic signals and the types of tactical moves that matter — the full report contains the granular regional and application splits, historical price tables, raw material cost curves, and proprietary supplier ratings that organizations require to operationalise these recommendations.
Next steps
-
Download the full report to access: detailed regional and application demand breakdowns, price tables and our full supplier benchmarking matrix.
-
Engage PW Consulting for a tailored 2‑day workshop where we map your exposure, stress‑test your procurement strategy against our scenarios, and produce a bespoke playbook for 2026 execution.
PW Consulting’s analysis is based on primary supplier and buyer interviews, trade and regulatory databases, and a proprietary market model calibrated to the 2025 base year. For 2026 planners seeking a defensible, executable strategy in the sodium ferrocyanide ecosystem, the combination of macro clarity, supplier insight and tactical playbooks contained in the full study will materially shorten the path from insight to action.
For detailed analysis of this topic, please visit the official page: Worldwide Sodium Ferrocyanide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automatic Gearbox Valves Market Poised for 5.12% CAGR — New Market Insights Revealed
By pmarketresearch, 2026-07-15
Worldwide Automatic Gearbox Valves Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting’s latest market study, Worldwide Automatic Gearbox Valves Market, frames a rapidly evolving component segment at the intersection of powertrain electrification, regulatory pressure and precision hydraulic‑electronic control. This briefing summarizes the report’s strategic value for executives planning resource allocation, R&D roadmaps, go‑to‑market plays and M&A activity in 2026 — and explains why stakeholders should consult the full report to access the proprietary granular intelligence that underpins these recommendations.
Worldwide Automatic Gearbox Valves Market
High‑level market trajectory and what it means for 2026
From 2020 through our base year 2025, the global automatic gearbox valves market demonstrated steady expansion underpinned by stronger transmission electrification and tighter emissions/fuel‑economy regulation. Measured in USD (Millions), the market grew from the low‑to‑mid single‑digit billions in 2020 to an estimated market size in 2025 that anchors the near‑term planning horizon. PW Consulting projects a compound annual growth rate (CAGR) of 5.12% over the forecast window 2026–2032, with the market continuing to expand through 2032 driven by both conventional and electrified powertrain demand for more sophisticated valve control.
Worldwide Automatic Gearbox Valves Market
For corporate planning in 2026, this trajectory signals three immediate implications:
Worldwide Automatic Gearbox Valves Market
- Investment discipline: allocate R&D and capital expenditure toward valve technologies and control architectures that deliver measurable transmission efficiency and shift quality gains within a moderate growth environment.
- Prioritize modularity: design valve modules and valve body solutions that can be scaled across multiple transmission platforms (conventional multi‑speed AT, CVT, DCT and hybridized variants) to maximize return on tooling and validation investments.
- Supply chain resilience: prepare for episodic raw‑material volatility and downstream OEM warranty risk by diversifying sourcing and building contingency capacity in key geographies.
What the full report delivers — practical, decision‑ready content
PW Consulting’s report is structured to be directly actionable for commercial, product and corporate development teams. Key deliverables include:
- A concise market sizing model and scenario forecasts (base year 2025; forecast period 2026–2032) that allow rapid rerunning of company‑level scenarios against topline demand assumptions.
- Technology menu and roadmaps: comparative analysis of solenoid, pressure control and hydraulic valve approaches, including integration pathways with electronic control units and mechatronic valve bodies.
- Manufacturing and cost levers: guidance on lightweight valve‑body casting choices, coatings and tolerancing strategies that materially affect bill‑of‑material and assembly costs.
- Commercial playbook: OEM procurement sensitivities, pricing dynamics, and contract structures (tiered warranty, performance‑based rebates, localization milestones) tailored to automatic gearbox valves.
- A risk‑adjusted M&A and partnership framework: triage criteria for bolt‑on acquisitions, JV partners and technology licensing to accelerate time‑to‑market.
To preserve the strategic advantage for clients, this public summary deliberately omits granular split values and per‑region/appliance revenue breakdowns. The full dataset and interactive models are available through our subscription portal and include the segment‑level intelligence required for precise investment sizing and negotiation preparation.
Competitive landscape — what to watch in 2026
The competitive structure of the gearbox‑valves market is moderately concentrated, reflecting a mix of global Tier‑1s and specialized solenoid specialists. Market concentration metrics indicate that the three largest players account for a meaningful portion of supply, while the five largest firms together represent over sixty percent of industry revenue — a dynamic that shapes pricing power, technical barriers and OEM sourcing strategies.
Leading companies that will shape competitive dynamics in 2026 include established transmission systems and mechatronics suppliers as well as focused solenoid specialists. Select strategic profiles (non‑exhaustive):
- BorgWarner (Auburn Hills, Michigan, USA) — a leading Tier‑1 supplier with a strong portfolio of electro‑hydraulic solenoids and valve body assemblies targeting efficiency and shift quality across multi‑speed and hybridized powertrains.
- Aisin Corporation (Kariya, Aichi, Japan) — vertically integrated supplier producing transmissions and integrated gearbox valves with deep OEM relationships and precision hydraulic capability.
- ZF Friedrichshafen (Friedrichshafen, Germany) — emphasizes electronic‑hydraulic integration for passenger and commercial applications and competes on system performance and integration depth.
- Bosch GmbH (Gerlingen, Germany) — leverages a broad powertrain electronics portfolio to offer pressure and shift solenoids as part of integrated powertrain modules.
- TLX Technologies and HUSCO Automotive (Wisconsin, USA) — specialized solenoid and valve manufacturers that play a critical role as innovation partners and second‑source suppliers for OEMs and Tier‑1s.
- Magna Powertrain, Hitachi Astemo, Mitsubishi Electric, Parker Hannifin — each brings differentiated strengths in full powertrain systems, hydraulic control modules, mechatronics expertise and fluid control technologies.
Competitive dynamics in 2026 will be shaped by three tactical behaviors:
- OEM preference for suppliers that can demonstrate demonstrable lifecycle cost savings via improved shift calibration and reduced parasitic losses.
- Increased collaborations and selective vertical integration as OEMs seek suppliers who can co‑develop valve control logic and hardware tuned for hybrid and mild‑hybrid architectures.
- Greater emphasis on second‑source qualification and regional capacity as OEMs de‑risk supply chains after high‑profile reliability and recall incidents.
Recent industry signals — operational implications
Three recent developments crystallize where executives must act in 2026:
- Manufacturing expansions: HUSCO Automotive’s facility expansion announced in late 2024 signals rising demand for electro‑hydraulic solenoids for shift‑by‑wire and start‑stop systems. Strategic implication: OEMs and Tier‑1s should evaluate long‑lead capacity commitments and preferred supplier status to secure output.
- Quality and warranty risk: A major recall related to a transmission control valve defect underlines the cost and reputational impact of valve reliability issues. Strategic implication: invest in accelerated validation rigs, field‑failure analytics and design‑for‑serviceability to limit warranty exposure.
- Cross‑sector partnerships: Emerson’s 2025 partnership showcases transferability of advanced solenoid technologies from industrial to automotive contexts. Strategic implication: active scouting of adjacent‑industry innovations can deliver performance and emissions benefits faster than pure in‑house development.
Regulatory and materials context — risk and opportunity
Regulatory tightening in major markets — directed at fuel economy and emissions — is an accelerant for advanced gearbox valve adoption. Electronic control of hydraulic circuits enables nuanced shift strategies and lock‑up control that directly affect vehicle efficiency. Simultaneously, volatility in raw material prices for aluminum and specialty steels affects cost competitiveness for valve bodies and associated components.
- Regulation: anticipate continued pressure from US and EU rulemaking that will make valve‑level efficiency gains a procurement criterion for OEMs.
- Materials: factor in scenarios for aluminum and steel cost swings and assess alternative materials, coatings and process improvements (for example, thin‑wall castings and corrosion‑resistant spool finishes) to protect margins.
How to use this intelligence in 2026 — recommended actions
For commercial and technical leaders preparing budgets and strategic plans in 2026, PW Consulting recommends a five‑point action agenda:
- Fast‑track modular product families that support both conventional and hybrid transmissions, shortening time‑to‑qualification for OEM programs.
- Authorize targeted capacity investments and preferred‑supplier agreements in regions aligned with your OEM book of business to mitigate lead‑time and logistics risk.
- Embed reliability engineering and field‑data analytics into post‑production processes to reduce recall risk and strengthen pricing power via proven total cost of ownership advantages.
- Pursue selective partnerships with specialized solenoid innovators and adjacent‑industry technology owners to import rapid performance gains with limited capex.
- Scenario‑plan for material cost volatility with hedging, supplier contracts and design alternatives to preserve margin flexibility.
Why stakeholders should read the full report
This press release highlights the strategic contours of the automatic gearbox valves market, but intentionally withholds the granular regional and application splits that underpin tactical 2026 decisions. The full PW Consulting report provides:
- Interactive market models (base year 2025; 2026–2032 forecast) enabling bespoke sensitivity analysis for corporate planning.
- Detailed supplier benchmarking, procurement playbooks and price‑to‑performance matrices to inform contract negotiations.
- Proprietary failure‑mode insights and test protocols to reduce time‑to‑market and warranty exposure.
Executives who must commit budgets, structure supply agreements or evaluate M&A targets in 2026 will find the full dataset and supporting analysis indispensable. Contact PW Consulting to arrange a briefing and to access the models and annexes that translate high‑level trends into executable actions.
Methodology note
The analysis herein uses 2025 as the base year and projects out to 2032. Market sizing is expressed in USD (Million) and growth is reported on a compound annual growth rate (CAGR) basis. Competitive concentration metrics reported in this summary indicate a market where the top three and five suppliers represent material shares of demand — a structural feature that informs recommended negotiation and partnership strategies.
For access to the full report, proprietary tables, vendor scorecards and client‑tailored scenario runs, please reach out to PW Consulting. Our team stands ready to help you convert these industry dynamics into a prioritized 2026 action plan.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Gearbox Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Plant Activator Market valued at USD 1,450.5 Million in 2025 to climb to USD 2,296.1 Million by 2032 at a 6.78% CAGR — Asia Pacific, Salicylic Acid Derivatives and Fruits & Vegetables to drive growth
By pmarketresearch, 2026-07-15
Worldwide Plant Activator Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s new market study on the Worldwide Plant Activator Market positions senior executives and investment teams to make decisive, high‑conviction moves in 2026. Using a 2025 base year and a 2026–2032 forecast window, the analysis shows the market accelerating from roughly USD 1.45 billion in 2025 to about USD 2.30 billion by 2032, at a compound annual growth rate (CAGR) of 6.78%. This briefing explains the report’s practical value for corporate strategy, product development and M&A decisions — while intentionally leaving detailed segment tables and granular city/commodity splits behind a registration wall to protect the full analytical asset.
Worldwide Plant Activator Market
Why this report matters for 2026
-
Actionable forecasting: The market trajectory and scenario models translate macro momentum into quarter-by‑quarter revenue implications for product classes and channels, enabling CFOs and business unit leaders to model headcount, CAPEX and inventory plans against a credible baseline.
Worldwide Plant Activator Market -
Regulatory playbook: Biologicals and synthetic activators are being evaluated under shifting approvals and tolerance regimes. Our regulatory roadmaps convert recent policy changes into explicit go/no‑go milestones for clinical trials, registration timelines and launch sequencing across major markets.
Worldwide Plant Activator Market -
Commercial prioritization: We map go‑to‑market tactics — from field trial design to grower adoption pathways — and supply them with ROI calculators that show when a reallocated R&D dollar or a targeted subsidy program will convert to incremental topline.
-
M&A and alliance screening: The report provides an investment screen that flags accretive targets, integration risk factors, and the value levers (distribution, IP, fermentation capacity) that matter most when pricing transactions in 2026.
What’s inside — a practitioner’s dossier
-
Executive summary and market sizing: A concise synthesis of growth drivers, adoption curves, and the outlook to 2032, with sensitivity runs for high/low adoption and regulatory tailwinds.
-
Segment architecture (methodology and definitions): Clear operational definitions for plant activators, their modes of action (e.g., systemic acquired resistance vs. priming), and the taxonomy used across the report.
-
Forecast model and assumptions: An auditable financial model in spreadsheet form that supports user-led scenarios, enabling finance teams to test price/mix, penetration and yield effects on revenue and margin.
-
Regulatory and policy mapping: Country‑level timelines, risk matrices and checklists that turn recent regulatory shifts into tactical steps — including requirements that have surfaced in certain registrations and the practical implications of reduced approval timelines for qualifying biologicals in Europe.
-
Supply chain & technology briefings: Analysis of raw‑materials trends (microbial fermentation, natural extracts, precision fermentation), cost curves, CAPEX needs for production scale‑up and risk mitigation strategies for supply concentration.
-
Competitive and pipeline intelligence: Strategic profiles for leading vendors, technology owners and emergent challengers, plus a proprietary filter for assessing product readiness and differentiation.
-
Commercial playbooks and field protocols: Practical templates for field trials, grower engagement, distributor contracts, and ROI calculators that quantify the time‑to‑value of adoption programs.
-
M&A and partnership playbook: Due‑diligence checklists, integration scorecards and valuation sensitivities tailored to biological vs small‑molecule activators.
-
Data annex and primary interviews: Raw survey results, interview transcripts with growers and regulators, and a transparent methodology appendix supporting reproducibility.
Competitive landscape — what to watch in 2026
The industry sits between two dynamics: innovation-driven product differentiation (new small molecules and biological elicitors) and a commercial layer that is still consolidating around distribution and formulation capabilities. Leading firms bring distinct strategic playbooks:
-
Established agrochemical multinationals (example: Syngenta, BASF) — leverage formulation know‑how, global field trial networks and channel reach to scale systemic activators and integrated disease management solutions.
-
Biological specialists and mid‑sized players (example: Certis, Futureco Bioscience, Plant Health Care plc) — focus on microbial strains, fermentation platforms and regulatory dossiers that unlock low‑residue, sustainable claims for growers and brand owners.
-
Nutrition and biostimulant providers (example: NutriAg, Gowan, Valagro) — compete on crop resilience narratives and combine elicitation with nutrition to deliver yield protection under abiotic stress scenarios.
-
Regional innovators and small‑molecule entrants (example: Lier Chemical) — pursuing locally sourced IP and country‑specific registrations; these players can be rapid disruptors if they clear regulatory hurdles and prove field efficacy.
Our strategic profiles examine corporate R&D pipelines, formulation advantages, channel control, and where firms are likely to pursue bolt‑on acquisitions versus co‑development partnerships. We also surface near‑term catalysts — for example, product launches and field trial readouts — that will re‑rank competitive positioning in 2026.
Notable developments that reshape near‑term strategy
-
Product and pipeline movement: New small‑molecule entrants and biological launches in 2024–2025 are shortening time‑to‑adoption for certain crops. Teams should reweight launch portfolios to prioritise products that meet low‑residue and sustainability criteria demanded by retail and export markets.
-
Regulatory shifts: In the U.S., tolerance exemptions for certain microbial strains reduce commercial friction for biological activators. In Europe, streamlined approval pathways for qualifying biologicals can shave years off development-to-market timelines. Conversely, some jurisdictions’ registration review processes continue to require additional toxicology and field demonstration data — a practical timing and cost consideration for market entry.
-
Commercial validation: Recent field‑trial reports and peer‑reviewed evaluations are moving the industry from hypothesis to commercial evidence. Buyers and investment teams will prioritize products with robust, reproducible field efficacy across climatic ranges.
-
Supply innovation: The rise of precision fermentation and synthetic biology platforms is shifting the cost structure for biological inputs, creating arbitrage opportunities for companies that control fermentation capacity or proprietary strains.
How PW Consulting’s report informs specific 2026 choices
-
Portfolio optimization: Use the report’s ROI matrices to reallocate R&D spend toward formulations and claims that unlock the fastest route to revenue given local regulatory climates and subsidy programs.
-
Go‑to‑market sequencing: Our scenario engine helps prioritize country launches and channel investments where regulatory tailwinds and subsidy programs create the most favorable adoption economics.
-
Partnership vs. M&A decisions: The M&A playbook quantifies when an acquisition is superior to partner-based scale‑up, based on distribution control, IP exclusivity and fermentation capacity bottlenecks.
-
Field trial strategy: Templates and statistical designs included in the report reduce time to credible efficacy evidence and help minimize trial cost while maximizing regulatory and commercial signalling value.
-
Regulatory engineering: The report’s country roadmaps convert regulatory uncertainty into decision calendars — when to submit dossiers, when to expect data requests and where to pre‑position safety studies to avoid launch delays.
Market structure and risk profile — executive summary
The plant activator market is growing at a mid‑single digit CAGR and is characterized by a mix of multinational incumbents, biology‑first specialists and nimble regional players. Market concentration is modest: top players hold significant influence in certain channels, but there remains ample room for technology differentiation and regional consolidation. Key risks include regulatory reversals, formulation scale‑up failures and the pace of field efficacy validation. Countervailing upside includes accelerating adoption driven by grower economics, retailer sustainability requirements and supportive subsidy programs in several European markets.
Final note — the trailer approach
This briefing highlights the strategic dimensions and practical utility of PW Consulting’s full Worldwide Plant Activator Market report for 2026 decision cycles. To preserve the report’s investigative value we have intentionally withheld detailed segment tables, regional/application breakouts and company revenue splits from this public summary. The complete study includes full datasets, downloadable models, and interactive dashboards suitable for finance, R&D and commercial planning teams.
To obtain the full report, the downloadable forecast model, and tailored advisory options (market entry workshops, M&A diligence, or custom scenario builds), please visit the PW Consulting publication page or contact your account lead for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Plant Activator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Lobe Pumps Market to Reach USD 1,452.61 Million by 2032, Expanding at a 4.6% CAGR
By pmarketresearch, 2026-07-15
Worldwide Lobe Pumps Market — Strategic Outlook for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest Worldwide Lobe Pumps Market report (base year 2025) delivers a concise, action-oriented roadmap for executives planning capital allocation, product strategy, and supply-chain resilience in 2026. The lobe pumps market, measured in USD Million, recorded steady growth through the 2020–2025 historical window and is projected to continue expanding across the 2026–2032 forecast period at a 4.6% CAGR. Our baseline figures show a market size of USD 1,060.3 Million in 2025 with a model-driven trajectory to approximately USD 1,452.6 Million by 2032 — a growth profile that demands calibrated commercial responses rather than one-size-fits-all plays.
Worldwide Lobe Pumps Market
Why this report is strategically valuable in 2026
-
Timing: 2026 is the inflection year for many industrial end-users as investment cycles restart post-capex freeze periods. The report helps you prioritize projects that leverage predictable pump demand growth while minimizing exposure to cyclical tail risks.
Worldwide Lobe Pumps Market -
Decision focus: It is designed to inform board-level choices across three levers—product/portfolio roadmaps, channel and aftermarket strategies, and M&A / partnership scouting—using market scenarios that integrate material-cost dynamics and regulatory pressures.
Worldwide Lobe Pumps Market -
Practical orientation: Beyond high-level forecasts, the study supplies executable frameworks (total cost of ownership models, retrofit decision trees, and supplier scoring matrices) that translate market signals into procurement and engineering actions.
Market trajectory and what it means operationally
Historical data through 2025 demonstrate a resilient demand base, driven by hygienic processing requirements in food & beverage and pharmaceutical sectors, and by robustness needs in wastewater and industrial processing. Our forecast applies a 4.6% CAGR for 2026–2032, reflecting the combination of steady replacement cycles, incremental adoption of energy-efficient variants, and selective growth in specialty end-markets.
Operational implications for 2026 include:
-
Capacity planning: Suppliers with flexible manufacturing footprints can capture a disproportionate share of incremental demand as customers trade off lead time vs cost.
-
R&D prioritization: Investments in hygienic finishes, reduced pulsation designs, and energy efficiency will deliver near-term commercial payback in regulated end-markets.
-
Aftermarket focus: With market expansion driven partly by replacement and retrofit cycles, aftermarket parts, service contracts, and digital monitoring represent high-margin revenue streams for 2026.
Segmentation covered — and why detailed splits are intentionally held back
The report covers segmentation by region, pump type, and application, and delivers qualitative demand drivers for each bucket (e.g., sanitary requirements in food & pharma, solids-handling in wastewater). In keeping with the “trailer” principle of this release, we present directional insights and scenario outputs while intentionally withholding detailed line-item segment disclosures from this summary. This approach allows us to demonstrate analytical depth while guiding readers to the full dataset on our portal for the granular numbers and interactive dashboards essential for transaction-level diligence.
Competitive landscape — who to watch and what they signal
The lobe pumps market is moderately consolidated. Our CR3 sits at roughly 32.4% and CR5 at approximately 45.2%, indicating several global leaders alongside an active mid-market composed of specialist and regional manufacturers. Competitive dynamics to monitor in 2026:
-
Alfa Laval (Lund, Sweden): A clear leader in hygienic rotary lobe technology with dedicated product lines for ultra-clean biotech/pharma and broader hygienic applications. Their emphasis on gentle handling across a wide viscosity range signals continued strength in regulated markets where validation and cleanability matter.
-
SPX Flow — Waukesha Cherry-Burrell (Charlotte, NC, USA): Strong in sanitary, CIP-capable designs for dairy and beverage sectors, with platforms that manage higher pressure and temperature. Their installed-base reach makes them a critical partner for retrofit and service-led monetization.
-
Vogelsang (Essen [Oldenburg], Germany): Differentiates through elastomer-coated lobes and targeted designs for high-solid, abrasive streams. Recent product showcases and technical updates underscore a push into biogas/wastewater niches and serviceability enhancements focused on uptime.
-
Börger, NETZSCH, Viking (IDEX), Fristam, Ampco, GEA, and Bonve: These players collectively illustrate a spectrum from highly specialized hygienic offerings to rugged industrial variants. Their strategies span geographical expansion, modularization for serviceability, and selective premiumization for energy- and maintenance-sensitive accounts.
Recent industry moves worth noting
-
Vogelsang’s trade-show presence and product updates (including multi-tip lobe designs and housing InjectionSystem adaptations) indicate a focused push to reduce pulsation, extend maintenance intervals, and improve handling of debris-laden liquids—capabilities that resonate with wastewater and biogas operators seeking lower downtime.
-
Across the vendor landscape, product evolution is moving toward energy reduction (some modern lobe pump models report up to ~25% lower energy consumption), easier CIP/SIP compliance, and modularity for faster service turnarounds.
Macro and supply-side dynamics shaping 2026 choices
-
Raw materials: Stainless steel remains the core construction material for hygienic pumps. The broader stainless steel market and intermediate processed-material price movements are influencing lead times and input-cost volatility; procurement strategies should include hedging, multi-sourcing, and component standardization to preserve margins.
-
Inflationary pressures: Producer Price Index trends in early 2026 signaled month-to-month increases in processed goods relevant to pump manufacturing. Manufacturers and buyers need to negotiate transparent indexation clauses and consider longer-term supplier agreements to stabilize cost bases.
-
Regulation and standards: Ongoing tightening of hygienic and EHEDG-related standards is accelerating demand for validated designs in food, beverage, and pharmaceutical processing. Firms that can demonstrate compliance through documentation and hygienic design certification gain preference among procurement teams.
-
Energy and sustainability: Energy-efficiency improvements in pump designs are not just compliance-driven; they materially lower total cost of ownership. Expect large end-users to increasingly prioritize lifecycle efficiency as part of sustainability commitments.
What the report contains — practical deliverables
PW Consulting’s study goes beyond market sizing. Key deliverables include:
-
Scenario-based forecasts and sensitivity tables that translate material-cost and demand shocks into region- and application-level revenue outcomes (full numerical granularity available on the report portal).
-
Buyer-focused tools: TCO calculators, retrofit vs replace decision trees, and procurement negotiation playbooks for securing volume and aftermarket margins.
-
Supplier and M&A playbooks: Due-diligence checklists, technology fit matrices, and integration risk maps for acquiring or partnering with regional specialists.
-
Competitive profiles and capability heatmaps for the leading vendors and emerging challengers — showing where incumbents are vulnerable and where nimble specialists can win service-led share.
How to use the insights in 2026
-
For manufacturers: Prioritize modular designs and digital-ready sensors to capture aftermarket revenue while reducing service friction. Hedge raw-material exposure and review capital allocation for capacity flexibility.
-
For OEMs and integrators: Build preferred-supplier relationships with vendors that combine hygienic credentials with service responsiveness; leverage the report’s retrofit frameworks to upsell modernization programs.
-
For private equity and strategic investors: Use the market-concentration and scenario outputs to size bolt-on opportunities and estimate value-creation from consolidation, geographic expansion, or aftermarket platform roll-ups.
-
For end-users (F&B, pharma, wastewater): Apply the TCO models to procurement cycles to validate investments in energy-efficient equipment and to forecast maintenance spend over multi-year contracts.
Methodology and data confidence
The report synthesizes primary interviews, vendor-level product spec analysis, trade-show intelligence, and macroeconomic indicators. Forecasts are triangulated using bottom-up installed-base replacement cycles and top-down demand drivers adjusted for material-cost shocks and regulatory shifts. Where applicable, the study includes probabilistic ranges to reflect supply-chain and raw-material uncertainty.
Next steps — access the full intelligence
This release presents a condensed, strategic view intended to orient executive-level decisions for 2026. The full report contains the granular segment tables, regional dashboards, and interactive TCO tools that allow teams to operationalize the recommendations outlined here. For transaction diligence, supplier due-diligence packs, or to license our interactive forecast module, visit our report portal or contact PW Consulting’s industry desk to schedule a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Lobe Pumps Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Phenolic Antioxidant Market Hits USD 2,315.1 Million in 2025, Poised for Further Growth
By pmarketresearch, 2026-07-15
Worldwide Phenolic Antioxidant Market — Strategic Imperatives for 2026: PW Consulting Outlook
Executive teaser
Our new PW Consulting market brief on the Worldwide Phenolic Antioxidant Market frames the commercial and regulatory inflection points that procurement, R&D, corporate development and supply-chain leaders must act on in 2026. Anchored to a 2025 base year, the global phenolic antioxidant market sits at roughly USD 2.32 billion and is forecast to grow at a steady compound annual growth rate (CAGR) of 4.52% over the 2026–2032 horizon to surpass roughly USD 3.15 billion by 2032. That trajectory reflects a mix of demand resilience in plastics, lubricants and specialty applications, offset by margin pressure from upstream feedstock volatility and intensifying regulatory constraints.
Worldwide Phenolic Antioxidant Market
Why this report matters for 2026 decision-makers
-
Time-sensitive procurement planning: With feedstock and freight cost shocks persisting into 2026, buyers who recalibrate indexation clauses and hedging strategies can materially protect margins.
Worldwide Phenolic Antioxidant Market -
R&D and product roadmaps: Reformulation pressures from food-contact and consumer-article regulations are accelerating the move to low-migration and recycled-compatible antioxidant grades; R&D prioritization in 2026 will determine competitive differentiation in 2027–2029.
Worldwide Phenolic Antioxidant Market -
M&A and alliance strategy: Moderate market concentration means well-timed bolt-on acquisitions and specialty partnerships unlock scale and proprietary formulations without the multiples of a fully consolidated sector.
-
Supply-chain resilience: Tariffs, IMO-related bunker surcharge volatility and regional capacity changes require multi-pronged sourcing strategies—localization, dual sourcing, and contract terms designed to share cost shocks.
What the report delivers — practical, actionable intelligence
PW Consulting’s report is built to be directly operationalized by commercial, technical and strategy teams. Highlights of the toolkit included:
-
Forward-looking demand model (bottom‑up) built from 2020–2025 historical activity and run through scenario stress tests for 2026–2032.
-
Price and margin model that links raw-material cost feeds, notable historical price moves and freight/tariff vectors to producer economics.
-
Supplier scorecards with capability matrices (capacity, specialty grades, regulatory certifications, geographic footprint) and a three-tier competitive positioning framework.
-
Regulatory impact matrix with compliance pathways, recommended labelling and formulation guardrails for markets with tightening restrictions.
-
Commercial playbooks for buyers and sellers: negotiation anchors, contract clauses to manage pass-through, and commercialization levers for premium specialty grades (e.g., recycled-compatible antioxidants).
-
M&A and inorganic growth playbook: target profiles and valuation drivers for specialty-grade assets and regional manufacturing nodes.
As a deliberate part of the “trailer” approach, we present the macro outlook and strategic implications here while reserving segment-level tables, region-by-region demand breakdowns and per-application forecasts to the full report. These granular outputs are the core of the paid deliverable and are essential for executable planning.
Market dynamics shaping strategic choices in 2026
The phenolic antioxidant ecosystem in 2026 will be shaped by five interlocking dynamics:
-
Feedstock and price volatility. Upstream tightness in key intermediates pushed spot phenol and related feedstock prices materially in late 2024; producers responded with list-price increases in 2024 and carry-through effects remain in contracts and spot tenders. Procurement teams should expect continued episodic feedstock-driven price moves and structure contracts accordingly.
-
Regulatory tightening and formulation risk. Regulatory action has materially constrained certain legacy phenolic chemistries for consumer contact applications; some widely used antioxidants are limited in concentration in several jurisdictions, and food-contact ceilings for specific grades are enforced. Firms face a twofold task—maintain compliance while preserving performance in high-heat, high-shear polymer processing.
-
Shipment economics and trade friction. Freight surcharge regimes tied to IMO fuel rules and targeted tariffs on imports from specific origins raise landed cost variability. This dynamic favors regional supply solutions and increases the strategic value of localized or near‑market capacity.
-
Demand-side substitution and recycling. Growth in recycled-content polymers and tighter requirements for recyclate-compatible additives are creating demand for new antioxidant grades tailored to recycled streams. Suppliers with early commercialized recycled-compatible antioxidants will capture share in high-growth pockets.
-
Customer consolidation and formulation sophistication. End-markets (plastics compounders, lubricant formulators, rubber manufacturers) are consolidating formulation sourcing, raising the bar for supplier technical support, co‑development and integrated value propositions (e.g., masterbatches, ready-to-use additive packages).
Competitive landscape — who matters and why
The market is neither a tight oligopoly nor wholly fragmented: the top three players account for a meaningful minority share while the top five capture slightly more than half the market. That competitive structure encourages both scale-driven plays and local, specialty-focused strategies.
-
BASF SE (Ludwigshafen, Germany) : Global leader with a broad Irganox portfolio and strong technical services. The company’s recent value-based price actions illustrate ability to pass through feedstock inflation; strategic focus for BASF is sustained premium positioning in high-performance plastics and lubricant stabilization.
-
SI Group (Tarrytown, NY, USA) : Specialty player concentrating on polymer and rubber clients. Recent launches targeting recycled plastics signal a strategic pivot to growth pockets where technical differentiation commands pricing power.
-
Songwon Industrial (Ulsan, South Korea) : Competitive in commodity and semi‑specialty grades; recent capacity expansion demonstrates a play to secure share in polymer demand corridors in APAC and export markets.
-
Lanxess AG (Cologne, Germany) : Strong in lubricant and fuel additive segments with a compliance-centric stance; regulatory recertification efforts reinforce market access and customer confidence.
-
Regional and specialty players (Sumitomo Chemical, Kawaguchi Chemical, Everlight, Rianlon, Yasho, Double Bond, among others): These firms compete on localized service models, price, and specialized grades for PVC, rubber and regional compounders. Several are well positioned to capture demand growth in emerging markets where logistic and tariff barriers favor near-market supply.
Key recent moves underline how incumbents are responding: capacity expansions to capture polymer demand; new grades tailored for recycled-content plastics; price increases to offset feedstock hikes; and regulatory recertifications to preserve route-to-market. For buyers, the implication is clear—vendor selection must weigh scale and specialty capabilities plus contractual protections for pass-through and supply continuity.
Strategic recommendations for 2026
-
Reconfigure procurement to five-year total-cost-of-ownership (TCO) contracts that include indexation triggers, volume-flex clauses and explicit pass-through mechanics for feedstock and freight shocks.
-
Prioritize product redevelopment for low-migration and recycled-compatible antioxidant grades; allocate protected R&D spend with rapid prototyping and pilot-scale validation with key customers.
-
Pursue selective near-market capacity—either greenfield micro-units or toll-manufacturing partnerships—to mitigate tariff/freight exposure and reduce lead times for high-value formulations.
-
Embed regulatory monitoring into product governance: maintain a rolling compliance register for key jurisdictions and pre-certification investments where feasible.
-
Evaluate M&A targets that offer formulation IP, regional manufacturing, or access to specialty end‑markets; modest consolidation can be accretive given the market’s moderate concentration profile.
Methodology and transparency
Our forecast and strategic guidance are derived from a blended methodology: a bottom-up demand model covering 2020–2025 historicals, plant-level capacity mapping, primary interviews across producers, formulators and compounders, price-pass-through econometrics, and regulatory scenario analysis. Sensitivity testing for feedstock shocks, freight-cost scenarios and regulatory tightening underpins our recommended paths.
To preserve the “trailer” intent of this release, we have intentionally not disclosed the report’s segment-level breakouts, region-by-region demand splits or application-specific revenue tables here. These granular outputs—critical for procurement tendering, plant-capacity optimization and M&A valuation—are available in the full report package on our website.
Next steps
For corporate teams preparing budgets, R&D roadmaps, or M&A pipelines for 2026, the report provides direct-to-action guidance and downloadable templates (contract clauses, regulatory checklists, and a supplier-risk workbook). PW Consulting can also deliver an executive briefing tailored to your organization’s exposure across feedstock, geography and application to translate insights into an implementation plan.
Closing
Phenolic antioxidants will remain a foundational enabler across plastics, rubber, lubricants and food/feed stability. The market’s moderate growth and evolving risk landscape make 2026 a pivotal planning year: firms that combine disciplined procurement, regulatory-forward product development and selective capacity plays will convert steady market expansion into durable competitive advantage. PW Consulting’s full report contains the data, models and playbooks to support those decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Antioxidant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com