

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Construction Use Hydroxypropyl Starch Ether Market Poised to Expand at 5.24% CAGR Over 2026–2032
By pmarketresearch, 2026-07-15
Worldwide Construction Use Hydroxypropyl Starch Ether Market — Strategic Intelligence for 2026 Decision‑Makers
PW Consulting today releases an executive briefing drawn from our new market research: Worldwide Construction Use Hydroxypropyl Starch Ether (HPS) Market, base year 2025. Built on a historical series (2020–2025) and a forward-looking forecast window (2026–2032), the study quantifies the market’s trajectory and delivers an operational playbook designed to inform procurement, product development, and M&A decisions in 2026.
Worldwide Construction Use Hydroxypropyl Starch Ether Market
Headline takeaways
- The global HPS market expanded from USD 192.3 Million in 2020 to USD 248.6 Million in 2025 (base year), reflecting recovery and product penetration during the period.
- Under our central forecast, the market is projected to grow at a compound annual growth rate (CAGR) of 5.24% for the forecast period 2026–2032, reaching roughly USD 355.4 Million by 2032.
- Market concentration remains moderate: the top three suppliers account for 38.5% of the market, while the top five account for 52.4%, indicating room for strategic consolidation and value capture by focused players.
Why this report matters in 2026
- Strategic procurement: Raw material volatility and regional supply imbalances are reshaping supplier selection criteria. Our analysis helps procurement teams build defensible dual‑sourcing and hedging strategies.
- Product roadmap decisions: Manufacturers of dry‑mix mortars, tile adhesives and wall plasters can prioritize formulation upgrades and premium SKUs based on quantified market sizing and performance economics.
- M&A and inorganic growth: With mid‑level concentration and clear technical differentiation among vendors, 2026 remains an active window for bolt‑on acquisitions and capacity plays—our report highlights target archetypes and valuation levers.
What the report delivers — an operationally focused dossier
- Demand model by year (2020–2032) and scenario analysis that stress‑tests volume and price assumptions against construction cycles and commodity shocks.
- Supply mapping and competitive benchmarking across manufacturing scale, product variants, technical service capabilities and distribution reach.
- Raw material cost pass‑through models and sensitivity matrices to quantify margin exposure to propylene oxide and feedstock fluctuations.
- Commercial playbooks: procurement checklists, go‑to‑market approaches for formulators, and an M&A playbook with integration risk checklists.
- Regulatory and sustainability landscape affecting starch sourcing, product labelling and safe‑use guidelines in key construction jurisdictions.
Market dynamics shaping decisions in 2026
Three dynamics dominate near‑term strategy for HPS stakeholders: demand composition driven by construction activity and dry‑mix adoption; raw material cost volatility; and product innovation that changes formulate economics.
Worldwide Construction Use Hydroxypropyl Starch Ether Market
- Construction demand & product mix: Growth in repair, renovation, and urbanization underpins steady demand for dry mortars that rely on HPS for water retention, rheology control and anti‑sag performance. Our demand model reflects both cyclical and structural levers—beneath the headline CAGR, there are application‑level pulses that inform SKU prioritization.
- Raw material volatility: The etherification process for HPS is sensitive to propylene oxide availability and price. Market references show Northeast Asia spot levels at approximately USD 1.14/kg in December 2025. By February 2026, reported levels stood at roughly USD 1,138/MT in China and USD 1,236/MT in the USA. Chinese domestic benchmark prices spiked in March 2026—one report cited 11,466.67 RMB/ton with a rapid month‑on‑month increase of over 40%—illustrating how feedstock tightness can compress margins or force price repricing downstream.
- Innovation & substitution pressure: HPS is often applied in combination with cellulose ethers and other additives. Innovations in starch modification, new grade introductions and blends with cellulose derivatives are changing performance profiles and unit economics. The report maps which product attributes command premium pricing and why technical service (on‑site trials, dosing guidance) is increasingly a differentiator.
Competitive landscape — synthesis and implications
Our competitive review profiles a diversified set of suppliers with differing strategic postures: specialist starch‑ether producers, integrated chemical players, and high‑service partners focused on building materials. While many leading vendors are regionally focused manufacturers with deep formulation expertise for cement and gypsum systems, trends point to a bifurcation between scale players chasing cost leadership and nimble specialists capturing premium niches.
Worldwide Construction Use Hydroxypropyl Starch Ether Market
- Scale and specialization: Established manufacturers offer broad HPS portfolios tailored to tile adhesives, wall putty and dry mortars, often pairing HPS with cellulose ethers to optimize rheology and workability. These firms leverage technical service and local distribution to defend customer relationships.
- Technical differentiation: Several firms emphasize product attributes such as water retention, sag resistance and compatibility with polymer modifiers. This technical nuance is where smaller suppliers can protect margin against price competition from larger producers.
- Consolidation potential: With the top five controlling just over half of the market, strategic acquisitions—targeting either capacity or application expertise—are likely to accelerate as companies seek to unlock scale benefits and broaden portfolios.
- Supply chain risk: Many manufacturers are exposed to upstream propylene oxide swings and regional feedstock constraints. Companies with forward integration, alternative etherification routes, or secured feedstock contracts will enjoy a competitive edge in 2026.
Practical implications for 2026 strategy
Across our client work, the following priorities emerge as highest impact for the coming 12–18 months:
- For manufacturers: Implement dynamic pricing clauses linked to propylene oxide indices, accelerate development of high‑value grades, and build technical support offerings that tie product performance to reduced installation cost for end customers.
- For raw material suppliers: Offer transparent indexation solutions and secure-offtake partnerships with HPS producers. Investments in feedstock diversification and capacity flexibility reduce downstream disruption risk.
- For mortar formulators and OEMs: Reassess formulations to balance material cost with installation labor savings—especially where HPS enables thinner bed technologies or faster set profiles that reduce total cost of ownership.
- For private equity and strategic investors: Target specialist HPS players with strong formulation IP, or regional players with potential for bolt‑on expansion to achieve scale and margin improvement.
Operational playbook included in the full report
We designed the deliverable to be actionable. Highlights of the operational toolkit included with the full report:
- Price sensitivity dashboards that quantify EBITDA impact across plausible propylene oxide scenarios.
- Supplier due‑diligence templates (quality, regulatory compliance, capacity, logistics resilience).
- Go‑to‑market blueprints for launching premium HPS grades—covering sampling programs, co‑development agreements and ROI cases for formulators.
- M&A screening matrix with synergy levers, integration risk factors and valuation range heuristics tailored to HPS targets.
How to use this intelligence
This briefing is a strategic preview designed to inform 2026 planning cycles. It surfaces the macro trajectory, competitive posture and tactical levers that matter—while preserving the granular segmentation, application‑level volumes and company‑by‑company data for the full report. For procurement teams, R&D leads, commercial directors and investment committees, the full dataset provides the calibrated inputs necessary to finalize budgets, supplier contracts and acquisition target lists.
To access the complete research package—containing the full demand model, application and regional breakdowns, individual company profiles and downloadable spreadsheets—please visit the PW Consulting report page or contact your PW Consulting account director for a secure data preview and tailored advisory engagement.
Closing perspective
HPS sits at the intersection of commodity dynamics and technical differentiation. The next 18 months will reward companies that marry disciplined feedstock risk management with targeted product innovation and a service‑led commercial approach. PW Consulting’s Worldwide Construction Use Hydroxypropyl Starch Ether Market report is built to be an operational tool for those decisions—delivering numbers, scenarios and pragmatic playbooks that translate insight into action.
For detailed analysis of this topic, please visit the official page: Worldwide Construction Use Hydroxypropyl Starch Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Ionic Hydroxypropyl Starch Ether Market to Reach USD 249.77 Million by 2032 at a 5.58% CAGR, Asia‑Pacific Leading with USD 76.42M (Base Year 2025)
By pmarketresearch, 2026-07-15
Worldwide Ionic Hydroxypropyl Starch Ether Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market study on the Worldwide Ionic Hydroxypropyl Starch Ether market delivers a focused, decision-oriented perspective designed for executives making resource allocation, commercial and M&A decisions in 2026. Anchored on a 2025 base year and a multi-year forecast to 2032, the report combines quantitative market sizing with deployable playbooks for procurement, product strategy, and competitive positioning. This release highlights the report’s practical value while preserving the granular intelligence available only in the full study.
Worldwide Ionic Hydroxypropyl Starch Ether Market
Market at a glance: growth trajectory and concentration
After recovering steadily through the early 2020s, the ionic hydroxypropyl starch ether market reached a material scale in the 2025 base year (reported in USD Million), supported by structural demand across construction additives, paper/textile sizing, adhesives and select food/pharma niches. Our baseline forecast carries the market forward with a compound annual growth rate (CAGR) of 5.58% across the 2026–2032 horizon, reflecting a combination of moderate volume expansion and selective price movement driven by input-cost dynamics and formulation shifts.
Worldwide Ionic Hydroxypropyl Starch Ether Market
Market concentration is moderate: the largest three producers account for a meaningful but non-dominant share of industry revenue, and the top five increase that concentration further — a landscape that enables both scale advantages for incumbent processors and opportunity for agile specialists and regional suppliers to carve out differentiated positions.
Worldwide Ionic Hydroxypropyl Starch Ether Market
Why 2026 is an inflection point for corporate strategy
- Raw-material sensitivity will determine margin outcomes. Production of hydroxypropyl starch ethers is rooted in agricultural starch feedstocks (corn, potato, tapioca) and an etherification chemistry that is inherently exposed to grain market swings and energy/freight cost volatility. Firms that align procurement, contract structure and hedging to these realities will protect margins and preserve competitive pricing flexibility.
- Formulation synergies and product bundling matter more. Demand drivers in key downstream sectors—particularly dry-mix mortars and paper/textile sizing—favor suppliers who can demonstrate performance improvements when starch ethers are paired with cellulose ethers and other rheology modifiers. 2026 will see buyers favor solution providers over commodity suppliers.
- Sustainability and traceability are becoming commercial gates. Buyers in Europe and other premium markets increasingly require supply-chain transparency and sustainability attributes tied to starch sources and manufacturing energy footprints. Suppliers able to certify feedstock origin and reduce lifecycle emissions will access premium channels.
- Supply chain resilience equals commercial continuity. Geographic dispersion of feedstock production and processing capacity—combined with shipping and energy cost uncertainty—requires playbooks for multi-sourcing, strategic safety stocks, and nearshoring where possible.
Actionable insights for 2026 planning
- Revise procurement to a hybrid-sourcing model. Adopt an approach that blends long-term offtake contracts for staple volumes with call-off arrangements or spot purchasing for opportunistic coverage. Embed indexation clauses tied to validated raw-material price indices and incorporate service-level KPIs linked to delivery reliability.
- Prioritize product co-development with leading mortar and paper formulators. Invest in joint development programs that demonstrate measurable performance benefits (workability, open time, sag resistance) when combining ionic starch ethers with cellulose ethers—these become powerful commercial differentiators in tenders.
- Operationalize a feedstock risk dashboard. Build a dashboard that tracks crop yields, regional freight rates, energy prices and quality premiums for targeted starch types. Use scenario triggers to shift procurement posture and production scheduling.
- Accelerate sustainability initiatives that customers can verify. Pursue certification pathways and supplier traceability systems for starch origin, and quantify the carbon and water footprint of production routes. Packaging and logistics improvements that reduce total delivered cost are high-return, low-complexity interventions.
- Targeted capacity plays, not broadscale scale‑up. Given the market’s moderate concentration and steady CAGR, selective capacity expansions focused on high-value grades, regional supply gaps or co-located formulation labs deliver better returns than undifferentiated volume growth investments.
Competitive landscape: strategic profiles and implications
The market is composed of starch-specialist processors, diversified starch/ingredients groups and focused cellulose-ether players that have broadened into starch ethers. Each cluster brings different advantages and constraints for prospective partners or acquirers:
- Integrated starch processors (examples include firms with large agricultural processing footprints). These players benefit from feedstock security and scale in derivative production. Their strategic advantage lies in upstream integration and the ability to optimize raw-material flows. Potential concerns include exposure to agricultural cycles and limited agility for rapid product customization.
- Specialist hydroxypropyl starch ether producers concentrated in Asia. These suppliers typically offer cost-competitive grades and close relationships with local dry-mortar OEMs. Opportunities exist for Western formulators to secure competitive supply, while risks hinge on logistics volatility and evolving regulatory expectations in higher-margin markets.
- European starch-derivative groups and branded suppliers. Companies with broad starch-ether portfolios emphasize product quality, sustainability credentials, and technical support. They are well-positioned for premium channels and co-development agreements but carry higher cost bases relative to certain regional producers.
- Collaborative and JV structures. The market shows a growing pattern of joint ventures and manufacturing partnerships—especially where local regulatory or logistics factors create entry barriers. Such structures are an efficient route to secure regional presence without full-capex commitment.
For commercial planners, the implication is clear: prioritize supplier relationships that combine technical support, traceable feedstock, and flexible manufacturing footprints. For corporate development teams, look for bolt-on acquisitions that add technical grades, regional supply capability, or differentiated sustainability attributes rather than large-scale volume plays alone.
Report contents: what the full study delivers to executives and functional leaders
PW Consulting’s full report goes beyond high-level narrative. The deliverables are organized to be directly actionable for procurement, R&D, business development and corporate strategy teams:
- Quantified historical market sizing (2020–2025) and a detailed 2026–2032 forecast built on bottom-up and top-down triangulation, presented in USD Million.
- Demand-by-application and regional demand modelling (methodology and drivers disclosed; granular split tables reserved for subscribers).
- Cost build-up models for typical starch ether grades, showing sensitivity to feedstock, energy and freight—plus scenario analysis to quantify margin impact under stress cases.
- Competitive benchmarking and company profiles for leading manufacturers, with strategic positioning maps and acquisition target shortlists.
- Procurement playbooks, supplier scorecards, and negotiation levers that buyers can implement immediately.
- Product-development roadmaps and formulation case studies that compare performance trade-offs in construction and paper/textile applications.
- Regulatory and sustainability matrices highlighting certification routes and key compliance milestones across major markets.
- M&A and partnership playbooks, including multiples guidance, integration risks and due-diligence checklists tailored to starch-derivative assets.
How executives should use this intelligence in 2026
- Board-level planning: Use the CAGR baseline and concentration indicators to stress-test organic growth targets and capital allocation plans for 3–5 year horizons.
- Procurement teams: Implement the hybrid-sourcing model and the feedstock risk dashboard to stabilize cost of goods sold and reduce supplier interruption risk.
- R&D and product managers: Prioritize formulations that unlock premium pricing through improved performance and sustainability claims—leverage co‑development frameworks contained in the full report.
- M&A & BD teams: Focus on tuck-ins that provide regional scale, technical grades or sustainability credentials rather than headline-volume plays.
PW Consulting’s study is intentionally structured as a decision tool: it provides the numbers you need to justify investment and the operational playbooks you need to execute. This executive preview demonstrates the kind of insights contained in the full report while preserving the detailed segment-level intelligence that subscribers rely upon for transaction-level decisions.
Next steps and access
For a complete view of segmentation, company-level benchmarking, downloadable models in USD Million, and the full slate of procurement and M&A templates, access the full Worldwide Ionic Hydroxypropyl Starch Ether Market report on the PW Consulting website. The full study includes the primary-data appendices, methodological notes, and proprietary scenario models that underpin the strategic recommendations summarized here.
PW Consulting remains available to run tailored workshops for executive teams and to apply the report’s models to bespoke scenarios—contact our strategy practice to arrange a briefing and implementation roadmap.
For detailed analysis of this topic, please visit the official page: Worldwide Ionic Hydroxypropyl Starch Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Tunnel Detection System Market to Expand at 8.04% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Tunnel Detection System Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases a forward-looking industry briefing derived from our full market research report on the Worldwide Tunnel Detection System market. As security threats evolve and infrastructure protection becomes mission-critical, this briefing highlights the strategic implications that enterprise leaders, procurement officers, and defense & homeland-security program managers must consider in 2026. It showcases the research depth behind our findings while deliberately reserving segment-level tabulations and proprietary modeling—available in the full report—to encourage direct engagement with our sources.
Worldwide Tunnel Detection System Market
Market Trajectory at a Glance
The tunnel detection market has entered a sustained expansion phase. Our topline model shows growth from USD 1,980.4 Million in 2020 to USD 2,840.5 Million in the report’s base year (2025). We project an immediate uplift to approximately USD 3,152.4 Million in 2026 and a continued climb to USD 4,868.12 Million by 2032, underpinned by a compound annual growth rate (CAGR) of 8.04% across the forecast period. These macro dynamics reflect a confluence of policy funding, technology maturation, and escalating operational requirements in border, critical infrastructure and asset protection contexts.
Worldwide Tunnel Detection System Market
Why This Matters for 2026 Strategy
- Capital planning and procurement timing: The step-change between 2025 and 2026 indicated in our model signals an inflection point for procurement cycles. Organizations planning major rollouts or CapEx commitments in 2026 should align tender schedules to capture early-adopter advantages while accounting for vendor delivery lead times.
- Technology portfolio choices: Detection architectures are diversifying (surface-based sensors, buried seismic arrays, fiber-based sensing, and ground-penetrating radar among others). Selection decisions should be driven by mission profile, false-alarm tolerance, coverage cadence, and integration with existing VMS and command centers. Our full report provides a decision matrix to map operational requirements to technology families and performance trade-offs.
- Supply chain and component risk: Core components—specialized geophones, accelerometers, fiber-optic sensing elements, and high-fidelity acoustic sensors—are subject to lead-time and qualification constraints. Buyers must incorporate component sourcing clauses and dual-sourcing strategies into contracts to mitigate delivery and lifecycle risks.
- Regulatory and funding tailwinds: Recent public allocations directed toward persistent surveillance and cross-border detection capabilities are accelerating adoption. Programs which can align their proposals with public funding priorities will materially improve project economics and accelerate deployment timelines.
Report Deliverables: Practical Tools for Executives
Our full report is structured to be a practical playbook, not just an academic exercise. Key operational deliverables include:
Worldwide Tunnel Detection System Market
- Deployment playbooks for pilot, phased, and enterprise-scale rollouts, with checklists for site engineering, environmental testing, and systems integration;
- Procurement templates and ROI calculators that quantify total cost of ownership, expected detection coverage, and lifecycle maintenance for competing architectures;
- A vendor evaluation framework that scores suppliers across performance metrics, verification protocols, integration effort, and sustainment footprint;
- Scenario-based decision guides for border security, transport tunnels, and critical infrastructure protections—including tailored rules of engagement and escalation ladders;
- Regulatory watch and funding tracker to identify short- and medium-term grant windows, program priorities, and compliance obligations;
- Structured scorecards and negotiation playbooks for risk-sharing contracts and performance-based service agreements.
Competitive Landscape: Capabilities, Differentiation, and Tactical Moves
The tunnel detection ecosystem blends defense primes, specialized sensor companies, and scientific instrumentation vendors. Market concentration is moderate: the top three firms account for roughly 32.4% of market revenues, while the top five together approach approximately 48.8%. That mix fosters both competition and opportunity for partnerships, integrations, and targeted consolidation.
- SensoGuard Seismic Solutions (Israel) — SensoGuard’s product set focuses on buried seismic arrays and wireless solutions marketed for perimeter and correctional environments, emphasizing AI-enabled classification to reduce false positives and seamless VMS integration. Recent catalog updates in April 2026 demonstrate a move to productize AI-assisted verification modules aimed at faster field adoption.
- Geospace Technologies (United States) — Geospace offers multi-sensor SADAR systems combining seismic and acoustic arrays for 3D localization of subterranean activity. Their strengths lie in dense sensor networks and real-time localization algorithms suited for complex terrains; they are frequently chosen where high-resolution spatial localization is required.
- Elbit Systems (Israel) — With a portfolio that blends acoustic, vibration and AI analytics, Elbit has leveraged its homeland and defense track record to scale to larger perimeter and border surveillance programs. Notably, Elbit’s American subsidiary executed further deployments in late 2025, reinforcing their position in government procurement channels.
- US Radar Inc. (United States) — US Radar brings deep specialization in ground-penetrating radar (GPR), with capabilities extending to deep-penetration imaging. Their systems are often selected for geophysical surveys and scenarios where subsurface characterization and imaging fidelity are prioritized.
- Lockheed Martin (United States) — As an integrator and systems house, Lockheed combines gravity gradiometry, GPR, and advanced signal-processing to support large-scale defense programs and airborne/surface-based surveying. Their historical program experience and scale give them an advantage in enterprise-level, government-funded contracts.
Each of these players addresses different risk profiles and operational needs: some prioritize low false-alarm rates and ease of VMS integration, while others target raw detection depth or enterprise program scale. The competitive dynamic favors vendors that combine sensor reliability, algorithmic transparency, and integration partners for command-and-control systems.
Industry Signals, Policy Drivers and Component Considerations
- Policy and funding: Public funding commitments aimed at persistent surveillance and tunnel detection are material. For example, a 2025 allocation focused on expanding ground-penetrating radar and acoustic sensor deployments has catalyzed program-level procurements and accelerated pilot-to-program transitions.
- Component constraints: Performance of seismic and acoustic solutions rests on a small set of specialized hardware—geophones, accelerometers, fiber-optic sensing elements, and precision ADCs. These items have long qualification cycles; procurement strategies must therefore address supplier qualification and lifecycle obsolescence.
- Operational noise and discrimination: The core technical challenge remains distinguishing covert tunneling from benign surface and subsurface noise (construction activity, natural seismicity, and heavy traffic). Advances in AI-assisted verification and multi-modal sensor fusion are improving discrimination, but algorithm explainability and field validation remain requirements for mission-critical acceptance.
Practical Recommendations for 2026 Executives
- Adopt phased risk-reduction pilots: Run small-scale, instrumented pilots to calibrate algorithm thresholds and integration with command ecosystems before committing to rollouts. Use pilots to validate detection-to-action timelines.
- Prioritize interoperability: Specify open integration interfaces (APIs, standardized alerts, and map overlays) in RFPs to avoid vendor lock-in and ease future capability layering (e.g., LIDAR, aerial ISR).
- Lock in critical components: Secure long-lead items via framework agreements and include test/acceptance criteria tied to environmental performance and false-alarm metrics.
- Incentivize sustainment: Favor procurement models that include performance-based maintenance and health monitoring—this reduces lifecycle cost and keeps system sensitivity calibrated over time.
- Consider strategic partnerships: Defense primes and sensor specialists each bring complementary strengths; evaluate JVs or teaming agreements where scale and rapid fielding are priorities.
How PW Consulting’s Full Report Supports Your 2026 Decisions
Our complete Worldwide Tunnel Detection System Market report supplies the actionable, data-driven materials needed to execute the recommendations above: granular supplier scorecards, procurement templates, risk-adjusted financial models, and validated deployment timelines. It also contains the full segmentation tables, regional and application breakdowns, and detailed forecasts underpinning our topline numbers. In this briefing we intentionally omit those segment-level figures to preserve the utility of the full dataset and to direct decision-makers to the source material that will enable contract-level planning.
For organizations preparing for procurement cycles, technology refreshes, or policy-aligned funding opportunities in 2026, the full report functions as both an evidence base and an operational playbook. If your program requires bespoke scenario analysis, PW Consulting also offers tailored workshops and modeling support to convert market insights into procurement-ready strategies.
Next Steps
- Download the executive summary and schedule a briefing with PW Consulting to review the complete segment-level forecasts and supplier matrices.
- Request a tailored workshop to map your operational requirements against vendor capabilities and to develop a defensible procurement timeline for 2026.
- Engage with our analysts for a confidential supplier risk assessment or an ROI validation for planned investments.
PW Consulting’s research provides the strategic context and tactical instruments organizations need to navigate an increasingly complex tunnel detection market. Our topline projections—from USD 1,980.4 Million in 2020 to a projected USD 4,868.12 Million by 2032 at an 8.04% CAGR—are the basis for practical, actionable plans that reduce deployment risk and accelerate time-to-effectiveness. Access the full report to unlock the detailed segmentation, vendor datasets, and procurement tools that will guide your 2026 decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Tunnel Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Advanced Cancer Pain Management Market Poised to Expand at a 6.55% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Advanced Cancer Pain Management Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s new market intelligence brief, Worldwide Advanced Cancer Pain Management Market (base year 2025; historical coverage 2020–2025; forecast 2026–2032), synthesizes clinical innovation, regulatory shifts, reimbursement reforms, and competitive positioning into a single, actionable narrative designed for boards, corporate strategy teams, and investors preparing 2026 priorities. Our forecast models project the market to expand from an estimated USD 8,424.42 million in 2025 to USD 13,134.49 million by 2032, representing a compounded annual growth rate (CAGR) of 6.55% over the 2026–2032 period. These topline dynamics underpin four strategic imperatives companies must address heading into 2026.
Worldwide Advanced Cancer Pain Management Market
Why this report matters for 2026 strategic choices
-
Timing and portfolio prioritization — With accelerating non-opioid therapeutic development and targeted interventional technologies, 2026 is a pivot year for reallocating R&D and commercialization budgets toward differentiated modalities that capture durable, reimbursable value.
Worldwide Advanced Cancer Pain Management Market -
Regulatory and reimbursement arbitrage — New regulatory guidance and reimbursement pathways are reshaping product economics; understanding the interplay between these forces is essential to set realistic go-to-market timelines and pricing strategies.
Worldwide Advanced Cancer Pain Management Market -
M&A and partnership rhythm — Moderate market concentration combined with rapid clinical innovation creates recurring windows for bolt-on acquisitions and strategic collaborations; being positioned as a credible partner or buyer in 2026 will materially change growth trajectories through 2032.
Topline market trajectory (high-level)
PW Consulting’s topline model characterizes a steady expansion in aggregate demand across therapeutic and interventional approaches. After a historically observed rise from USD 7,420.5 million (2023) to USD 8,424.42 million (2025), our forecast anticipates continued growth to USD 8,976.22 million in 2026 and a horizon value of USD 13,134.49 million by 2032. This trajectory reflects sustained clinical need, improving access to supportive care, and cross-cutting policy shifts that influence both opioid and non-opioid treatment adoption.
Market structure and competitive posture
The market shows a concentrated competitive structure: the top three firms account for a material portion of market sales, with the top five expanding that share further. This concentration creates both barriers and opportunities: established biopharma and device players retain strong commercial channels and payer relationships, while specialist innovators are carving out high-margin niches through differentiated mechanisms of action and interventional platforms.
-
Incumbent biopharma — Large pharmaceutical companies continue to dominate established opioid portfolios and branded analgesics. Their strengths include deep payer engagement, global distribution, and scale in clinical development that can be leveraged for adjunctive or supportive indications.
-
Specialist innovators — Small to mid-sized developers and device companies are advancing targeted interventional solutions and non-opioid pharmacotherapies. Their value lies in clinical differentiation and, increasingly, in new reimbursement categories that recognize device-enabled and biologic modalities.
Competitive highlights (selected)
-
Pfizer Inc. (New York, USA) remains a dominant supplier of opioid analgesics and continues to be central to access strategies where opioids remain standard of care for advanced cancer pain.
-
Johnson & Johnson (Janssen) (New Brunswick, USA) continues commercialization of long-acting transdermal opioids for chronic cancer pain, maintaining provider relationships in oncology and palliative networks.
-
Teva Pharmaceutical Industries Ltd. (Tel Aviv, Israel) sustains broad generics coverage that shapes price dynamics and payer negotiation leverage across markets.
-
Mundipharma (Cambridge, UK), Eli Lilly (Indianapolis, USA), Novartis (Basel, Switzerland), and AstraZeneca (Cambridge, UK) play strategic roles by integrating analgesic therapies into broader oncology and supportive-care portfolios.
-
Smaller innovators such as WEX Pharmaceuticals (Vancouver, Canada), Tetra Bio-Pharma (Canada), and Autonomix Medical (USA) are notable for pioneering non-traditional modalities — from tetrodotoxin-based injectables and cannabinoid investigational therapies to transvascular radiofrequency ablation platforms — that are shifting clinical practice for specific, high-unmet-need cohorts.
Recent clinical and commercial developments shaping 2026 tactics
-
Autonomix Medical: clinical data and trial expansion. Autonomix expanded its proof-of-concept program in 2025 and presented long-term clinical data in 2026 on a transvascular RF ablation approach for pancreatic cancer pain. These indicators suggest a maturing interventional niche with potential to broaden beyond single-cancer indications — a key signal for investors and acquirers assessing the interventional portfolio opportunity.
-
WEX Pharmaceuticals / Dogwood Therapeutics: positive interim efficacy. Collaboration results showing improved relief in chemotherapy-induced neuropathic pain mark a critical inflection for small-molecule or biologic candidates that target neuropathic pathways, potentially unlocking new ambulatory indications.
-
Device reimbursement evolution. CMS’s recognition of certain electronic infusion pumps for separate Medicare payment under recent regulatory changes (effective January 1, 2026) creates commercial incentives for providers to adopt device-enabled delivery systems and for suppliers to innovate around value-based delivery models.
Policy and payer dynamics — implications for 2026 plans
Policy and reimbursement developments over 2024–2026 are re-defining the economics of pain management. Key dynamics include:
-
Regulatory acceleration of non-opioid programs: recent guidance from the U.S. FDA to expedite development of safe, effective non-opioid analgesics reduces time-to-market uncertainty for novel therapeutics, reshaping R&D prioritization.
-
Opioid stewardship frameworks: authoritative prescribing guidelines continue to delineate cancer and palliative exceptions, influencing prescriber behavior but not eliminating demand for opioids in advanced disease contexts.
-
Reimbursement carve-outs: new payment rules for qualifying non-opioid devices and supplies — including temporary statutory provisions tied to specific acts — create near-term windows to demonstrate economic value and scale adoption before sunset provisions or subsequent rulemaking.
-
Controlled-substance quotas: recent adjustments to production quotas for key opioids have ripple effects on supply security, pricing, and substitution strategies across markets.
What’s in the PW Consulting report (practical deliverables)
The report is intentionally practice-focused to support immediate strategic decision-making in 2026. It includes:
-
Topline market sizing and a transparent forecasting model (2026–2032) built on demand drivers, price trends, and clinical adoption curves.
-
Scenario-based strategic roadmaps that quantify the impact of alternative regulatory and reimbursement outcomes on portfolio economics.
-
Competitive benchmarking with capability maps, partnership fit matrices, and M&A scorecards tailored to both incumbent and challenger archetypes.
-
Go-to-market playbooks for device-enabled solutions, specialty pharmacotherapies, and integrated service models aimed at oncology centers and palliative care networks.
-
Operational checklists for clinical development, payer evidence generation, and cross-functional commercialization to accelerate adoption in the 2026 policy environment.
Note: per the “trailer” approach of this release, we have deliberately withheld granular regional and modality-level revenue splits and payor-specific pricing tables from this public preview. These detailed tables, along with our proprietary unit economics model and market maps, are available through the full report package.
Strategic implications and recommended 2026 actions
-
Reassess portfolio sequencing: Prioritize assets that benefit from new reimbursement codes and those least exposed to quota-constrained opioid supplies. Consider fast-follower investments in device-enabled delivery and non-opioid pharmacologies where regulatory pathways have become clearer.
-
Accelerate strategic partnerships: For innovators, 2026 is an opportune window to transact with incumbents seeking differentiated assets to complement large analgesic franchises or to shore up supply chains.
-
Invest in payer evidence now: Rapidly develop value dossiers that capture cost offsets enabled by non-opioid therapies and device interventions — early payer engagement will materially shorten coverage timelines.
-
Scenario-proof the supply chain: Implement contingency plans for controlled-substance sourcing and identify alternative delivery or therapeutic options that mitigate quota-related disruption risk.
-
Operationalize real-world evidence capabilities: Deploy pragmatic trials and registries focused on quality-of-life endpoints and health-economic outcomes to accelerate reimbursement and guideline inclusion.
Final note — how PW Consulting can help
For executives designing 2026 strategies, this report provides both the evidence base and pragmatic playbooks needed to make confident resource allocation decisions. If your team is evaluating portfolio pivots, partnership targets, or payer-engagement strategies in advanced cancer pain management, PW Consulting’s full dataset and scenario models will help convert strategic intent into measurable outcomes.
To access the complete report — including the proprietary segmentation datasets, granular regional and modality breakdowns, CR3/CR5 concentration analytics, and financial models — please visit our report page. The full package contains the operational templates and excel models required to integrate these insights directly into your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Advanced Cancer Pain Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Inflatable Above‑Ground Pool Market Set to Expand at a 6.18% CAGR in the 2026–2032 Forecast, Reveals New Growth Opportunities
By pmarketresearch, 2026-07-15
Worldwide Inflatable Above Ground Pool Market: Strategic Imperatives for 2026
Executive Preview — PW Consulting
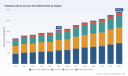
The global inflatable above ground pool market has evolved from a seasonal consumer niche into a strategically relevant segment for manufacturers, retailers, and investors. Our new market study — base year 2025, forecast period 2026–2032 — shows that the industry grew from approximately USD 1,180 Million in 2020 to USD 1,580 Million in 2025, and, at an expected compound annual growth rate (CAGR) of 6.18%, is projected to expand materially through 2032. These headline figures position the market as a medium-growth, capital-efficient opportunity for companies that can rapidly adapt to new safety regulations, raw-material volatility, and shifting consumer channels in 2026.
Worldwide Inflatable Above Ground Pool Market
Why this report matters for 2026 decision‑makers
-
Timing and scale: 2026 is the first full planning year after a series of industry shocks — notably high‑profile product recalls and material market shifts — making rapid, evidence‑based strategy essential for capital allocation, product roadmap prioritization, and channel investments.
Worldwide Inflatable Above Ground Pool Market -
Risk and reputation: Product safety incidents have moved from isolated operational headaches to enterprise-level brand and legal risks. Executives who can operationalize safety into design, supplier selection, and go‑to‑market processes will preserve market share and avoid costly disruptions.
Worldwide Inflatable Above Ground Pool Market -
Margin and sourcing dynamics: PVC and related resin markets remain volatile. Our scenario work shows procurement strategies enacted in 2026 — hedging, supplier diversification, nearshoring, or design substitution to alternative polymers — will distinctly separate resilient players from those subject to margin compression.
-
Channel transformation: E‑commerce and omnichannel execution continue to shift the economics of seasonal leisure goods. 2026 is a pivotal year to reallocate marketing and logistics spend toward channels with demonstrable return on spend and post‑sale support capabilities.
Recent industry developments shaping 2026
-
Product safety and recall dynamics: A mid‑2025 recall affecting several major manufacturers highlighted systemic product‑safety exposures in models using particular external compression features. This event — and the regulator engagement that followed — has amplified compliance expectations globally and accelerated demand for third‑party testing and design change management.
-
Raw material environment: Late‑2025 downward movement in PVC resin pricing created near‑term buyer leverage, but the underlying supply‑demand dislocation remains. Volatility across PVC, polyethylene, and steel persists and must be modeled into 2026 sourcing and pricing strategies.
-
Manufacturer responses: Several producers announced catalog releases, capacity ramps, and expanded OEM/ODM offerings entering 2026 — underscoring an industry preparing to capitalize on both backyard leisure demand and rising adult/premium segments.
What PW Consulting’s report delivers — practical, actionable intelligence
-
A rigorously sourced market size and forecast model (2020–2032) with downloadable Excel scenarios and sensitivity analyses tied to price, raw material, and regulatory variables — enabling CFOs and commercial leads to stress‑test FY26 budgets.
-
Operational playbooks for product safety lifecycle management, covering design checkpoints, independent testing protocols, recall preparedness, and consumer communications — intended for product and legal teams.
-
Supply‑chain and procurement tools, including supplier‑risk heat maps, cost‑to‑source models, and recommended hedging approaches to stabilize margins in volatile resin markets.
-
Channel and commercial strategies that map profitability across direct e‑commerce, mass retail, and specialty distribution — with playbooks for assortment, pricing, promotional cadence, and post‑sale service economics.
-
Competitive intelligence dossiers on leading participants, M&A opportunity screening, and an M&A valuation framework tailored to seasonality, inventory risk, and recall liabilities.
-
A regulatory and compliance checklist aligned to key jurisdictions and standards, including applicable ASTM/CPSIA considerations — enabling product teams and compliance officers to operationalize legal requirements into release gates.
Note: This press overview intentionally omits the detailed segmentation tables and region/application breakdowns contained in the full report. These granular datasets are provided to licensed report purchasers to underpin commercial models and investment memoranda.
Competitive landscape — positioning and strategic implications
The market sits in a moderately concentrated competitive structure: the three‑player concentration (CR3) and five‑player concentration (CR5) metrics show meaningful leadership by established brands but leave room for agile entrants and consolidation plays. Our qualitative assessment of leading participants highlights the following strategic archetypes.
-
Global brand incumbents with broad retail reach — firms with household recognition and deep mass‑retail distribution continue to leverage scale in manufacturing and logistics. Their strengths are marketing reach and seasonal shelf presence; their vulnerability lies in complexity when executing rapid design changes or recalls.
-
Vertically integrated manufacturers — companies that retain control over manufacturing and some raw material inputs can protect margins during input volatility and offer competitive OEM pricing. Their strategic choice is balancing scale with nimbleness in product development.
-
Niche premium and design‑led brands — smaller players pursuing adult, lifestyle, or design‑first pools generate higher ASPs and better customer loyalty but must scale distribution and service to maintain growth.
-
OEM/ODM specialists — suppliers offering customizable solutions to retailers and private‑label partners present an attractive partner model for entrants wanting speed to market without heavy capex.
Our report includes tactical profiles of the core players, their geographies of emphasis, value propositions, and near‑term strategic moves — all geared to support competitor benchmarking and partnership screening.
Key strategic priorities for 2026 (what to do next)
-
Make safety a commercial differentiator: convert compliance investments into customer trust through transparent testing, extended warranties for affected models, and proactive consumer education.
-
Rework procurement and product bills of materials to reduce single‑supplier exposure to PVC and other volatile inputs; evaluate polymer alternatives and design changes that reduce material intensity without compromising durability.
-
Rebalance portfolio cadence: prioritize SKUs that generate stable margin outside peak season (premium, durable, adult-oriented models) while streamlining low‑margin, high‑inventory items.
-
Operationalize recall resilience: implement a rapid traceability stack, recall simulation exercises, and a customer remediation budget embedded in annual planning.
-
Execute channel experiments with rigorous KPI governance: test marketplace promotions, subscription‑based replacement parts, and service bundles that extend lifecycle revenue.
-
Scan for inorganic opportunities: acquisition targets should be screened not only for revenue but for manufacturing footprint, testing capabilities, and intellectual property that reduce product‑safety exposure.
Scenario framing for boardrooms
-
Base Case (aligned with our headline CAGR): steady growth, gradual premiumization, and moderate margin pressure from raw‑material swings. Recommended focus: efficiency and safety investments to lock in share.
-
Upside Case: accelerated adult/premium adoption and favorable resin pricing deliver above‑trend growth. Recommended focus: scale premium lines, increase direct‑to‑consumer investments, and opportunistic capacity expansion.
-
Downside Case: regulatory shocks or another large recall depress demand and force inventory write‑downs. Recommended focus: liquidity preservation, deferred capex, and acquisition of distressed assets with long‑term upside.
Next step — how to use this research in Q1–Q2 2026
Corporate leaders should use the report to finalize FY26 capital plans, set procurement hedges, and define safety/design priorities that will be embedded into product development roadmaps. Commercial teams can leverage our channel playbooks and pricing sensitivity models to optimize promotional calendars and SKU rationalization ahead of the 2026 selling season.
Accessing the full intelligence
This release is a strategic preview intended to orient decision‑makers. The full PW Consulting Worldwide Inflatable Above Ground Pool Market report contains the complete set of segmentation tables, regional and application breakdowns, company financial matrices, and the downloadable forecast model essential for investment committees and operating plans. Licensed purchasers receive the dataset and a one‑hour briefing with our lead analyst to translate the findings into actionable initiatives for 2026.
PW Consulting — Senior Strategic Advisor and Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Worldwide Inflatable Above Ground Pool Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Amino Acid-Based Formula Market to Grow from USD 1,638.7 Million in 2025 to USD 2,790.28 Million by 2032 at a 7.9% CAGR
By pmarketresearch, 2026-07-15
Worldwide Amino Acid Based Formula Market — Strategic Preview for 2026 Decisions
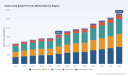
PW Consulting today releases an executive preview of our latest Worldwide Amino Acid Based Formula Market study (base year: 2025; forecast period: 2026–2032). The amino acid based formula category — a medically indicated subset of infant and pediatric nutrition — has demonstrated resilient growth through the pandemic recovery and is entering a phase of structural expansion. Our model pegs the global market at approximately USD 1,638.7 Million in 2025, rising at a compound annual growth rate (CAGR) of 7.9% through the forecast window. By 2032 the category approaches multi‑billion dollar scale under the base-case projection, underscoring why 2026 is a pivotal year for commercial, manufacturing and regulatory strategy formation.
Worldwide Amino Acid Based Formula Market
What this report delivers — practical, decision‑grade intelligence
- Forward-looking revenue model (USD Million) with scenario alternatives calibrated to regulatory, reimbursement and raw‑material shocks — enabling board‑level financial planning and sensitivity analysis.
- Competitive landscape with differentiated canvases for market share drivers, route‑to‑market maps, and product life‑cycle positioning tailored to amino acid‑based medical nutrition.
- Regulatory heat map across principal markets that translates classification, labeling and exempt‑formula frameworks into concrete launch timelines and risk buffers.
- Reimbursement and formulary playbook detailing payor engagement strategies, coverage triggers and state‑level nuances for prioritizing market access investments.
- Manufacturing and supply‑chain playbook, including cost‑to‑serve modeling for free amino acid sourcing, recommended buffer inventories, and candidate CDMO profiles for scale or rapid response.
- Go‑to‑market and clinical evidence templates: protocol outlines for real‑world evidence (RWE), health economic dossiers and physician engagement to shorten adoption cycles in specialty channels.
Market dynamics shaping 2026 strategic choices
Three structural dynamics underpin the category expansion and should be front and center for 2026 plans:
Worldwide Amino Acid Based Formula Market
- Clinical adoption anchored in medical necessity. Amino acid formulas remain the standard of care for infants and children with severe cow’s milk protein allergy (CMPA), multiple food allergies, or malabsorptive conditions. Clinical guidelines and payer pathways materially influence uptake — where coverage and clear prescription protocols exist, utilization accelerates.
- Cost structure and pricing pressure. These formulas rely on free amino acids as the core protein source rather than intact or hydrolyzed proteins. That upstream ingredient profile drives higher unit production costs and elevated retail prices, creating margin tension and a premium‑pricing opportunity that is sensitive to commodity movements and scale economics.
- Concentration and competitive barriers. The category exhibits a high degree of concentration among established specialty nutrition manufacturers, creating both advantages in clinical trust and challenges for new entrants. Market concentration implies high go‑to‑market friction but also signals opportunities for niche innovation and service differentiation (e.g., extended‑age formulations, ingredient enhancements, or tolerance‑focused clinical programs).
Competitive snapshot: what leading players signal to the market
The competitive landscape is dominated by established global nutrition and medical‑food companies. Each incumbent brings different strengths that shape opportunity windows for competitors and partners:
Worldwide Amino Acid Based Formula Market
- Abbott Laboratories (EleCare): Strong clinical adoption and brand trust in specialty pediatric channels, recently expanded into older‑child formulations with product innovations that broaden total addressable population beyond infancy. New product introductions signal strategic focus on lifecycle expansion and nutrient fortification targeted at neurodevelopmental claims.
- Mead Johnson Nutrition (Reckitt) — PurAmino: Positioned with heritage in pediatric nutrition and distribution muscle across hospital formularies and outpatient specialty pharmacies. Their portfolio emphasizes DHA/ARA inclusion and clinician familiarity, making them a durable competitor in medically managed segments.
- Nestlé Health Science — Alfamino: Offers broad geographic reach and scale but recent regulatory events in key markets have introduced heightened oversight and short‑term supply disruptions, illustrating reputational and operational risks even for large incumbents.
- Nutricia (Danone) — Neocate: A clinically entrenched brand with deep relationships in tertiary care centers and a strong product family spanning infant to older‑child needs. Their focus on clinical evidence and specialty channel access creates barriers to switching for prescribers.
Recent company‑level developments — product launches and product recalls — act as leading indicators for two important themes in 2026 planning: (1) product lifecycle extension (age and nutritional add‑ons) will be a primary route to grow share, and (2) operational resilience and quality governance will separate winners from laggards as regulators increase scrutiny.
Regulatory and reimbursement levers — practical implications
Regulatory classification matters more than ever. In key markets, amino acid formulas are managed as exempt or specialty products intended for use under medical supervision. This status creates a dual opportunity: clarity of indication supports premium positioning and physician prescribing, while the exempt/specialty status imposes strict manufacturing and labeling obligations. In the U.S., several amino acid formulas appear on the FDA’s exempt list and are subject to targeted oversight — market entrants must design dossiers and lot‑release processes to align with these expectations before launch.
On reimbursement, public programs and private payors are pivotal. In many jurisdictions, medically necessary amino acid‑based formulas may be eligible for coverage under public nutrition programs or hospital formularies, with state and insurer variability. 2026 commercial strategy must therefore prioritize payor evidence packages and state‑level engagement to unlock access and limit out‑of‑pocket barriers for patients.
Operational imperatives for 2026
- Strengthen quality systems and batch traceability. Recent recalls in 2026 highlight how a single quality event can trigger market access reversals and payer scrutiny; 2026 investment in enhanced QA/QC, supplier audits and serialization will be insurance against regulatory shocks.
- Secure amino‑acid supply and diversify vendors. Given elevated raw material cost and concentration, risk mitigation through multi‑sourcing, forward contracts and strategic inventory is non‑negotiable for manufacturers and CDMOs.
- Design flexible manufacturing footprints. A two‑tier approach — core volumes in low‑cost, high‑quality plants and rapid‑response regional lines for emergency supply — reduces time‑to‑supply risk in the event of recalls or logistic interruptions.
- Prioritize evidence generation that matters to payors and prescribers. RWE, growth and tolerance endpoints, and health economic models that quantify cost offsets versus alternative clinical pathways unlock formulary inclusion and justify reimbursement.
Scenario planning — three actionable paths for 2026
- Base case (aligned with 7.9% CAGR): Gradual adoption continues, reimbursement improves incrementally, incumbents defend share via product extensions. Recommended actions: accelerate medical affairs engagement; secure supply; align pricing with value dossiers.
- Upside case: Policy shifts and stronger public program coverage drive faster uptake. Recommended actions: scale manufacturing capacity, prioritize market entries with fast coverage, and deploy aggressive clinician education programs to capture share.
- Downside case: Regulatory events or raw ingredient shortages cause transient contraction. Recommended actions: implement contingency supply plans, activate recall‑ready communication protocols, and seize competitor disruptions with targeted local promotions and supply assurances.
How executives should use this report in 2026
We designed this study to be immediately usable across three horizons:
- 90‑day plays: supplier qualification checklists, quality‑control gap analysis, and priority payor engagement templates.
- 12‑month plans: capacity investment decisions, product roadmap prioritization (e.g., extended‑age SKUs), and commercial launch sequencing tied to reimbursement timelines.
- 3‑year strategy: M&A screening for bolt‑on clinical brands or CDMOs, global supply‑chain reshoring scenarios and R&D pipelines aligned to tolerance and tolerance‑enhancing ingredients.
Why PW Consulting’s perspective matters
Our analysis combines proprietary market modeling with supply‑side interviews across manufacturers, CDMOs and clinical leaders, payer policy scans and real‑world prescribing datasets. The result is not just a point forecast but an operational playbook linking top‑line scenarios to concrete manufacturing, regulatory and commercial actions. For executives assessing investment, M&A, or market entry in 2026, the value lies in the linkage between plausible near‑term disruptions and executable mitigations — not simply in headline growth rates.
Next steps and how to obtain full intelligence
This release is a strategic preview highlighting direction and decision levers. The comprehensive PW Consulting report includes the granular, segment‑level demand models, regional channel breakdowns, product‑form forecasts, and interactive scenario spreadsheets that we intentionally withhold from this preview. Those detailed matrices — including market splits by region, product form and age cohort, plus unit economics and price curves — are available in the full report and interactive dashboard for licensed clients.
For 2026 planning, organizations should prioritize (1) immediate audit of quality and supplier exposures, (2) rapid development of payer value evidence, and (3) scenario‑based capacity planning. PW Consulting stands ready to brief executive teams and tailor the report’s models to enterprise budgets, portfolio ambitions and M&A pipelines.
To request the full report and an executive briefing, please consult PW Consulting’s corporate channels — the preview above maps the strategic terrain; the full deliverable contains the tactical coordinates required for execution.
For detailed analysis of this topic, please visit the official page: Worldwide Amino Acid Based Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide External Pacemakers Market to Reach USD 1,864.9 Million by 2032, Expanding at a 4.74% CAGR (2026–2032)
By pmarketresearch, 2026-07-15
Worldwide External Pacemakers Market — Strategic Outlook for 2026: Why Executive Teams Must Recalibrate Now
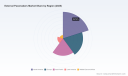
PW Consulting’s latest market study — Worldwide External Pacemakers Market (base year 2025; historical window 2020–2025; forecast 2026–2032) — equips senior executives and investment committees with the forward-looking intelligence required to make high-stakes decisions in 2026. The market is stable and predictable at the macro level, with a compound annual growth rate (CAGR) of 4.74% through the forecast horizon. From an estimated market size in 2025 through 2032, the trajectory we model reflects secular demand in acute cardiac care, modest replacement cycles, regulatory reclassification tailwinds, and incremental reimbursement opportunities tied to remote physiologic monitoring. This release outlines the strategic takeaways senior leaders should prioritize while intentionally withholding the granular region- and application-level splits contained in the full report to preserve the commercial value of the proprietary dataset.
Worldwide External Pacemakers Market
Why this market matters to 2026 corporate strategies
-
Predictable top-line expansion: A mid-single-digit CAGR provides a planning anchor for product roadmaps, capacity investments, and commercial coverage assumptions. The market growth is sufficiently steady to support staged investments while still offering pockets of outsized opportunity for differentiated product entrants.
Worldwide External Pacemakers Market -
Consolidation and concentration dynamics: Market concentration is high; the leading firms capture a dominant share of industry revenues. This concentration profile amplifies the importance of competitive benchmarking and targeted differentiation for any new entrant or incumbent seeking share gains.
Worldwide External Pacemakers Market -
Regulatory and reimbursement inflection points: Recent and pending regulatory and reimbursement shifts have immediate operational implications for 2026. These include long-standing device reclassification precedents and the emergence of CPT codes for remote physiologic monitoring that change the commercial calculus for devices that can integrate monitoring telemetries.
What PW Consulting’s report delivers — practical, decision-ready modules
-
Proprietary market sizing and forecasting model (2020–2032): A transparent, scenario-capable financial model with baseline, upside, and downside cases calibrated to procedure volumes, device lifecycles, and device substitution dynamics. The model is provided in an executable workbook so teams can stress-test assumptions against internal data.
-
Strategic playbooks: Action-oriented go-to-market playbooks tailored for (a) incumbent market leaders looking to defend share, (b) smaller OEMs seeking targeted expansion, and (c) private-equity-backed platforms evaluating roll-up strategies.
-
Regulatory pathway mapping: Practical checklists and timeline estimates for 510(k)/Class II pathways, conformity with 21 CFR 870.3600, and country-specific practicalities that materially affect time-to-market and CAPEX plans.
-
Reimbursement impact analysis: A focused assessment of how new remote monitoring CPT codes and evolving payer policies can alter total cost of ownership for hospitals and ambulatory providers, and therefore affect procurement parameters and tender outcomes.
-
Competitive benchmarking and capability matrices: Deep profiles of the leading manufacturers across product portfolios, clinical capabilities, distribution reach, and service models — enabling rapid identification of strategic vulnerability or acquisition targets.
-
Supply-chain and manufacturing risk register: Supplier concentration mapping, single-source component sensitivities, and mitigation levers, including alternate suppliers and localized sourcing strategies to reduce lead-time variability.
-
Clinical adoption and hospital decision framework: Evidence synthesis and a decision-tree for hospital procurement committees that maps clinical use cases to procurement levers, clinician adoption barriers, and managed-care contracting approaches.
Competitive landscape — who shapes the market and how
The market is shaped by a mix of global device majors, specialized cardiac device manufacturers, and regionally focused suppliers. The top-tier companies blend product breadth, clinical trial portfolios, and deep customer relationships; mid-tier and regional players compete on cost, speed-to-local-market, and tailored service models. The market’s concentration metrics indicate dominant positions among the largest suppliers, with the top three players controlling a substantial majority of revenues and the top five capturing an even larger proportion.
-
Medtronic (Dublin, Ireland) — A global leader with a diversified cardiac rhythm management franchise; their temporary external pacing offerings are integrated into large clinical and post-surgical workflows. Medtronic’s scale enables investments in clinical evidence generation and bundled service propositions that are challenging for smaller players to match. ( https://www.medtronic.com)
-
Boston Scientific (Marlborough, MA, USA) — Positions external pacing capabilities within a broader electrophysiology and EP lab systems portfolio, which creates synergies for cross-selling and integrated procedural workflows. Their strength lies in system-level offerings that appeal to high-throughput centers. ( https://www.bostonscientific.com)
-
ZOLL Medical (Chelmsford, MA, USA) — Known for portable external pacing integrated with emergency resuscitation systems; this orthogonal product approach appeals to emergency and critical-care pathways where mobility and integrated defibrillation/pacing are decision drivers. ( https://www.zoll.com)
-
BIOTRONIK (Berlin, Germany) , Abbott Laboratories (Abbott Park, IL, USA) , and Oscor Inc. (Palm Harbor, FL, USA) — These firms combine targeted external pacing devices with complementary CRM or procedural portfolios; their strategic playbooks emphasize clinical partnerships and procedural efficiency.
-
Osypka Medical (Germany) , Lepu Medical (Beijing) , MicroPort (Shanghai) , and regional manufacturers — These companies compete effectively in segment-specific or geographic niches by offering form-factor innovation, localized support, and price-competitive options.
-
Adjacent suppliers such as Cook Medical supply critical consumables (temporary pacing wires and leads) that are essential to the external pacing ecosystem; their role in procurement strategies and bundle negotiations is often underappreciated by strategic planners.
Regulatory and reimbursement dynamics that will re-shape 2026 execution
-
Regulatory context: External pacemaker pulse generators are regulated under 21 CFR 870.3600 in the U.S., and historic regulatory precedents — including the FDA’s reclassification of related pulse generators to Class II with special controls — materially lower the entry barrier and compress time-to-market for certain device updates. Companies should incorporate these regulatory timelines into product launch planning to avoid costly delays.
-
Reimbursement catalysts: The 2026 CMS updates introduced new CPT codes covering remote physiologic monitoring device supply for multi-day data transmission windows. For external pacemakers that can pair with telemetric monitoring systems, these codes create a pathway to monetize remote monitoring workflows and improve hospital economics for continuous post-procedural surveillance.
-
Recent market signal: Early regulatory activity continues; for example, a 510(k) clearance for a novel external pacemaker pulse generator was publicized in early 2025, demonstrating ongoing product innovation and regulatory movement in this device class.
Actionable recommendations for executive teams in 2026
-
Re-evaluate portfolio fit against bundled clinical workflows: With reimbursement increasingly tied to monitoring and service bundles, firms should prioritize integrations (software + device) that enable capture of new revenue streams and defend hospital procurement decisions.
-
Targeted M&A and partnerships: Use the market’s concentration to your advantage — identify tuck-in targets that fill gaps in form factor, telemetry, or geographic distribution. Sellers with established hospital relationships and consumable bundles are especially valuable.
-
Protect margin via supply-chain resilience: Firms should quantify single-source risks for critical components and implement dual-sourcing or near-shoring where financially feasible to protect against delivery disruptions.
-
Invest in clinical evidence for differentiated claims: Smaller firms can neutralize scale advantages by generating robust, pragmatic clinical evidence that demonstrates improved workflow efficiency or lower total cost of care.
-
Commercialize remote-monitoring capabilities: For product teams, prioritize roadmaps that enable remote physiologic data capture and secure transmission to leverage the new CPT codes and improve hospital value propositions.
How PW Consulting’s report supports your 2026 decision cycle
Our report is designed as a working tool for C-suite and board-level decision-making. It combines a fully auditable market model, playbooks that translate market dynamics to quarter-by-quarter actions, and competitor intelligence calibrated to support investor diligence and commercial due diligence. To respect the “trailer” principle and preserve the commercial integrity of our proprietary research, we have intentionally refrained from publishing the full regional, type, and end-user splits in this release. These granular datasets — including the driver-level mechanics that underpin our top-line forecast — are included in the full report and accompanying financial model.
For executive teams preparing budgets, prioritizing R&D spend, or evaluating M&A targets in 2026, the full dataset and scenario model will accelerate alignment between clinical, regulatory, and commercial functions.
Next steps
-
Download the full report and the model to access the complete regional and application-level segmentation, the underlying assumptions, and the actionable playbooks referenced herein.
-
Engage PW Consulting for a tailored executive workshop to translate the findings into a 90-day action plan aligned to your organization’s strategic objectives and risk appetite.
Contact PW Consulting to request the full Worldwide External Pacemakers Market report, the supporting forecast model, and bespoke advisory services to convert this market intelligence into executable strategies for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide External Pacemakers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Private Client Tax Services Market Set to Reach USD 20,392.72 Million in 2025
By pmarketresearch, 2026-07-15
Worldwide Private Client Tax Services Market — Strategic Outlook for 2026 Decision-Making
Executive snapshot
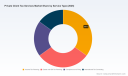
PW Consulting’s latest market study, with base year 2025, positions the global private client tax services market as a resilient and strategically significant sector for the next investment cycle. After sustained expansion through the first half of the decade, the market is estimated at USD 20,392.72 Million in 2025 and is projected to grow at a compound annual growth rate (CAGR) of 5.81% over the 2026–2032 forecast window, reaching roughly USD 30,260.42 Million by 2032. The very next year — 2026 — is expected to see the market pass the USD 21.5 Billion threshold, underscoring an inflection where advisory-led revenue increasingly complements traditional compliance work.
Worldwide Private Client Tax Services Market
Why this matters for boards and private client leaders in 2026
-
Capital allocation: Firms must reconcile near-term revenue stability from compliance work with longer-term margin improvement available through higher-value advisory and productized solutions.
Worldwide Private Client Tax Services Market -
Go-to-market positioning: A growing and predictable market base creates room for premium segmentation — but success depends on clear differentiation in cross-border capability, family office services, and bespoke succession planning.
Worldwide Private Client Tax Services Market -
Regulatory risk as a growth lever: Intensifying enforcement of global information-exchange regimes turns compliance into a client acquisition channel rather than a commoditized afterthought.
-
Talent and delivery model: The war for tax specialists with multi-jurisdictional skills will shape operating costs, pricing power, and the feasibility of high-touch offerings.
How PW Consulting’s report translates to operational decisions
The report is designed as a decision-grade resource for executives and deal teams planning activity in 2026. It combines rigorous market sizing and scenario modelling with actionable modules that executives can operationalize without redoing the work from scratch. Highlights include:
-
Scenario-driven market forecasts that translate the headline CAGR into addressable opportunity maps under conservative, base-case, and accelerated-adoption scenarios.
-
Methodology notes and reproducible models (base year 2025) that allow internal teams to stress-test assumptions against firm-level KPIs.
-
Regulatory risk heatmaps and a prioritized list of compliance imperatives (CRS, FATCA, and multi-jurisdiction reporting) that directly map to product and resourcing decisions.
-
Provider scorecards and capability matrices that profile major incumbents across advisory depth, international capability, family-office services, and technology adoption — enabling rapid shortlist creation for partnerships, vendor selection, or M&A targets.
-
Playbooks for packaging services (tiered bundles, subscription models, success-fee arrangements) and a set of pricing archetypes that preserve confidentiality but provide relative benchmarks for negotiation.
-
Talent and operating-model blueprints covering insourcing vs. co-sourcing trade-offs, centre-of-excellence design, and productivity levers from automation and AI-assisted tax workflows.
Competitive landscape — concentration, capability, and momentum
The market exhibits moderate concentration: the top three providers capture a meaningful but not overwhelming share of revenue, and the top five consolidate a majority position. This structure creates a two-track competitive dynamic. Global incumbents leverage scale and integrated advisory capabilities to win complex, cross-border mandates; meanwhile, regional and specialist players continue to capture niche flows from family offices, entrepreneurial clients, and vertically focused wealthy cohorts.
Leading global firms — including the largest professional-service networks based in the United Kingdom and the Netherlands, and major US-headquartered regional players — continue to expand their private client offerings by bundling wealth planning, estate and gift advisory, international tax structuring, and enhanced compliance services. Mid-market advisors and national specialists are countering with highly personalized service models and rapid responsiveness to regulatory change.
Recent market activity underscores these dynamics: recognitions of leading firms for client service excellence, the publication of client-reporting surveys and wealth-planning guides, and specialist insights on asset diversification and cross-border wealth protection. These developments are symptomatic of a competitive race that is increasingly about technical depth, client experience, and packaged advisory products rather than price alone.
Regulation, talent and technology: the three forces shaping 2026 strategies
-
Regulatory intensification: Continued enforcement of international exchange standards is driving higher demand for compliance, but also creating upstream advisory needs around structuring, repatriation, and voluntary disclosures. Firms that fold regulatory mechanics into advisory work create sticky client relationships.
-
Talent scarcity and cost: Tax specialists who combine technical competence with client-facing advisory skills are scarce. Expect wage inflation in specialist roles and pressure to redesign delivery models that combine experienced advisors with AI-enabled junior teams to preserve margins.
-
Technology and AI: Adoption of AI for document review, tax provision analytics, and scenario modelling is accelerating. Early adopters reduce turnaround, enhance quality, and create new product lines (e.g., tax-scenario simulators for succession planning).
Strategic imperatives for 2026
-
Productize premium advisory: Convert bespoke high-touch engagements into repeatable, tiered offerings (e.g., packaged cross-border onboarding, subscription compliance + advisory blends) to improve predictability and margins.
-
Prioritize cross-border capability: Invest selectively in multi-jurisdictional desks and secondment programs or acquire boutique specialists to accelerate capability without lengthy organic build.
-
Embed compliance as an acquisition channel: Use automated CRS/FATCA readiness and voluntary-disclosure advisory as a foot-in-the-door service that articulates the firm’s technical credibility.
-
Design hybrid talent models: Combine senior advisory talent with centralized automation hubs to deliver scalability and limit full-time headcount inflation.
-
Targeted M&A and alliance criteria: Look for targets that provide either differentiated client segments (family offices, UHNW networks) or proprietary tech/IP that accelerates delivery automation and enhances client stickiness.
How to use the report in 90 days
-
Week 1–2: Run the included scenario models against internal revenue and margin targets to quantify the size of incremental advisory opportunity for 2026.
-
Week 3–6: Map client rosters to PW Consulting’s capability matrices to identify 10–15 priority clients for cross-sell and productized offerings.
-
Week 7–12: Implement a pilot productized offering (compliance + advisory subscription) and measure time-to-delivery, NPS, and contribution margin using the report’s reporting templates.
What the report does not reveal — and why that is strategic
Following the “trailer” principle, this article highlights the market trajectory, structural drivers, competitive dynamics, and pragmatic playbooks you can use in 2026. To preserve the tactical advantage and ensure commercial confidentiality, the report withholds raw sub-segmentation tables in public summaries — detailed regional-, service-, and client-category revenue splits, full provider scorecards with calibrated capability scores, and downloadable forecasting workbooks are available in the full report package. These elements are essential for precise deal underwriting, M&A valuation, andbid design and are intentionally gated to authorized purchasers.
Closing — why act now
2026 will be a decisive year for private client tax service providers and their clients. The market is large, growing at a mid-single-digit CAGR, and at a cusp where advisory-led models can materially re-shape margin pools. Firms that move quickly to repackage services, shore up multi-jurisdiction talent, and embed compliance as a value-adjacent service will capture disproportionate upside. PW Consulting’s Worldwide Private Client Tax Services Market report is engineered to convert market-level forecasts and regulatory signals into executable operational plans and investment theses for the coming year.
For executives ready to translate 2026 strategy into measurable actions — including access to the full datasets, provider scorecards, and scenario playbooks referenced here — please visit the report landing page to request the complete deliverable and the accompanying modelling assets.
For detailed analysis of this topic, please visit the official page: Worldwide Private Client Tax Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com