

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Advanced Cancer Pain Management Market Poised to Expand at a 6.55% CAGR Through 2032

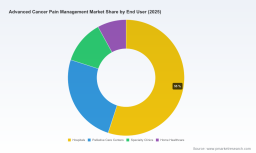
Worldwide Advanced Cancer Pain Management Market — Strategic Preview for 2026 Decision-Making
PW Consulting’s new market intelligence brief, Worldwide Advanced Cancer Pain Management Market (base year 2025; historical coverage 2020–2025; forecast 2026–2032), synthesizes clinical innovation, regulatory shifts, reimbursement reforms, and competitive positioning into a single, actionable narrative designed for boards, corporate strategy teams, and investors preparing 2026 priorities. Our forecast models project the market to expand from an estimated USD 8,424.42 million in 2025 to USD 13,134.49 million by 2032, representing a compounded annual growth rate (CAGR) of 6.55% over the 2026–2032 period. These topline dynamics underpin four strategic imperatives companies must address heading into 2026.
Worldwide Advanced Cancer Pain Management Market
Why this report matters for 2026 strategic choices
-
Timing and portfolio prioritization — With accelerating non-opioid therapeutic development and targeted interventional technologies, 2026 is a pivot year for reallocating R&D and commercialization budgets toward differentiated modalities that capture durable, reimbursable value.
Worldwide Advanced Cancer Pain Management Market -
Regulatory and reimbursement arbitrage — New regulatory guidance and reimbursement pathways are reshaping product economics; understanding the interplay between these forces is essential to set realistic go-to-market timelines and pricing strategies.
Worldwide Advanced Cancer Pain Management Market -
M&A and partnership rhythm — Moderate market concentration combined with rapid clinical innovation creates recurring windows for bolt-on acquisitions and strategic collaborations; being positioned as a credible partner or buyer in 2026 will materially change growth trajectories through 2032.
Topline market trajectory (high-level)
PW Consulting’s topline model characterizes a steady expansion in aggregate demand across therapeutic and interventional approaches. After a historically observed rise from USD 7,420.5 million (2023) to USD 8,424.42 million (2025), our forecast anticipates continued growth to USD 8,976.22 million in 2026 and a horizon value of USD 13,134.49 million by 2032. This trajectory reflects sustained clinical need, improving access to supportive care, and cross-cutting policy shifts that influence both opioid and non-opioid treatment adoption.
Market structure and competitive posture
The market shows a concentrated competitive structure: the top three firms account for a material portion of market sales, with the top five expanding that share further. This concentration creates both barriers and opportunities: established biopharma and device players retain strong commercial channels and payer relationships, while specialist innovators are carving out high-margin niches through differentiated mechanisms of action and interventional platforms.
-
Incumbent biopharma — Large pharmaceutical companies continue to dominate established opioid portfolios and branded analgesics. Their strengths include deep payer engagement, global distribution, and scale in clinical development that can be leveraged for adjunctive or supportive indications.
-
Specialist innovators — Small to mid-sized developers and device companies are advancing targeted interventional solutions and non-opioid pharmacotherapies. Their value lies in clinical differentiation and, increasingly, in new reimbursement categories that recognize device-enabled and biologic modalities.
Competitive highlights (selected)
-
Pfizer Inc. (New York, USA) remains a dominant supplier of opioid analgesics and continues to be central to access strategies where opioids remain standard of care for advanced cancer pain.
-
Johnson & Johnson (Janssen) (New Brunswick, USA) continues commercialization of long-acting transdermal opioids for chronic cancer pain, maintaining provider relationships in oncology and palliative networks.
-
Teva Pharmaceutical Industries Ltd. (Tel Aviv, Israel) sustains broad generics coverage that shapes price dynamics and payer negotiation leverage across markets.
-
Mundipharma (Cambridge, UK), Eli Lilly (Indianapolis, USA), Novartis (Basel, Switzerland), and AstraZeneca (Cambridge, UK) play strategic roles by integrating analgesic therapies into broader oncology and supportive-care portfolios.
-
Smaller innovators such as WEX Pharmaceuticals (Vancouver, Canada), Tetra Bio-Pharma (Canada), and Autonomix Medical (USA) are notable for pioneering non-traditional modalities — from tetrodotoxin-based injectables and cannabinoid investigational therapies to transvascular radiofrequency ablation platforms — that are shifting clinical practice for specific, high-unmet-need cohorts.
Recent clinical and commercial developments shaping 2026 tactics
-
Autonomix Medical: clinical data and trial expansion. Autonomix expanded its proof-of-concept program in 2025 and presented long-term clinical data in 2026 on a transvascular RF ablation approach for pancreatic cancer pain. These indicators suggest a maturing interventional niche with potential to broaden beyond single-cancer indications — a key signal for investors and acquirers assessing the interventional portfolio opportunity.
-
WEX Pharmaceuticals / Dogwood Therapeutics: positive interim efficacy. Collaboration results showing improved relief in chemotherapy-induced neuropathic pain mark a critical inflection for small-molecule or biologic candidates that target neuropathic pathways, potentially unlocking new ambulatory indications.
-
Device reimbursement evolution. CMS’s recognition of certain electronic infusion pumps for separate Medicare payment under recent regulatory changes (effective January 1, 2026) creates commercial incentives for providers to adopt device-enabled delivery systems and for suppliers to innovate around value-based delivery models.
Policy and payer dynamics — implications for 2026 plans
Policy and reimbursement developments over 2024–2026 are re-defining the economics of pain management. Key dynamics include:
-
Regulatory acceleration of non-opioid programs: recent guidance from the U.S. FDA to expedite development of safe, effective non-opioid analgesics reduces time-to-market uncertainty for novel therapeutics, reshaping R&D prioritization.
-
Opioid stewardship frameworks: authoritative prescribing guidelines continue to delineate cancer and palliative exceptions, influencing prescriber behavior but not eliminating demand for opioids in advanced disease contexts.
-
Reimbursement carve-outs: new payment rules for qualifying non-opioid devices and supplies — including temporary statutory provisions tied to specific acts — create near-term windows to demonstrate economic value and scale adoption before sunset provisions or subsequent rulemaking.
-
Controlled-substance quotas: recent adjustments to production quotas for key opioids have ripple effects on supply security, pricing, and substitution strategies across markets.
What’s in the PW Consulting report (practical deliverables)
The report is intentionally practice-focused to support immediate strategic decision-making in 2026. It includes:
-
Topline market sizing and a transparent forecasting model (2026–2032) built on demand drivers, price trends, and clinical adoption curves.
-
Scenario-based strategic roadmaps that quantify the impact of alternative regulatory and reimbursement outcomes on portfolio economics.
-
Competitive benchmarking with capability maps, partnership fit matrices, and M&A scorecards tailored to both incumbent and challenger archetypes.
-
Go-to-market playbooks for device-enabled solutions, specialty pharmacotherapies, and integrated service models aimed at oncology centers and palliative care networks.
-
Operational checklists for clinical development, payer evidence generation, and cross-functional commercialization to accelerate adoption in the 2026 policy environment.
Note: per the “trailer” approach of this release, we have deliberately withheld granular regional and modality-level revenue splits and payor-specific pricing tables from this public preview. These detailed tables, along with our proprietary unit economics model and market maps, are available through the full report package.
Strategic implications and recommended 2026 actions
-
Reassess portfolio sequencing: Prioritize assets that benefit from new reimbursement codes and those least exposed to quota-constrained opioid supplies. Consider fast-follower investments in device-enabled delivery and non-opioid pharmacologies where regulatory pathways have become clearer.
-
Accelerate strategic partnerships: For innovators, 2026 is an opportune window to transact with incumbents seeking differentiated assets to complement large analgesic franchises or to shore up supply chains.
-
Invest in payer evidence now: Rapidly develop value dossiers that capture cost offsets enabled by non-opioid therapies and device interventions — early payer engagement will materially shorten coverage timelines.
-
Scenario-proof the supply chain: Implement contingency plans for controlled-substance sourcing and identify alternative delivery or therapeutic options that mitigate quota-related disruption risk.
-
Operationalize real-world evidence capabilities: Deploy pragmatic trials and registries focused on quality-of-life endpoints and health-economic outcomes to accelerate reimbursement and guideline inclusion.
Final note — how PW Consulting can help
For executives designing 2026 strategies, this report provides both the evidence base and pragmatic playbooks needed to make confident resource allocation decisions. If your team is evaluating portfolio pivots, partnership targets, or payer-engagement strategies in advanced cancer pain management, PW Consulting’s full dataset and scenario models will help convert strategic intent into measurable outcomes.
To access the complete report — including the proprietary segmentation datasets, granular regional and modality breakdowns, CR3/CR5 concentration analytics, and financial models — please visit our report page. The full package contains the operational templates and excel models required to integrate these insights directly into your 2026 planning cycle.
For detailed analysis of this topic, please visit the official page: Worldwide Advanced Cancer Pain Management Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com