

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Construction Use Hydroxypropyl Starch Ether Market Poised to Expand at 5.24% CAGR Over 2026–2032

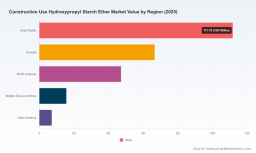
Worldwide Construction Use Hydroxypropyl Starch Ether Market — Strategic Intelligence for 2026 Decision‑Makers
PW Consulting today releases an executive briefing drawn from our new market research: Worldwide Construction Use Hydroxypropyl Starch Ether (HPS) Market, base year 2025. Built on a historical series (2020–2025) and a forward-looking forecast window (2026–2032), the study quantifies the market’s trajectory and delivers an operational playbook designed to inform procurement, product development, and M&A decisions in 2026.
Worldwide Construction Use Hydroxypropyl Starch Ether Market
Headline takeaways
- The global HPS market expanded from USD 192.3 Million in 2020 to USD 248.6 Million in 2025 (base year), reflecting recovery and product penetration during the period.
- Under our central forecast, the market is projected to grow at a compound annual growth rate (CAGR) of 5.24% for the forecast period 2026–2032, reaching roughly USD 355.4 Million by 2032.
- Market concentration remains moderate: the top three suppliers account for 38.5% of the market, while the top five account for 52.4%, indicating room for strategic consolidation and value capture by focused players.
Why this report matters in 2026
- Strategic procurement: Raw material volatility and regional supply imbalances are reshaping supplier selection criteria. Our analysis helps procurement teams build defensible dual‑sourcing and hedging strategies.
- Product roadmap decisions: Manufacturers of dry‑mix mortars, tile adhesives and wall plasters can prioritize formulation upgrades and premium SKUs based on quantified market sizing and performance economics.
- M&A and inorganic growth: With mid‑level concentration and clear technical differentiation among vendors, 2026 remains an active window for bolt‑on acquisitions and capacity plays—our report highlights target archetypes and valuation levers.
What the report delivers — an operationally focused dossier
- Demand model by year (2020–2032) and scenario analysis that stress‑tests volume and price assumptions against construction cycles and commodity shocks.
- Supply mapping and competitive benchmarking across manufacturing scale, product variants, technical service capabilities and distribution reach.
- Raw material cost pass‑through models and sensitivity matrices to quantify margin exposure to propylene oxide and feedstock fluctuations.
- Commercial playbooks: procurement checklists, go‑to‑market approaches for formulators, and an M&A playbook with integration risk checklists.
- Regulatory and sustainability landscape affecting starch sourcing, product labelling and safe‑use guidelines in key construction jurisdictions.
Market dynamics shaping decisions in 2026
Three dynamics dominate near‑term strategy for HPS stakeholders: demand composition driven by construction activity and dry‑mix adoption; raw material cost volatility; and product innovation that changes formulate economics.
Worldwide Construction Use Hydroxypropyl Starch Ether Market
- Construction demand & product mix: Growth in repair, renovation, and urbanization underpins steady demand for dry mortars that rely on HPS for water retention, rheology control and anti‑sag performance. Our demand model reflects both cyclical and structural levers—beneath the headline CAGR, there are application‑level pulses that inform SKU prioritization.
- Raw material volatility: The etherification process for HPS is sensitive to propylene oxide availability and price. Market references show Northeast Asia spot levels at approximately USD 1.14/kg in December 2025. By February 2026, reported levels stood at roughly USD 1,138/MT in China and USD 1,236/MT in the USA. Chinese domestic benchmark prices spiked in March 2026—one report cited 11,466.67 RMB/ton with a rapid month‑on‑month increase of over 40%—illustrating how feedstock tightness can compress margins or force price repricing downstream.
- Innovation & substitution pressure: HPS is often applied in combination with cellulose ethers and other additives. Innovations in starch modification, new grade introductions and blends with cellulose derivatives are changing performance profiles and unit economics. The report maps which product attributes command premium pricing and why technical service (on‑site trials, dosing guidance) is increasingly a differentiator.
Competitive landscape — synthesis and implications
Our competitive review profiles a diversified set of suppliers with differing strategic postures: specialist starch‑ether producers, integrated chemical players, and high‑service partners focused on building materials. While many leading vendors are regionally focused manufacturers with deep formulation expertise for cement and gypsum systems, trends point to a bifurcation between scale players chasing cost leadership and nimble specialists capturing premium niches.
Worldwide Construction Use Hydroxypropyl Starch Ether Market
- Scale and specialization: Established manufacturers offer broad HPS portfolios tailored to tile adhesives, wall putty and dry mortars, often pairing HPS with cellulose ethers to optimize rheology and workability. These firms leverage technical service and local distribution to defend customer relationships.
- Technical differentiation: Several firms emphasize product attributes such as water retention, sag resistance and compatibility with polymer modifiers. This technical nuance is where smaller suppliers can protect margin against price competition from larger producers.
- Consolidation potential: With the top five controlling just over half of the market, strategic acquisitions—targeting either capacity or application expertise—are likely to accelerate as companies seek to unlock scale benefits and broaden portfolios.
- Supply chain risk: Many manufacturers are exposed to upstream propylene oxide swings and regional feedstock constraints. Companies with forward integration, alternative etherification routes, or secured feedstock contracts will enjoy a competitive edge in 2026.
Practical implications for 2026 strategy
Across our client work, the following priorities emerge as highest impact for the coming 12–18 months:
- For manufacturers: Implement dynamic pricing clauses linked to propylene oxide indices, accelerate development of high‑value grades, and build technical support offerings that tie product performance to reduced installation cost for end customers.
- For raw material suppliers: Offer transparent indexation solutions and secure-offtake partnerships with HPS producers. Investments in feedstock diversification and capacity flexibility reduce downstream disruption risk.
- For mortar formulators and OEMs: Reassess formulations to balance material cost with installation labor savings—especially where HPS enables thinner bed technologies or faster set profiles that reduce total cost of ownership.
- For private equity and strategic investors: Target specialist HPS players with strong formulation IP, or regional players with potential for bolt‑on expansion to achieve scale and margin improvement.
Operational playbook included in the full report
We designed the deliverable to be actionable. Highlights of the operational toolkit included with the full report:
- Price sensitivity dashboards that quantify EBITDA impact across plausible propylene oxide scenarios.
- Supplier due‑diligence templates (quality, regulatory compliance, capacity, logistics resilience).
- Go‑to‑market blueprints for launching premium HPS grades—covering sampling programs, co‑development agreements and ROI cases for formulators.
- M&A screening matrix with synergy levers, integration risk factors and valuation range heuristics tailored to HPS targets.
How to use this intelligence
This briefing is a strategic preview designed to inform 2026 planning cycles. It surfaces the macro trajectory, competitive posture and tactical levers that matter—while preserving the granular segmentation, application‑level volumes and company‑by‑company data for the full report. For procurement teams, R&D leads, commercial directors and investment committees, the full dataset provides the calibrated inputs necessary to finalize budgets, supplier contracts and acquisition target lists.
To access the complete research package—containing the full demand model, application and regional breakdowns, individual company profiles and downloadable spreadsheets—please visit the PW Consulting report page or contact your PW Consulting account director for a secure data preview and tailored advisory engagement.
Closing perspective
HPS sits at the intersection of commodity dynamics and technical differentiation. The next 18 months will reward companies that marry disciplined feedstock risk management with targeted product innovation and a service‑led commercial approach. PW Consulting’s Worldwide Construction Use Hydroxypropyl Starch Ether Market report is built to be an operational tool for those decisions—delivering numbers, scenarios and pragmatic playbooks that translate insight into action.
For detailed analysis of this topic, please visit the official page: Worldwide Construction Use Hydroxypropyl Starch Ether Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com