

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Inflatable Above‑Ground Pool Market Set to Expand at a 6.18% CAGR in the 2026–2032 Forecast, Reveals New Growth Opportunities

Worldwide Inflatable Above Ground Pool Market: Strategic Imperatives for 2026
Executive Preview — PW Consulting
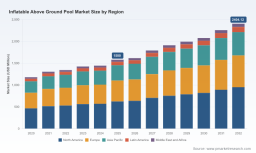
The global inflatable above ground pool market has evolved from a seasonal consumer niche into a strategically relevant segment for manufacturers, retailers, and investors. Our new market study — base year 2025, forecast period 2026–2032 — shows that the industry grew from approximately USD 1,180 Million in 2020 to USD 1,580 Million in 2025, and, at an expected compound annual growth rate (CAGR) of 6.18%, is projected to expand materially through 2032. These headline figures position the market as a medium-growth, capital-efficient opportunity for companies that can rapidly adapt to new safety regulations, raw-material volatility, and shifting consumer channels in 2026.
Worldwide Inflatable Above Ground Pool Market
Why this report matters for 2026 decision‑makers
-
Timing and scale: 2026 is the first full planning year after a series of industry shocks — notably high‑profile product recalls and material market shifts — making rapid, evidence‑based strategy essential for capital allocation, product roadmap prioritization, and channel investments.
Worldwide Inflatable Above Ground Pool Market -
Risk and reputation: Product safety incidents have moved from isolated operational headaches to enterprise-level brand and legal risks. Executives who can operationalize safety into design, supplier selection, and go‑to‑market processes will preserve market share and avoid costly disruptions.
Worldwide Inflatable Above Ground Pool Market -
Margin and sourcing dynamics: PVC and related resin markets remain volatile. Our scenario work shows procurement strategies enacted in 2026 — hedging, supplier diversification, nearshoring, or design substitution to alternative polymers — will distinctly separate resilient players from those subject to margin compression.
-
Channel transformation: E‑commerce and omnichannel execution continue to shift the economics of seasonal leisure goods. 2026 is a pivotal year to reallocate marketing and logistics spend toward channels with demonstrable return on spend and post‑sale support capabilities.
Recent industry developments shaping 2026
-
Product safety and recall dynamics: A mid‑2025 recall affecting several major manufacturers highlighted systemic product‑safety exposures in models using particular external compression features. This event — and the regulator engagement that followed — has amplified compliance expectations globally and accelerated demand for third‑party testing and design change management.
-
Raw material environment: Late‑2025 downward movement in PVC resin pricing created near‑term buyer leverage, but the underlying supply‑demand dislocation remains. Volatility across PVC, polyethylene, and steel persists and must be modeled into 2026 sourcing and pricing strategies.
-
Manufacturer responses: Several producers announced catalog releases, capacity ramps, and expanded OEM/ODM offerings entering 2026 — underscoring an industry preparing to capitalize on both backyard leisure demand and rising adult/premium segments.
What PW Consulting’s report delivers — practical, actionable intelligence
-
A rigorously sourced market size and forecast model (2020–2032) with downloadable Excel scenarios and sensitivity analyses tied to price, raw material, and regulatory variables — enabling CFOs and commercial leads to stress‑test FY26 budgets.
-
Operational playbooks for product safety lifecycle management, covering design checkpoints, independent testing protocols, recall preparedness, and consumer communications — intended for product and legal teams.
-
Supply‑chain and procurement tools, including supplier‑risk heat maps, cost‑to‑source models, and recommended hedging approaches to stabilize margins in volatile resin markets.
-
Channel and commercial strategies that map profitability across direct e‑commerce, mass retail, and specialty distribution — with playbooks for assortment, pricing, promotional cadence, and post‑sale service economics.
-
Competitive intelligence dossiers on leading participants, M&A opportunity screening, and an M&A valuation framework tailored to seasonality, inventory risk, and recall liabilities.
-
A regulatory and compliance checklist aligned to key jurisdictions and standards, including applicable ASTM/CPSIA considerations — enabling product teams and compliance officers to operationalize legal requirements into release gates.
Note: This press overview intentionally omits the detailed segmentation tables and region/application breakdowns contained in the full report. These granular datasets are provided to licensed report purchasers to underpin commercial models and investment memoranda.
Competitive landscape — positioning and strategic implications
The market sits in a moderately concentrated competitive structure: the three‑player concentration (CR3) and five‑player concentration (CR5) metrics show meaningful leadership by established brands but leave room for agile entrants and consolidation plays. Our qualitative assessment of leading participants highlights the following strategic archetypes.
-
Global brand incumbents with broad retail reach — firms with household recognition and deep mass‑retail distribution continue to leverage scale in manufacturing and logistics. Their strengths are marketing reach and seasonal shelf presence; their vulnerability lies in complexity when executing rapid design changes or recalls.
-
Vertically integrated manufacturers — companies that retain control over manufacturing and some raw material inputs can protect margins during input volatility and offer competitive OEM pricing. Their strategic choice is balancing scale with nimbleness in product development.
-
Niche premium and design‑led brands — smaller players pursuing adult, lifestyle, or design‑first pools generate higher ASPs and better customer loyalty but must scale distribution and service to maintain growth.
-
OEM/ODM specialists — suppliers offering customizable solutions to retailers and private‑label partners present an attractive partner model for entrants wanting speed to market without heavy capex.
Our report includes tactical profiles of the core players, their geographies of emphasis, value propositions, and near‑term strategic moves — all geared to support competitor benchmarking and partnership screening.
Key strategic priorities for 2026 (what to do next)
-
Make safety a commercial differentiator: convert compliance investments into customer trust through transparent testing, extended warranties for affected models, and proactive consumer education.
-
Rework procurement and product bills of materials to reduce single‑supplier exposure to PVC and other volatile inputs; evaluate polymer alternatives and design changes that reduce material intensity without compromising durability.
-
Rebalance portfolio cadence: prioritize SKUs that generate stable margin outside peak season (premium, durable, adult-oriented models) while streamlining low‑margin, high‑inventory items.
-
Operationalize recall resilience: implement a rapid traceability stack, recall simulation exercises, and a customer remediation budget embedded in annual planning.
-
Execute channel experiments with rigorous KPI governance: test marketplace promotions, subscription‑based replacement parts, and service bundles that extend lifecycle revenue.
-
Scan for inorganic opportunities: acquisition targets should be screened not only for revenue but for manufacturing footprint, testing capabilities, and intellectual property that reduce product‑safety exposure.
Scenario framing for boardrooms
-
Base Case (aligned with our headline CAGR): steady growth, gradual premiumization, and moderate margin pressure from raw‑material swings. Recommended focus: efficiency and safety investments to lock in share.
-
Upside Case: accelerated adult/premium adoption and favorable resin pricing deliver above‑trend growth. Recommended focus: scale premium lines, increase direct‑to‑consumer investments, and opportunistic capacity expansion.
-
Downside Case: regulatory shocks or another large recall depress demand and force inventory write‑downs. Recommended focus: liquidity preservation, deferred capex, and acquisition of distressed assets with long‑term upside.
Next step — how to use this research in Q1–Q2 2026
Corporate leaders should use the report to finalize FY26 capital plans, set procurement hedges, and define safety/design priorities that will be embedded into product development roadmaps. Commercial teams can leverage our channel playbooks and pricing sensitivity models to optimize promotional calendars and SKU rationalization ahead of the 2026 selling season.
Accessing the full intelligence
This release is a strategic preview intended to orient decision‑makers. The full PW Consulting Worldwide Inflatable Above Ground Pool Market report contains the complete set of segmentation tables, regional and application breakdowns, company financial matrices, and the downloadable forecast model essential for investment committees and operating plans. Licensed purchasers receive the dataset and a one‑hour briefing with our lead analyst to translate the findings into actionable initiatives for 2026.
PW Consulting — Senior Strategic Advisor and Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Worldwide Inflatable Above Ground Pool Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com