

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Tunnel Detection System Market to Expand at 8.04% CAGR Through 2032

Worldwide Tunnel Detection System Market: Strategic Briefing for 2026 Decision-Makers
PW Consulting today releases a forward-looking industry briefing derived from our full market research report on the Worldwide Tunnel Detection System market. As security threats evolve and infrastructure protection becomes mission-critical, this briefing highlights the strategic implications that enterprise leaders, procurement officers, and defense & homeland-security program managers must consider in 2026. It showcases the research depth behind our findings while deliberately reserving segment-level tabulations and proprietary modeling—available in the full report—to encourage direct engagement with our sources.
Worldwide Tunnel Detection System Market
Market Trajectory at a Glance
The tunnel detection market has entered a sustained expansion phase. Our topline model shows growth from USD 1,980.4 Million in 2020 to USD 2,840.5 Million in the report’s base year (2025). We project an immediate uplift to approximately USD 3,152.4 Million in 2026 and a continued climb to USD 4,868.12 Million by 2032, underpinned by a compound annual growth rate (CAGR) of 8.04% across the forecast period. These macro dynamics reflect a confluence of policy funding, technology maturation, and escalating operational requirements in border, critical infrastructure and asset protection contexts.
Worldwide Tunnel Detection System Market
Why This Matters for 2026 Strategy
- Capital planning and procurement timing: The step-change between 2025 and 2026 indicated in our model signals an inflection point for procurement cycles. Organizations planning major rollouts or CapEx commitments in 2026 should align tender schedules to capture early-adopter advantages while accounting for vendor delivery lead times.
- Technology portfolio choices: Detection architectures are diversifying (surface-based sensors, buried seismic arrays, fiber-based sensing, and ground-penetrating radar among others). Selection decisions should be driven by mission profile, false-alarm tolerance, coverage cadence, and integration with existing VMS and command centers. Our full report provides a decision matrix to map operational requirements to technology families and performance trade-offs.
- Supply chain and component risk: Core components—specialized geophones, accelerometers, fiber-optic sensing elements, and high-fidelity acoustic sensors—are subject to lead-time and qualification constraints. Buyers must incorporate component sourcing clauses and dual-sourcing strategies into contracts to mitigate delivery and lifecycle risks.
- Regulatory and funding tailwinds: Recent public allocations directed toward persistent surveillance and cross-border detection capabilities are accelerating adoption. Programs which can align their proposals with public funding priorities will materially improve project economics and accelerate deployment timelines.
Report Deliverables: Practical Tools for Executives
Our full report is structured to be a practical playbook, not just an academic exercise. Key operational deliverables include:
Worldwide Tunnel Detection System Market
- Deployment playbooks for pilot, phased, and enterprise-scale rollouts, with checklists for site engineering, environmental testing, and systems integration;
- Procurement templates and ROI calculators that quantify total cost of ownership, expected detection coverage, and lifecycle maintenance for competing architectures;
- A vendor evaluation framework that scores suppliers across performance metrics, verification protocols, integration effort, and sustainment footprint;
- Scenario-based decision guides for border security, transport tunnels, and critical infrastructure protections—including tailored rules of engagement and escalation ladders;
- Regulatory watch and funding tracker to identify short- and medium-term grant windows, program priorities, and compliance obligations;
- Structured scorecards and negotiation playbooks for risk-sharing contracts and performance-based service agreements.
Competitive Landscape: Capabilities, Differentiation, and Tactical Moves
The tunnel detection ecosystem blends defense primes, specialized sensor companies, and scientific instrumentation vendors. Market concentration is moderate: the top three firms account for roughly 32.4% of market revenues, while the top five together approach approximately 48.8%. That mix fosters both competition and opportunity for partnerships, integrations, and targeted consolidation.
- SensoGuard Seismic Solutions (Israel) — SensoGuard’s product set focuses on buried seismic arrays and wireless solutions marketed for perimeter and correctional environments, emphasizing AI-enabled classification to reduce false positives and seamless VMS integration. Recent catalog updates in April 2026 demonstrate a move to productize AI-assisted verification modules aimed at faster field adoption.
- Geospace Technologies (United States) — Geospace offers multi-sensor SADAR systems combining seismic and acoustic arrays for 3D localization of subterranean activity. Their strengths lie in dense sensor networks and real-time localization algorithms suited for complex terrains; they are frequently chosen where high-resolution spatial localization is required.
- Elbit Systems (Israel) — With a portfolio that blends acoustic, vibration and AI analytics, Elbit has leveraged its homeland and defense track record to scale to larger perimeter and border surveillance programs. Notably, Elbit’s American subsidiary executed further deployments in late 2025, reinforcing their position in government procurement channels.
- US Radar Inc. (United States) — US Radar brings deep specialization in ground-penetrating radar (GPR), with capabilities extending to deep-penetration imaging. Their systems are often selected for geophysical surveys and scenarios where subsurface characterization and imaging fidelity are prioritized.
- Lockheed Martin (United States) — As an integrator and systems house, Lockheed combines gravity gradiometry, GPR, and advanced signal-processing to support large-scale defense programs and airborne/surface-based surveying. Their historical program experience and scale give them an advantage in enterprise-level, government-funded contracts.
Each of these players addresses different risk profiles and operational needs: some prioritize low false-alarm rates and ease of VMS integration, while others target raw detection depth or enterprise program scale. The competitive dynamic favors vendors that combine sensor reliability, algorithmic transparency, and integration partners for command-and-control systems.
Industry Signals, Policy Drivers and Component Considerations
- Policy and funding: Public funding commitments aimed at persistent surveillance and tunnel detection are material. For example, a 2025 allocation focused on expanding ground-penetrating radar and acoustic sensor deployments has catalyzed program-level procurements and accelerated pilot-to-program transitions.
- Component constraints: Performance of seismic and acoustic solutions rests on a small set of specialized hardware—geophones, accelerometers, fiber-optic sensing elements, and precision ADCs. These items have long qualification cycles; procurement strategies must therefore address supplier qualification and lifecycle obsolescence.
- Operational noise and discrimination: The core technical challenge remains distinguishing covert tunneling from benign surface and subsurface noise (construction activity, natural seismicity, and heavy traffic). Advances in AI-assisted verification and multi-modal sensor fusion are improving discrimination, but algorithm explainability and field validation remain requirements for mission-critical acceptance.
Practical Recommendations for 2026 Executives
- Adopt phased risk-reduction pilots: Run small-scale, instrumented pilots to calibrate algorithm thresholds and integration with command ecosystems before committing to rollouts. Use pilots to validate detection-to-action timelines.
- Prioritize interoperability: Specify open integration interfaces (APIs, standardized alerts, and map overlays) in RFPs to avoid vendor lock-in and ease future capability layering (e.g., LIDAR, aerial ISR).
- Lock in critical components: Secure long-lead items via framework agreements and include test/acceptance criteria tied to environmental performance and false-alarm metrics.
- Incentivize sustainment: Favor procurement models that include performance-based maintenance and health monitoring—this reduces lifecycle cost and keeps system sensitivity calibrated over time.
- Consider strategic partnerships: Defense primes and sensor specialists each bring complementary strengths; evaluate JVs or teaming agreements where scale and rapid fielding are priorities.
How PW Consulting’s Full Report Supports Your 2026 Decisions
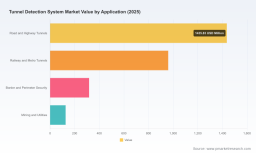
Our complete Worldwide Tunnel Detection System Market report supplies the actionable, data-driven materials needed to execute the recommendations above: granular supplier scorecards, procurement templates, risk-adjusted financial models, and validated deployment timelines. It also contains the full segmentation tables, regional and application breakdowns, and detailed forecasts underpinning our topline numbers. In this briefing we intentionally omit those segment-level figures to preserve the utility of the full dataset and to direct decision-makers to the source material that will enable contract-level planning.
For organizations preparing for procurement cycles, technology refreshes, or policy-aligned funding opportunities in 2026, the full report functions as both an evidence base and an operational playbook. If your program requires bespoke scenario analysis, PW Consulting also offers tailored workshops and modeling support to convert market insights into procurement-ready strategies.
Next Steps
- Download the executive summary and schedule a briefing with PW Consulting to review the complete segment-level forecasts and supplier matrices.
- Request a tailored workshop to map your operational requirements against vendor capabilities and to develop a defensible procurement timeline for 2026.
- Engage with our analysts for a confidential supplier risk assessment or an ROI validation for planned investments.
PW Consulting’s research provides the strategic context and tactical instruments organizations need to navigate an increasingly complex tunnel detection market. Our topline projections—from USD 1,980.4 Million in 2020 to a projected USD 4,868.12 Million by 2032 at an 8.04% CAGR—are the basis for practical, actionable plans that reduce deployment risk and accelerate time-to-effectiveness. Access the full report to unlock the detailed segmentation, vendor datasets, and procurement tools that will guide your 2026 decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Tunnel Detection System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com