

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Amino Acid-Based Formula Market to Grow from USD 1,638.7 Million in 2025 to USD 2,790.28 Million by 2032 at a 7.9% CAGR

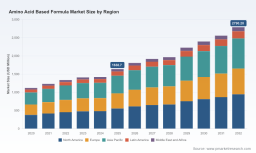
Worldwide Amino Acid Based Formula Market — Strategic Preview for 2026 Decisions
PW Consulting today releases an executive preview of our latest Worldwide Amino Acid Based Formula Market study (base year: 2025; forecast period: 2026–2032). The amino acid based formula category — a medically indicated subset of infant and pediatric nutrition — has demonstrated resilient growth through the pandemic recovery and is entering a phase of structural expansion. Our model pegs the global market at approximately USD 1,638.7 Million in 2025, rising at a compound annual growth rate (CAGR) of 7.9% through the forecast window. By 2032 the category approaches multi‑billion dollar scale under the base-case projection, underscoring why 2026 is a pivotal year for commercial, manufacturing and regulatory strategy formation.
Worldwide Amino Acid Based Formula Market
What this report delivers — practical, decision‑grade intelligence
- Forward-looking revenue model (USD Million) with scenario alternatives calibrated to regulatory, reimbursement and raw‑material shocks — enabling board‑level financial planning and sensitivity analysis.
- Competitive landscape with differentiated canvases for market share drivers, route‑to‑market maps, and product life‑cycle positioning tailored to amino acid‑based medical nutrition.
- Regulatory heat map across principal markets that translates classification, labeling and exempt‑formula frameworks into concrete launch timelines and risk buffers.
- Reimbursement and formulary playbook detailing payor engagement strategies, coverage triggers and state‑level nuances for prioritizing market access investments.
- Manufacturing and supply‑chain playbook, including cost‑to‑serve modeling for free amino acid sourcing, recommended buffer inventories, and candidate CDMO profiles for scale or rapid response.
- Go‑to‑market and clinical evidence templates: protocol outlines for real‑world evidence (RWE), health economic dossiers and physician engagement to shorten adoption cycles in specialty channels.
Market dynamics shaping 2026 strategic choices
Three structural dynamics underpin the category expansion and should be front and center for 2026 plans:
Worldwide Amino Acid Based Formula Market
- Clinical adoption anchored in medical necessity. Amino acid formulas remain the standard of care for infants and children with severe cow’s milk protein allergy (CMPA), multiple food allergies, or malabsorptive conditions. Clinical guidelines and payer pathways materially influence uptake — where coverage and clear prescription protocols exist, utilization accelerates.
- Cost structure and pricing pressure. These formulas rely on free amino acids as the core protein source rather than intact or hydrolyzed proteins. That upstream ingredient profile drives higher unit production costs and elevated retail prices, creating margin tension and a premium‑pricing opportunity that is sensitive to commodity movements and scale economics.
- Concentration and competitive barriers. The category exhibits a high degree of concentration among established specialty nutrition manufacturers, creating both advantages in clinical trust and challenges for new entrants. Market concentration implies high go‑to‑market friction but also signals opportunities for niche innovation and service differentiation (e.g., extended‑age formulations, ingredient enhancements, or tolerance‑focused clinical programs).
Competitive snapshot: what leading players signal to the market
The competitive landscape is dominated by established global nutrition and medical‑food companies. Each incumbent brings different strengths that shape opportunity windows for competitors and partners:
Worldwide Amino Acid Based Formula Market
- Abbott Laboratories (EleCare): Strong clinical adoption and brand trust in specialty pediatric channels, recently expanded into older‑child formulations with product innovations that broaden total addressable population beyond infancy. New product introductions signal strategic focus on lifecycle expansion and nutrient fortification targeted at neurodevelopmental claims.
- Mead Johnson Nutrition (Reckitt) — PurAmino: Positioned with heritage in pediatric nutrition and distribution muscle across hospital formularies and outpatient specialty pharmacies. Their portfolio emphasizes DHA/ARA inclusion and clinician familiarity, making them a durable competitor in medically managed segments.
- Nestlé Health Science — Alfamino: Offers broad geographic reach and scale but recent regulatory events in key markets have introduced heightened oversight and short‑term supply disruptions, illustrating reputational and operational risks even for large incumbents.
- Nutricia (Danone) — Neocate: A clinically entrenched brand with deep relationships in tertiary care centers and a strong product family spanning infant to older‑child needs. Their focus on clinical evidence and specialty channel access creates barriers to switching for prescribers.
Recent company‑level developments — product launches and product recalls — act as leading indicators for two important themes in 2026 planning: (1) product lifecycle extension (age and nutritional add‑ons) will be a primary route to grow share, and (2) operational resilience and quality governance will separate winners from laggards as regulators increase scrutiny.
Regulatory and reimbursement levers — practical implications
Regulatory classification matters more than ever. In key markets, amino acid formulas are managed as exempt or specialty products intended for use under medical supervision. This status creates a dual opportunity: clarity of indication supports premium positioning and physician prescribing, while the exempt/specialty status imposes strict manufacturing and labeling obligations. In the U.S., several amino acid formulas appear on the FDA’s exempt list and are subject to targeted oversight — market entrants must design dossiers and lot‑release processes to align with these expectations before launch.
On reimbursement, public programs and private payors are pivotal. In many jurisdictions, medically necessary amino acid‑based formulas may be eligible for coverage under public nutrition programs or hospital formularies, with state and insurer variability. 2026 commercial strategy must therefore prioritize payor evidence packages and state‑level engagement to unlock access and limit out‑of‑pocket barriers for patients.
Operational imperatives for 2026
- Strengthen quality systems and batch traceability. Recent recalls in 2026 highlight how a single quality event can trigger market access reversals and payer scrutiny; 2026 investment in enhanced QA/QC, supplier audits and serialization will be insurance against regulatory shocks.
- Secure amino‑acid supply and diversify vendors. Given elevated raw material cost and concentration, risk mitigation through multi‑sourcing, forward contracts and strategic inventory is non‑negotiable for manufacturers and CDMOs.
- Design flexible manufacturing footprints. A two‑tier approach — core volumes in low‑cost, high‑quality plants and rapid‑response regional lines for emergency supply — reduces time‑to‑supply risk in the event of recalls or logistic interruptions.
- Prioritize evidence generation that matters to payors and prescribers. RWE, growth and tolerance endpoints, and health economic models that quantify cost offsets versus alternative clinical pathways unlock formulary inclusion and justify reimbursement.
Scenario planning — three actionable paths for 2026
- Base case (aligned with 7.9% CAGR): Gradual adoption continues, reimbursement improves incrementally, incumbents defend share via product extensions. Recommended actions: accelerate medical affairs engagement; secure supply; align pricing with value dossiers.
- Upside case: Policy shifts and stronger public program coverage drive faster uptake. Recommended actions: scale manufacturing capacity, prioritize market entries with fast coverage, and deploy aggressive clinician education programs to capture share.
- Downside case: Regulatory events or raw ingredient shortages cause transient contraction. Recommended actions: implement contingency supply plans, activate recall‑ready communication protocols, and seize competitor disruptions with targeted local promotions and supply assurances.
How executives should use this report in 2026
We designed this study to be immediately usable across three horizons:
- 90‑day plays: supplier qualification checklists, quality‑control gap analysis, and priority payor engagement templates.
- 12‑month plans: capacity investment decisions, product roadmap prioritization (e.g., extended‑age SKUs), and commercial launch sequencing tied to reimbursement timelines.
- 3‑year strategy: M&A screening for bolt‑on clinical brands or CDMOs, global supply‑chain reshoring scenarios and R&D pipelines aligned to tolerance and tolerance‑enhancing ingredients.
Why PW Consulting’s perspective matters
Our analysis combines proprietary market modeling with supply‑side interviews across manufacturers, CDMOs and clinical leaders, payer policy scans and real‑world prescribing datasets. The result is not just a point forecast but an operational playbook linking top‑line scenarios to concrete manufacturing, regulatory and commercial actions. For executives assessing investment, M&A, or market entry in 2026, the value lies in the linkage between plausible near‑term disruptions and executable mitigations — not simply in headline growth rates.
Next steps and how to obtain full intelligence
This release is a strategic preview highlighting direction and decision levers. The comprehensive PW Consulting report includes the granular, segment‑level demand models, regional channel breakdowns, product‑form forecasts, and interactive scenario spreadsheets that we intentionally withhold from this preview. Those detailed matrices — including market splits by region, product form and age cohort, plus unit economics and price curves — are available in the full report and interactive dashboard for licensed clients.
For 2026 planning, organizations should prioritize (1) immediate audit of quality and supplier exposures, (2) rapid development of payer value evidence, and (3) scenario‑based capacity planning. PW Consulting stands ready to brief executive teams and tailor the report’s models to enterprise budgets, portfolio ambitions and M&A pipelines.
To request the full report and an executive briefing, please consult PW Consulting’s corporate channels — the preview above maps the strategic terrain; the full deliverable contains the tactical coordinates required for execution.
For detailed analysis of this topic, please visit the official page: Worldwide Amino Acid Based Formula Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com