

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Mechanical Anti‑Corrosion Lubricating Oil Market to Reach USD 3,250 Million in 2025, Projected to Grow at a 5.2% CAGR Through 2032

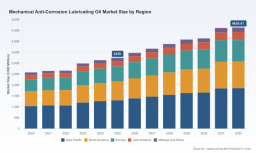
Worldwide Mechanical Anti-Corrosion Lubricating Oil Market — Strategic Imperatives for 2026 (PW Consulting Preview)
Executive summary
PW Consulting’s upcoming Worldwide Mechanical Anti-Corrosion Lubricating Oil Market report synthesizes five years of historic market behavior (2020–2025) and presents an actionable forecast across 2026–2032. The market has expanded from approximately USD 2,580 million in 2020 to an estimated USD 3,250 million in 2025, and is projected to grow at a steady compound annual growth rate of 5.2% over the forecast window. By 2032 the sector is expected to be materially larger than it was at the 2025 base, reflecting recovery in industrial demand, continued investment in corrosion protection across value chains, and the gradual adoption of next‑generation chemistries and services.
Worldwide Mechanical Anti-Corrosion Lubricating Oil Market
Why this preview matters for senior decision-makers in 2026
-
Timing and resource allocation: The market’s steady mid-single‑digit CAGR signals a transition from stabilization into selective expansion — an environment in which capital deployment should prioritize differentiated portfolios and resilient supply chains rather than broad capacity builds.
Worldwide Mechanical Anti-Corrosion Lubricating Oil Market -
Tactical pricing and procurement: Raw material trajectories that softened in late 2025 into early 2026 have created a window to reset procurement strategies and margin targets. Firms that lock favorable input costs into multi-tier contracts and couple them with dynamic pricing can capture immediate margin upside and strengthen customer retention.
Worldwide Mechanical Anti-Corrosion Lubricating Oil Market -
Innovation leverage: The intersection of sustainability expectations and equipment reliability requirements means product innovation (bio‑based blends, high‑performance synthetics, and advanced additive packages) will be a primary driver of premiumization — and of competitive advantage.
-
Consolidation and partnerships: With market concentration moderate (the top three suppliers account for a material share and the top five for a majority of the structured commercial market), 2026 is likely to see targeted M&A, co‑development and channel partnerships rather than broad, headline acquisitions.
Report practicalities — what PW Consulting delivers (selected)
-
Proven market-sizing and forecasts to 2032 with scenario and sensitivity models that let you test price, demand and raw material shocks against revenue and margin outcomes.
-
Supplier benchmarking and capability matrices that evaluate formulation technology, additive stacks, global supply footprint, aftermarket channels and service capabilities.
-
Commercial playbooks for OEM/aftermarket segmentation, go‑to‑market tactics, tender and contract design, and margin optimization across distribution tiers.
-
Procurement and raw material intelligence including drivers of base oil and additive cost cycles, inventory dynamics and risk mitigation strategies.
-
Regulatory and sustainability impact assessment covering biodegradability, VOC restrictions, end‑of‑life considerations and claims substantiation for green product lines.
-
Investment and M&A thesis suite: target screening, valuation sensitivities, and integration blueprints focused on bolt‑ons that accelerate specialty chemistry and channel reach.
Market dynamics that will define 2026 decisions
-
Input-cost volatility but an easing window: After elevated base‑oil cycles earlier in the period, market conditions softened into late 2025 and early 2026, driven by weaker lubricant demand in some end markets and replenished inventories. This has reduced immediate cost pressure for formulators but increases the importance of flexible procurement and hedging frameworks to guard against renewed spikes.
-
Premiumization vs. volume competition: Growth is concentrated in higher‑value synthetics and specialty additive‑intensive formulations that offer longer protection windows, multi‑mode corrosion inhibition, and compatibility with modern surface treatments. Price‑driven volume plays remain viable in mature channels but are increasingly margin‑constrained.
-
Sustainability and disclosure as commercial enablers: Customers and procurement teams are raising the bar for sustainability claims, life‑cycle evidence and supplier transparency. Companies that can combine performance with credible environmental credentials will unlock new procurement pools and justify premium pricing.
-
Service and digitalization: Lubrication is moving from a commodified product sale to a service bundle — condition‑based maintenance, inventory as a service, and data‑backed corrosion risk assessments become differentiators for B2B buyers seeking total cost of ownership reductions.
Competitive landscape — where incumbents and specialists are focusing
The competitive map blends global integrated oil majors, specialty lubricant manufacturers, additive houses and niche corrosion protection companies. Integrated energy firms bring scale in base oils and distribution; specialty players bring formulation expertise and customer intimacy; corrosion‑focused providers bring niche technologies for storage, transporation and OEM protection.
-
Integrated majors (e.g., ExxonMobil, Shell, TotalEnergies): Leverage global supply chains, extensive distribution networks and customer relationships in transportation and heavy industries. Their strategic play is broad coverage — from commodity anti‑rust fluids to higher‑value preventive lubricants — and bundling with other energy/product offerings to defend share.
-
Specialty formulators (e.g., FUCHS Group, Klüber Lubrication): Focus on R&D‑led, application‑specific chemistry and technical service. They excel in working with OEMs on spec development and in delivering performance guarantees that allow higher margin capture.
-
Additive and specialty chemistry providers (e.g., Afton Chemical, Lubrizol, DuPont/MOLYKOTE): Act as critical leverage points for formulators. Their ability to deliver advanced corrosion inhibitors and multifunctional additive packages determines product differentiation and speed to market for next‑generation blends.
-
Niche corrosion players (e.g., ZERUST/EXCOR, Cortec, Daubert): Dominate protection in asset storage, shipment and specific industrial use cases. Their focused value propositions around VpCI/VCI chemistries are attractive targets for partnerships or bolt‑on acquisitions by larger formulators seeking to broaden portfolio depth.
-
MRO and aftermarket brands (e.g., CRC Industries, WD‑40 Company, Jet‑Lube): Capture frequent small‑ticket purchases and brand‑led loyalty among maintenance teams. Their strength is reach and recognition within commercial maintenance workflows.
Actionable strategies for 2026
-
Prioritize product tiering and margin capture: Design a three‑tier portfolio (value, performance, premium‑sustainability) and align pricing to total cost of ownership messaging. For customers with critical uptime requirements, sell service bundles rather than liters.
-
Lock in flexible raw material arrangements: Move from fixed‑term purchase commitments to a blended mix of spot, indexed and hedged contracts. Short‑term base‑oil softness presents an opportunity to secure favorable terms for 2026 while building contingency clauses for upside risk.
-
Invest selectively in bio‑based and low‑VOC formulations: Accelerate qualification programs with strategic OEMs and tier‑1 distributors. Even if adoption ramps slowly, being first‑to‑market with certified solutions pays dividends in procurement cycles that prioritize sustainability.
-
Exploit distribution and aftermarket channels: Strengthen relationships with MRO distributors and inspection/maintenance service providers to convert product sales into recurring service contracts. Consider consignment models to reduce customer procurement friction.
-
Pursue targeted M&A and partnerships: Focus on bolt‑ons that add formulation IP, additive capabilities or niche corrosion protection technologies. Integration playbooks should prioritize rapid commercialization and cross‑sell into existing accounts.
-
Operationalize digital services: Pilot condition‑based lubrication programs and deploy simple IoT‑enabled monitoring for high‑value assets to prove service economics and reduce churn.
Risk matrix — what to watch in 2026
-
Raw material rebound: Although prices eased recently, a supply disruption or stronger-than‑expected rebound in automotive/industrial demand could re‑inflate costs and compress margins for low‑value segments.
-
Regulatory tightening: Emerging restrictions on certain solvents and additives could accelerate reformulation costs and create temporary supply bottlenecks for approved chemistries.
-
Channel disruption: Direct procurement strategies by large OEMs and maintenance integrators could squeeze traditional distributor margins — prompting the need for new commercial models.
-
Reputational risk: Unsupportable sustainability claims or failure to substantiate biodegradability can lead to lost contracts and brand damage; invest in third‑party testing and traceability.
How to use this preview and the full PW Consulting deliverable
This preview is intended to inform 2026 planning conversations — budget allocation, procurement cycles, portfolio roadmaps and M&A screening. The full PW Consulting report contains the granular segmentation, supplier scorecards, a downloadable price‑sensitivity model, and proprietary scenario outputs (including break‑even and NPV analyses for strategic investments). We intentionally withhold detailed regional/application splits and proprietary supplier scores in this public summary; the complete data set and executive slide pack are available through the report portal.
Closing: immediate next steps for executives
-
Run a rapid portfolio review against the three‑tier product framework and identify two SKUs to reposition as “service‑anchored” offerings in H1 2026.
-
Open a disciplined procurement window to capture the current easing in base materials, but include clauses to protect against upside volatility.
-
Engage with one specialty additive partner and one niche corrosion technology provider for joint pilots that can generate validated case studies by Q4 2026.
PW Consulting’s full Worldwide Mechanical Anti‑Corrosion Lubricating Oil Market report is the operational toolset for 2026 — combining validated market sizing, competitive intelligence, risk scenarios and go‑to‑market playbooks that translate market trends into executable actions. For the complete segmentation, supplier scorecards and downloadable models, please visit the report page.
For detailed analysis of this topic, please visit the official page: Worldwide Mechanical Anti-Corrosion Lubricating Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com