

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Digital Printed Cartons Market Poised to Reach USD 7.85 Billion by 2032, Growing at a 15.63% CAGR

Worldwide Digital Printed Cartons Market — Strategic Preview for 2026 Decision-Makers
PW Consulting today releases a strategic preview of our forthcoming Worldwide Digital Printed Cartons Market report (base year 2025). This advisory brief highlights the macro dynamics, competitive implications, and near‑term strategic choices that senior executives, investors, and supply‑chain leaders must address in 2026. The full report contains the granular segmentations, proprietary scenario models, and deal‑level intelligence that underpin the recommendations below — intentionally withheld here to preserve the depth of our paid intelligence.
Worldwide Digital Printed Cartons Market
Market at a Glance: Rapid Growth, Strategic Inflection
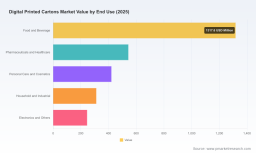
The market for digitally printed folding cartons is entering a sustained growth phase. Our analysis shows the market was valued at USD 2,840.0 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 15.63% through the forecast horizon. By the end of the forecast period, the market is expected to be multiple billions in size, reflecting the accelerating adoption of digital print technologies across packaging converters and brand owners.
Worldwide Digital Printed Cartons Market
Two structural forces drive this trajectory: the economics of customization and the regulatory push toward recyclable, mono‑material constructions. The confluence of these forces is transforming both demand patterns (shorter runs, variable data, personalization) and supply economics (lower plate costs, reduced inventory obsolescence). For 2026, companies that align investment, commercial and sustainability strategies to these forces will capture disproportionate value.
Worldwide Digital Printed Cartons Market
Why This Report Matters for 2026 Decisions
-
Capital allocation under uncertainty — We provide scenario‑based investment cases for digital press adoption versus hybrid roll‑to‑sheet capacity, enabling CFOs to compare payback, utilization and margin outcomes under realistic throughput and substrate cost volatility assumptions.
-
Go‑to‑market playbooks — Brand teams and converters receive tactical frameworks for pricing personalization, structuring short‑run contracts, and integrating digital print capabilities into omnichannel packaging strategies.
-
M&A and partnership intelligence — Our M&A heatmaps and capability gap analysis indicate where acquisitive scale or technology partnerships will best accelerate market entry or extend geographic footprints.
-
Risk and resilience planning — The report models raw material sensitivity, regulatory risk (including emerging EPR schemes) and supply chain shocks to stress‑test sourcing strategies and long‑term contracts.
Report Contents — Practical, Actionable, Confidential
-
Executive summary and 3‑point strategic imperatives for corporate boards and private equity investors.
-
Market sizing and econometric forecast model (2026‑2032) with interactive scenarios to test pricing, substrate inflation and demand shocks.
-
Competitive landscape, including capability mapping, CR3/CR5 concentration analysis, and supplier scorecards for technology vendors and converters.
-
Technology adoption roadmap outlining when inkjet, electrophotographic and hybrid solutions are preferred relative to run length, print fidelity and substrate constraints.
-
Operational playbooks for converters: digital prepress, color management, inventory reduction tactics and labor skills transition plans.
-
Case studies and primary interviews with C‑suite executives, converters, and OEMs demonstrating real‑world outcomes.
Competitive Landscape: Who Matters and Why
The vendor and converter universe is a mix of global packaging champions and digitally native converters. Market concentration data points to a moderately consolidated market: the top three players account for a material share and the top five demonstrate nearly half of industry revenue, indicating scale matters for high‑volume converting and integrated retail contracts. This concentration creates both barriers and opportunities for nimble entrants.
-
Smurfit Westrock (Ireland / United States) — Leverages scale and integrated supply chains to offer short‑run digital cartons alongside traditional folding cartons and corrugated solutions. Their sustainability narrative and retail relationships make them a preferred partner for omnichannel consumer goods brands seeking rapid SKU rotations.
-
Graphic Packaging International (United States) — Strong in high‑volume converting with significant investments in digital printing capability for food and beverage applications. Their positioning benefits from deep relationships with high‑frequency CPG customers and high‑efficiency converting plants.
-
Mayr‑Melnhof Karton AG (MM Group) (Austria) — Premium cartonboard and print quality expertise positions them well for pharmaceutical, luxury and barrier‑sensitive food packaging — segments where print fidelity and material performance command a premium.
-
DS Smith Plc (United Kingdom) — Focuses on circular economy solutions and short‑run digital printing for e‑commerce and FMCG. Their strengths lie in sustainable material systems and retailer collaborations.
-
Amcor plc (Switzerland) — A global packaging incumbent offering hybrid approaches that blend digital printing with flexible and paperboard substrates for multi‑category customers, enabling cross‑portfolio sales synergies.
-
CCL Industries Inc. (Canada) and ePac Holdings (United States) — Both represent converters with strong digital print and label expertise, delivering high‑impact decorative and short‑run cartons for brands focused on rapid shelf turns and promotional activity.
-
THIMM Group, Stora Enso Oyj and Mondi Group — European specialists with complementary strengths in digital displays, renewable fiber materials and customized print solutions. Their integrated capabilities in fiber sourcing and converting are increasingly valuable as sustainability rules tighten.
Latest Industry Movements and Strategic Implications
-
Trade shows such as WEPACK 2026 demonstrated live production lines and accelerated OEM roadmaps toward faster, higher‑quality digital presses. For 2026, executives should plan evaluation pilots with OEMs showcased at these events to compress adoption timelines.
-
Converter case examples (e.g., transitions to Xeikon technology) highlight immediate benefits in production efficiency and quality. These real‑world deployments serve as templates for how to manage changeover costs and skill retraining.
-
Recent plant investments in Europe for pharma‑grade digitally printed folding cartons underline the sectoral pull for compliant, traceable, and low‑volume high‑mix production — a clear signal for focused capability investments for players targeting healthcare customers.
Material, Regulatory and Cost Dynamics
Three structural inputs will shape margins and strategy in 2026:
-
Raw material variability — Paperboard and recovered fiber markets remain subject to pricing volatility. Lightweighting trends reduce per‑unit material consumption, but converters must balance weight reduction against print surface requirements and barrier needs.
-
Regulatory pressure — Europe's Packaging and Packaging Waste Regulation and expanding EPR schemes (regionally accelerating in North America and parts of Asia) are pushing brands toward recyclable mono‑material designs. Digital printing’s plate‑less workflows support rapid SKU variation without the waste associated with traditional prepress, creating a strategic advantage for converters who master recyclable substrate solutions.
-
Operational shifts — Digital adoption reduces minimum economical run lengths and enables variable data. Procurement and commercial teams must revise costing models, SKU rationalization approaches, and inventory policies to capture full value.
Strategic Imperatives for 2026
-
Prioritize hybrid capacity investments where customer mix shows both high‑frequency short runs and selective long runs. Use our scenario model to calculate when inkjet or electrophotography purchases become accretive to margin versus outsourced digital conversion.
-
Embed sustainability as a business model: design for recyclability, document lifecycle benefits of digital workflows, and align with EPR reporting requirements to protect customer relationships and preclude regulatory penalties.
-
Develop commercial offers that monetize personalization — limited editions, localization, and serialized authenticity — with clear ROI metrics for customers based on conversion lift and reduced obsolescence.
-
Build strategic partnerships with OEMs and substrate suppliers to de‑risk supply and secure access to qualified recyclable boards optimized for digital inks and print processes.
-
Use M&A selectively to acquire capabilities (color management, prepress automation, last‑mile finishing) rather than scale alone — the marginal value of specialized digital expertise is high during this transition.
Next Steps — How PW Consulting Supports Your 2026 Playbook
PW Consulting’s full report delivers the models, competitive scorecards, and confidential appendices that boards and investment committees require to move from strategic intent to executable plans. We pair the syndicated forecast with bespoke advisory — from build vs. buy decision workshops to due‑diligence on target converters and implementation roadmaps for production and sales teams.
If your 2026 planning cycle includes capital allocation, channel reshaping or compliance upgrades in packaging, our report will materially shorten your decision timeline and reduce execution risk. For access to the complete data tables, interactive forecast model, and confidential competitive exhibits, please consult the PW Consulting report portal — the in‑depth intelligence is purposely gated to preserve the commercial value of the analysis.
PW Consulting — translating market motion into boardroom action for the digital carton era.
For detailed analysis of this topic, please visit the official page: Worldwide Digital Printed Cartons Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com