

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Phenolic Antioxidant Market Hits USD 2,315.1 Million in 2025, Poised for Further Growth

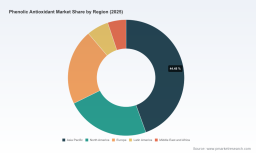
Worldwide Phenolic Antioxidant Market — Strategic Imperatives for 2026: PW Consulting Outlook
Executive teaser
Our new PW Consulting market brief on the Worldwide Phenolic Antioxidant Market frames the commercial and regulatory inflection points that procurement, R&D, corporate development and supply-chain leaders must act on in 2026. Anchored to a 2025 base year, the global phenolic antioxidant market sits at roughly USD 2.32 billion and is forecast to grow at a steady compound annual growth rate (CAGR) of 4.52% over the 2026–2032 horizon to surpass roughly USD 3.15 billion by 2032. That trajectory reflects a mix of demand resilience in plastics, lubricants and specialty applications, offset by margin pressure from upstream feedstock volatility and intensifying regulatory constraints.
Worldwide Phenolic Antioxidant Market
Why this report matters for 2026 decision-makers
-
Time-sensitive procurement planning: With feedstock and freight cost shocks persisting into 2026, buyers who recalibrate indexation clauses and hedging strategies can materially protect margins.
Worldwide Phenolic Antioxidant Market -
R&D and product roadmaps: Reformulation pressures from food-contact and consumer-article regulations are accelerating the move to low-migration and recycled-compatible antioxidant grades; R&D prioritization in 2026 will determine competitive differentiation in 2027–2029.
Worldwide Phenolic Antioxidant Market -
M&A and alliance strategy: Moderate market concentration means well-timed bolt-on acquisitions and specialty partnerships unlock scale and proprietary formulations without the multiples of a fully consolidated sector.
-
Supply-chain resilience: Tariffs, IMO-related bunker surcharge volatility and regional capacity changes require multi-pronged sourcing strategies—localization, dual sourcing, and contract terms designed to share cost shocks.
What the report delivers — practical, actionable intelligence
PW Consulting’s report is built to be directly operationalized by commercial, technical and strategy teams. Highlights of the toolkit included:
-
Forward-looking demand model (bottom‑up) built from 2020–2025 historical activity and run through scenario stress tests for 2026–2032.
-
Price and margin model that links raw-material cost feeds, notable historical price moves and freight/tariff vectors to producer economics.
-
Supplier scorecards with capability matrices (capacity, specialty grades, regulatory certifications, geographic footprint) and a three-tier competitive positioning framework.
-
Regulatory impact matrix with compliance pathways, recommended labelling and formulation guardrails for markets with tightening restrictions.
-
Commercial playbooks for buyers and sellers: negotiation anchors, contract clauses to manage pass-through, and commercialization levers for premium specialty grades (e.g., recycled-compatible antioxidants).
-
M&A and inorganic growth playbook: target profiles and valuation drivers for specialty-grade assets and regional manufacturing nodes.
As a deliberate part of the “trailer” approach, we present the macro outlook and strategic implications here while reserving segment-level tables, region-by-region demand breakdowns and per-application forecasts to the full report. These granular outputs are the core of the paid deliverable and are essential for executable planning.
Market dynamics shaping strategic choices in 2026
The phenolic antioxidant ecosystem in 2026 will be shaped by five interlocking dynamics:
-
Feedstock and price volatility. Upstream tightness in key intermediates pushed spot phenol and related feedstock prices materially in late 2024; producers responded with list-price increases in 2024 and carry-through effects remain in contracts and spot tenders. Procurement teams should expect continued episodic feedstock-driven price moves and structure contracts accordingly.
-
Regulatory tightening and formulation risk. Regulatory action has materially constrained certain legacy phenolic chemistries for consumer contact applications; some widely used antioxidants are limited in concentration in several jurisdictions, and food-contact ceilings for specific grades are enforced. Firms face a twofold task—maintain compliance while preserving performance in high-heat, high-shear polymer processing.
-
Shipment economics and trade friction. Freight surcharge regimes tied to IMO fuel rules and targeted tariffs on imports from specific origins raise landed cost variability. This dynamic favors regional supply solutions and increases the strategic value of localized or near‑market capacity.
-
Demand-side substitution and recycling. Growth in recycled-content polymers and tighter requirements for recyclate-compatible additives are creating demand for new antioxidant grades tailored to recycled streams. Suppliers with early commercialized recycled-compatible antioxidants will capture share in high-growth pockets.
-
Customer consolidation and formulation sophistication. End-markets (plastics compounders, lubricant formulators, rubber manufacturers) are consolidating formulation sourcing, raising the bar for supplier technical support, co‑development and integrated value propositions (e.g., masterbatches, ready-to-use additive packages).
Competitive landscape — who matters and why
The market is neither a tight oligopoly nor wholly fragmented: the top three players account for a meaningful minority share while the top five capture slightly more than half the market. That competitive structure encourages both scale-driven plays and local, specialty-focused strategies.
-
BASF SE (Ludwigshafen, Germany) : Global leader with a broad Irganox portfolio and strong technical services. The company’s recent value-based price actions illustrate ability to pass through feedstock inflation; strategic focus for BASF is sustained premium positioning in high-performance plastics and lubricant stabilization.
-
SI Group (Tarrytown, NY, USA) : Specialty player concentrating on polymer and rubber clients. Recent launches targeting recycled plastics signal a strategic pivot to growth pockets where technical differentiation commands pricing power.
-
Songwon Industrial (Ulsan, South Korea) : Competitive in commodity and semi‑specialty grades; recent capacity expansion demonstrates a play to secure share in polymer demand corridors in APAC and export markets.
-
Lanxess AG (Cologne, Germany) : Strong in lubricant and fuel additive segments with a compliance-centric stance; regulatory recertification efforts reinforce market access and customer confidence.
-
Regional and specialty players (Sumitomo Chemical, Kawaguchi Chemical, Everlight, Rianlon, Yasho, Double Bond, among others): These firms compete on localized service models, price, and specialized grades for PVC, rubber and regional compounders. Several are well positioned to capture demand growth in emerging markets where logistic and tariff barriers favor near-market supply.
Key recent moves underline how incumbents are responding: capacity expansions to capture polymer demand; new grades tailored for recycled-content plastics; price increases to offset feedstock hikes; and regulatory recertifications to preserve route-to-market. For buyers, the implication is clear—vendor selection must weigh scale and specialty capabilities plus contractual protections for pass-through and supply continuity.
Strategic recommendations for 2026
-
Reconfigure procurement to five-year total-cost-of-ownership (TCO) contracts that include indexation triggers, volume-flex clauses and explicit pass-through mechanics for feedstock and freight shocks.
-
Prioritize product redevelopment for low-migration and recycled-compatible antioxidant grades; allocate protected R&D spend with rapid prototyping and pilot-scale validation with key customers.
-
Pursue selective near-market capacity—either greenfield micro-units or toll-manufacturing partnerships—to mitigate tariff/freight exposure and reduce lead times for high-value formulations.
-
Embed regulatory monitoring into product governance: maintain a rolling compliance register for key jurisdictions and pre-certification investments where feasible.
-
Evaluate M&A targets that offer formulation IP, regional manufacturing, or access to specialty end‑markets; modest consolidation can be accretive given the market’s moderate concentration profile.
Methodology and transparency
Our forecast and strategic guidance are derived from a blended methodology: a bottom-up demand model covering 2020–2025 historicals, plant-level capacity mapping, primary interviews across producers, formulators and compounders, price-pass-through econometrics, and regulatory scenario analysis. Sensitivity testing for feedstock shocks, freight-cost scenarios and regulatory tightening underpins our recommended paths.
To preserve the “trailer” intent of this release, we have intentionally not disclosed the report’s segment-level breakouts, region-by-region demand splits or application-specific revenue tables here. These granular outputs—critical for procurement tendering, plant-capacity optimization and M&A valuation—are available in the full report package on our website.
Next steps
For corporate teams preparing budgets, R&D roadmaps, or M&A pipelines for 2026, the report provides direct-to-action guidance and downloadable templates (contract clauses, regulatory checklists, and a supplier-risk workbook). PW Consulting can also deliver an executive briefing tailored to your organization’s exposure across feedstock, geography and application to translate insights into an implementation plan.
Closing
Phenolic antioxidants will remain a foundational enabler across plastics, rubber, lubricants and food/feed stability. The market’s moderate growth and evolving risk landscape make 2026 a pivotal planning year: firms that combine disciplined procurement, regulatory-forward product development and selective capacity plays will convert steady market expansion into durable competitive advantage. PW Consulting’s full report contains the data, models and playbooks to support those decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Phenolic Antioxidant Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com