

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automatic Gearbox Valves Market Poised for 5.12% CAGR — New Market Insights Revealed

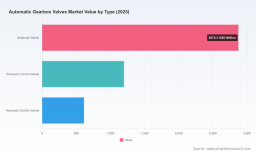
Worldwide Automatic Gearbox Valves Market — Strategic Insights for 2026 Decision‑Makers
PW Consulting’s latest market study, Worldwide Automatic Gearbox Valves Market, frames a rapidly evolving component segment at the intersection of powertrain electrification, regulatory pressure and precision hydraulic‑electronic control. This briefing summarizes the report’s strategic value for executives planning resource allocation, R&D roadmaps, go‑to‑market plays and M&A activity in 2026 — and explains why stakeholders should consult the full report to access the proprietary granular intelligence that underpins these recommendations.
Worldwide Automatic Gearbox Valves Market
High‑level market trajectory and what it means for 2026
From 2020 through our base year 2025, the global automatic gearbox valves market demonstrated steady expansion underpinned by stronger transmission electrification and tighter emissions/fuel‑economy regulation. Measured in USD (Millions), the market grew from the low‑to‑mid single‑digit billions in 2020 to an estimated market size in 2025 that anchors the near‑term planning horizon. PW Consulting projects a compound annual growth rate (CAGR) of 5.12% over the forecast window 2026–2032, with the market continuing to expand through 2032 driven by both conventional and electrified powertrain demand for more sophisticated valve control.
Worldwide Automatic Gearbox Valves Market
For corporate planning in 2026, this trajectory signals three immediate implications:
Worldwide Automatic Gearbox Valves Market
- Investment discipline: allocate R&D and capital expenditure toward valve technologies and control architectures that deliver measurable transmission efficiency and shift quality gains within a moderate growth environment.
- Prioritize modularity: design valve modules and valve body solutions that can be scaled across multiple transmission platforms (conventional multi‑speed AT, CVT, DCT and hybridized variants) to maximize return on tooling and validation investments.
- Supply chain resilience: prepare for episodic raw‑material volatility and downstream OEM warranty risk by diversifying sourcing and building contingency capacity in key geographies.
What the full report delivers — practical, decision‑ready content
PW Consulting’s report is structured to be directly actionable for commercial, product and corporate development teams. Key deliverables include:
- A concise market sizing model and scenario forecasts (base year 2025; forecast period 2026–2032) that allow rapid rerunning of company‑level scenarios against topline demand assumptions.
- Technology menu and roadmaps: comparative analysis of solenoid, pressure control and hydraulic valve approaches, including integration pathways with electronic control units and mechatronic valve bodies.
- Manufacturing and cost levers: guidance on lightweight valve‑body casting choices, coatings and tolerancing strategies that materially affect bill‑of‑material and assembly costs.
- Commercial playbook: OEM procurement sensitivities, pricing dynamics, and contract structures (tiered warranty, performance‑based rebates, localization milestones) tailored to automatic gearbox valves.
- A risk‑adjusted M&A and partnership framework: triage criteria for bolt‑on acquisitions, JV partners and technology licensing to accelerate time‑to‑market.
To preserve the strategic advantage for clients, this public summary deliberately omits granular split values and per‑region/appliance revenue breakdowns. The full dataset and interactive models are available through our subscription portal and include the segment‑level intelligence required for precise investment sizing and negotiation preparation.
Competitive landscape — what to watch in 2026
The competitive structure of the gearbox‑valves market is moderately concentrated, reflecting a mix of global Tier‑1s and specialized solenoid specialists. Market concentration metrics indicate that the three largest players account for a meaningful portion of supply, while the five largest firms together represent over sixty percent of industry revenue — a dynamic that shapes pricing power, technical barriers and OEM sourcing strategies.
Leading companies that will shape competitive dynamics in 2026 include established transmission systems and mechatronics suppliers as well as focused solenoid specialists. Select strategic profiles (non‑exhaustive):
- BorgWarner (Auburn Hills, Michigan, USA) — a leading Tier‑1 supplier with a strong portfolio of electro‑hydraulic solenoids and valve body assemblies targeting efficiency and shift quality across multi‑speed and hybridized powertrains.
- Aisin Corporation (Kariya, Aichi, Japan) — vertically integrated supplier producing transmissions and integrated gearbox valves with deep OEM relationships and precision hydraulic capability.
- ZF Friedrichshafen (Friedrichshafen, Germany) — emphasizes electronic‑hydraulic integration for passenger and commercial applications and competes on system performance and integration depth.
- Bosch GmbH (Gerlingen, Germany) — leverages a broad powertrain electronics portfolio to offer pressure and shift solenoids as part of integrated powertrain modules.
- TLX Technologies and HUSCO Automotive (Wisconsin, USA) — specialized solenoid and valve manufacturers that play a critical role as innovation partners and second‑source suppliers for OEMs and Tier‑1s.
- Magna Powertrain, Hitachi Astemo, Mitsubishi Electric, Parker Hannifin — each brings differentiated strengths in full powertrain systems, hydraulic control modules, mechatronics expertise and fluid control technologies.
Competitive dynamics in 2026 will be shaped by three tactical behaviors:
- OEM preference for suppliers that can demonstrate demonstrable lifecycle cost savings via improved shift calibration and reduced parasitic losses.
- Increased collaborations and selective vertical integration as OEMs seek suppliers who can co‑develop valve control logic and hardware tuned for hybrid and mild‑hybrid architectures.
- Greater emphasis on second‑source qualification and regional capacity as OEMs de‑risk supply chains after high‑profile reliability and recall incidents.
Recent industry signals — operational implications
Three recent developments crystallize where executives must act in 2026:
- Manufacturing expansions: HUSCO Automotive’s facility expansion announced in late 2024 signals rising demand for electro‑hydraulic solenoids for shift‑by‑wire and start‑stop systems. Strategic implication: OEMs and Tier‑1s should evaluate long‑lead capacity commitments and preferred supplier status to secure output.
- Quality and warranty risk: A major recall related to a transmission control valve defect underlines the cost and reputational impact of valve reliability issues. Strategic implication: invest in accelerated validation rigs, field‑failure analytics and design‑for‑serviceability to limit warranty exposure.
- Cross‑sector partnerships: Emerson’s 2025 partnership showcases transferability of advanced solenoid technologies from industrial to automotive contexts. Strategic implication: active scouting of adjacent‑industry innovations can deliver performance and emissions benefits faster than pure in‑house development.
Regulatory and materials context — risk and opportunity
Regulatory tightening in major markets — directed at fuel economy and emissions — is an accelerant for advanced gearbox valve adoption. Electronic control of hydraulic circuits enables nuanced shift strategies and lock‑up control that directly affect vehicle efficiency. Simultaneously, volatility in raw material prices for aluminum and specialty steels affects cost competitiveness for valve bodies and associated components.
- Regulation: anticipate continued pressure from US and EU rulemaking that will make valve‑level efficiency gains a procurement criterion for OEMs.
- Materials: factor in scenarios for aluminum and steel cost swings and assess alternative materials, coatings and process improvements (for example, thin‑wall castings and corrosion‑resistant spool finishes) to protect margins.
How to use this intelligence in 2026 — recommended actions
For commercial and technical leaders preparing budgets and strategic plans in 2026, PW Consulting recommends a five‑point action agenda:
- Fast‑track modular product families that support both conventional and hybrid transmissions, shortening time‑to‑qualification for OEM programs.
- Authorize targeted capacity investments and preferred‑supplier agreements in regions aligned with your OEM book of business to mitigate lead‑time and logistics risk.
- Embed reliability engineering and field‑data analytics into post‑production processes to reduce recall risk and strengthen pricing power via proven total cost of ownership advantages.
- Pursue selective partnerships with specialized solenoid innovators and adjacent‑industry technology owners to import rapid performance gains with limited capex.
- Scenario‑plan for material cost volatility with hedging, supplier contracts and design alternatives to preserve margin flexibility.
Why stakeholders should read the full report
This press release highlights the strategic contours of the automatic gearbox valves market, but intentionally withholds the granular regional and application splits that underpin tactical 2026 decisions. The full PW Consulting report provides:
- Interactive market models (base year 2025; 2026–2032 forecast) enabling bespoke sensitivity analysis for corporate planning.
- Detailed supplier benchmarking, procurement playbooks and price‑to‑performance matrices to inform contract negotiations.
- Proprietary failure‑mode insights and test protocols to reduce time‑to‑market and warranty exposure.
Executives who must commit budgets, structure supply agreements or evaluate M&A targets in 2026 will find the full dataset and supporting analysis indispensable. Contact PW Consulting to arrange a briefing and to access the models and annexes that translate high‑level trends into executable actions.
Methodology note
The analysis herein uses 2025 as the base year and projects out to 2032. Market sizing is expressed in USD (Million) and growth is reported on a compound annual growth rate (CAGR) basis. Competitive concentration metrics reported in this summary indicate a market where the top three and five suppliers represent material shares of demand — a structural feature that informs recommended negotiation and partnership strategies.
For access to the full report, proprietary tables, vendor scorecards and client‑tailored scenario runs, please reach out to PW Consulting. Our team stands ready to help you convert these industry dynamics into a prioritized 2026 action plan.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Gearbox Valves Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com