

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Skin Perfusion Pressure Testing Devices Market Poised for 5.8% CAGR Through 2032
By pmarketresearch, 2026-07-15
PW Consulting Releases Strategic Brief: Worldwide Skin Perfusion Pressure (SPP) Testing Devices Market — Critical Guidance for 2026 Decision-Making
PW Consulting today publishes the executive briefing for our new market research report, Worldwide Skin Perfusion Pressure Testing Devices Market. The report codifies five years of historical market intelligence (2020–2025), a 2025 base-year assessment, and a forward-looking forecast through 2032. Our analysis shows the market has expanded from the high hundreds of millions in 2020 to a clearly larger base in 2025 (USD 235.0 Million), and is positioned to grow at a compound annual growth rate (CAGR) of 5.8% across the 2026–2032 forecast period — reaching a projected market scale by 2032 that materially changes competitive calculus for device firms, payers, and health systems.
Worldwide Skin Perfusion Pressure Testing Devices Market
Why this report is a must-read for executives planning 2026 strategies
-
Actionable foresight at a pivotal inflection: SPP testing is transitioning from a niche vascular assessment tool to an integral diagnostic adjunct for wound care and vascular planning. The growth trajectory and timing outlined in our models identify a window in 2026 where strategic moves (clinical evidence generation, reimbursement capture, targeted partnerships) yield outsized returns relative to later entry.
Worldwide Skin Perfusion Pressure Testing Devices Market -
Investment and portfolio prioritization: With a steady mid-single-digit CAGR driving the marketplace, capital allocation decisions across R&D, commercial expansion, and M&A require calibrated timing. The report translates macro growth into decision-ready scenarios for investment committees.
Worldwide Skin Perfusion Pressure Testing Devices Market -
Regulatory and payer dynamics that determine commercial viability: SPP devices sit within established regulatory pathways and accepted coding frameworks — factors that shorten commercialization timelines for prepared firms and raise the barrier to entry for others.
What the report delivers — practical intelligence, not academic theory
-
Market sizing and trend analytics: Time-series market sizing (2020–2025) and a robust forecast (2026–2032) with sensitivity analyses across adoption, pricing, and reimbursement scenarios — all modeled in downloadable spreadsheets for client stress-testing.
-
Segment strategy playbook: Detailed, operational recommendations for product, channel, and geographic prioritization designed to be executable by commercial leaders. (Note: fine-grained segment tables are reserved for the full report to preserve competitive advantage.)
-
Clinical and regulatory roadmap: A checklist and timeline for 510(k) strategy, clinical evidence packages, and post-market surveillance approaches tailored to skin perfusion pressure modalities.
-
Reimbursement playbook: Tactical guidance for coding, coverage, and price realization negotiations—mapping the corridors where SPP testing can be integrated into care pathways to secure incremental revenue.
-
Competitive intelligence and M&A scouting: Profiles of incumbents, challenger technologies, capability gaps, and consolidation targets — with actionable shortlists for buy-side and sell-side teams.
-
Commercial execution templates: Go-to-market KPIs, sample account plans for wound care centers and hospital vascular units, and service adoption levers that convert clinical interest into recurring utilization.
Market dynamics you need to internalize for 2026 planning
-
Clinical drivers: Rising chronic wound prevalence, the ongoing burden of diabetes-related peripheral vascular disease, and greater emphasis on limb salvage programs are steadily pushing SPP testing into standard diagnostic pathways where perfusion metrics improve clinical decision-making.
-
Technology evolution: Incremental improvements in laser Doppler, photoplethysmography (PPG) hybrids, and pressure-cuff integration are increasing the reliability and ease-of-use of SPP devices. These product enhancements are shortening training curves and enabling broader deployment beyond specialist centers.
-
Regulatory constraints and enablers: SPP devices commercially land within the 510(k) regulatory framework as Class II devices (product code KMA). A clear path to market exists for firms with predicate-based claims, but claims architecture and labeling strategy materially affect time-to-revenue.
-
Payer behavior: SPP testing is reimbursed within extant noninvasive arterial study codes; the commercial upside for suppliers depends on packaging tests into reimbursable bundles and demonstrating downstream cost avoidance (e.g., avoided amputations or targeted revascularization).
-
Market structure: The market shows moderate concentration — the leading firms control a meaningful share of volume and installed base. This dynamic concentrates clinical relationships and service capabilities with incumbent vendors but also opens acquisition opportunities for mid-market entrants.
Competitive landscape — what market leaders are doing now
-
ViOptix (Fremont, CA) — Known for the Oximeter+ system which combines laser Doppler and PPG approaches. ViOptix has strengthened clinical positioning through iterative firmware and algorithm updates; a recent firmware release improved SPP accuracy in diabetic foot assessments, reinforcing their suitability for limb salvage programs and adding incremental value to existing accounts.
-
Perimed AB (Järfälla, Sweden) — Perimed’s PeriFlux family emphasizes laser Doppler modules and integrated pressure-perfusion workflows. Their recent presence at leading clinical forums demonstrates a strategy of evidentiary commercialization: showcasing automated SPP testing capability to clinicians and influencing adoption at wound care centers and vascular clinics.
-
Moor Instruments (Axminster, UK) — Moor’s platforms support SPP protocols via laser Doppler flowmetry and pressure cuff integration. The company’s focus remains on supporting research and specialist clinical use, with propositions centered on measurement fidelity and device interoperability.
Competitive takeaways: incumbents are leveraging device-level updates, clinical outreach at specialty conferences, and service assurance to lock-in core accounts. For challengers, differentiation through workflow integration, cloud-enabled reporting, or bundled service contracts is the most viable path to displace entrenched vendors.
Strategic moves to prioritize in 2026
-
Lock the clinical evidence gate: Invest in prospective, indication-specific studies that demonstrate how SPP-guided decisions change clinical endpoints and total cost of care. Evidence that links SPP use to avoided downstream interventions accelerates payer acceptance.
-
Design reimbursement-first commercial models: Align product pricing and service bundles with existing noninvasive vascular study codes and build payer dossiers that quantify health-economic benefit. Tactical pilots with large hospital systems will unlock scale contracts.
-
Operationalize regulatory strategy early: Use predicate devices and targeted 510(k) claims to shorten time-to-market, but simultaneously plan for label expansion supported by post-market data for higher-value indications.
-
Targeted partnerships over broad geographic expansion: Select clinical hubs and wound care networks for concentrated deployment, establishing center-of-excellence cases that create reference accounts for broader rollouts.
-
Prepare for consolidation: Given market concentration among the top competitors, M&A is a high-probability strategy for players seeking rapid scale. Our report identifies capability gaps most attractive to acquirers (software-enabled analytics, cloud reporting, and bundled services).
Clinical use-cases where SPP testing creates business value
-
Diabetic foot care and limb salvage — objective perfusion metrics inform decisions on revascularization, debridement, and amputative planning.
-
Pre- and post-revascularization assessment — closer monitoring of skin perfusion helps predict wound healing potential and optimize intervention timing.
-
Flap and reconstructive surgery — trend monitoring of perfusion supports early detection of compromised grafts.
-
Research niche — in patients with calcified vessels where Doppler signals are unreliable, SPP testing is often discussed as a research-use modality; clinical adoption requires clear study protocols and interpretive frameworks.
How PW Consulting turns insight into executable advantage
-
Custom due diligence: Fast-turn commercial and clinical diligence packages for investment teams assessing target valuations and integration synergies.
-
Market entry blueprints: End-to-end plans covering regulatory pathway, clinical trial design, pricing playbook, and initial account targeting to compress time-to-scale.
-
Commercial acceleration sprints: On-the-ground programs to convert pilot sites into national contracts, including field sales enablement, clinical education curriculum, and value-based contracting templates.
-
Data and models: Access to the full financial model, country-level adoption trajectories, and customizable scenario tools that let clients quantify upside under alternative pricing, adoption, and regulatory assumptions.
Next steps for readers
This briefing outlines the strategic contours that will shape winners and losers in the SPP testing market through 2026 and beyond. For organizations making capital allocation, portfolio, or commercial decisions in 2026, the stakes are clear: early movers who combine credible clinical evidence, pragmatic regulatory strategy, and payer-aware commercial models will capture disproportionate share of the market’s growth.
To review the full data tables, granular segmentation, country-level forecasts, and downloadable valuation models that support these recommendations, please visit the PW Consulting report page for the Worldwide Skin Perfusion Pressure Testing Devices Market. Our full report contains the proprietary breakdowns and executable templates that clients rely on to convert insight into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Skin Perfusion Pressure Testing Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Dust Extraction System Market Poised for 5.8% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Dust Extraction System Market: Strategic Intelligence Briefing for 2026 Decisions
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I am pleased to present a focused intelligence briefing drawn from our latest Worldwide Dust Extraction System Market study (base year 2025, forecast period 2026–2032). This briefing explains why the report is a practical decision-making instrument for corporate leaders, investors, and operations executives planning for 2026, and it highlights the strategic choices the market dynamics are forcing across product design, supply chains, service models, and regulatory compliance. Consider this a high-value trailer: we reveal the macro contours and the actionable frameworks you need to prioritize, while preserving the granular segment-level models and numeric splits that are available in the full report.
Worldwide Dust Extraction System Market
Market Snapshot: Growth Trajectory and Structural Context
The global dust extraction systems market is moving from steady maintenance demand into a period of measured expansion. Our model—anchored to 2025 as the base year—projects a compound annual growth rate (CAGR) of 5.8% over the 2026–2032 forecast window. The market size in 2025 stood at a quantified macro level that provides a reliable planning baseline; our forecasts place the market materially higher by 2032 under a central scenario that assumes continued regulatory tightening, retrofit activity, and modernization across heavy industries.
Worldwide Dust Extraction System Market
Two structural features are critical for corporate planning in 2026: (1) the market remains fragmented, with the combined share of the three largest vendors and the five largest vendors reflecting a low-to-moderate concentration profile, and (2) demand drivers are increasingly non-price factors—regulation, lifecycle retrofit programs, and total cost of ownership (TCO) optimization—rather than simple replacement cycles. These realities shape the choice set for both incumbent vendors and new entrants.
Worldwide Dust Extraction System Market
Why This Report Matters for 2026 Strategic Decisions
- Regulatory-Driven Capital Allocation: The consolidation of combustible-dust guidance into NFPA 660 (effective December 2024) and active enforcement through OSHA programs means organizations must prioritize compliant systems now. Our report maps how these regulatory shifts change equipment specifications, site-level risk assessments, and capital project timelines.
- Supply-Chain & Cost Risk Management: Tariffs introduced in 2025 on filter media and specialized alloys have altered component sourcing economics. The study provides a decision framework that quantifies trade-offs between offshore procurement, nearshoring, and increased inventories—critical inputs for procurement strategies in 2026.
- Retrofit Opportunity Prioritization: Aging cement and steel plants in North America and Europe are undergoing retrofit programs to meet tighter emission and opacity rules. Our retrofit prioritization matrix helps operations teams rank projects by payback, regulatory urgency, and operational risk—enabling rational capex phasing in 2026 budgets.
- Service-Led Revenue Strategies: As equipment becomes more commoditized, aftermarket services (filter subscription models, predictive maintenance, and performance guarantees) are the durable margin play. The report includes commercial models and pricing benchmarks for service offerings across customer segments.
Competitive Landscape — what 2026 decision-makers must know
The competitive map blends global filtration champions, specialized regional manufacturers, and agile OEMs that serve discrete verticals. The market’s low-to-moderate concentration means strategic moves (alliances, bolt-on acquisitions, or vertical partnerships) can rapidly alter market positions if executed with operational precision. Below are profiles of the core companies we analyze in depth, with strategic implications drawn from comparative capabilities and go-to-market postures.
- Donaldson Company, Inc. (Bloomington, Minnesota, USA) — A global filtration leader offering cartridge collectors, baghouses, and established product lines for manufacturing, metalworking, pharma, and food processing. Strengths: broad product breadth, global service footprint, R&D in filtration media.
- Nederman Holding AB (Helsingborg, Sweden) — Specializes in workplace extraction with integrated solutions including extraction arms and ventilation systems for metalworking and heavy industry. Strengths: ergonomic/workplace safety positioning and system integration expertise.
- Camfil AB (Stockholm, Sweden) — Focuses on high-efficiency air filtration and APC cartridge solutions targeted at energy efficiency and sustainability. Strengths: regulatory advisory capacity and energy-optimized product lines.
- Parker Hannifin Corporation (Cleveland, Ohio, USA) — Offers industrial filtration as part of a broader industrial portfolio. Strengths: cross-selling into larger industrial accounts and engineering scale.
- AAF International (Louisville, Kentucky, USA) — Long-established air filtration and dust collection provider with deep legacy expertise. Strengths: strong brand and lifecycle service capability.
- Oneida Air Systems, Inc. (Syracuse, New York, USA) — Known for cyclone and cartridge units, with strength in woodworking and smaller industrial setups. Strengths: niche channel penetration and flexible product lines.
- A.C.T. Dust Collectors (USA) — Rugged cartridge and baghouse manufacturer for heavy-duty environments. Strengths: industrial robustness and customization capability.
- Sly Incorporated (Cleveland, Ohio, USA) — Custom baghouse and wet scrubber specialist for OEMs and industrials. Strengths: bespoke engineering and turnkey supply.
- Höcker Polytechnik GmbH (Germany) — Modular systems and MultiStar collectors with energy optimization emphasis for woodworking and industry. Strengths: modular design and energy focus.
- Moldow A/S (Denmark) — Long-standing modular systems provider promising significant energy savings for large-scale manufacturing. Strengths: energy efficiency claims and scale for big plants.
- Dustcontrol (Norsborg, Sweden) — Provider of mobile and central vacuum extraction units for construction and industrial sites. Strengths: mobility and on-site construction solutions.
- Imperial Systems, Inc. (Pennsylvania, USA) — Makers of high-performance CMAXX systems directed at metalworking and demanding environments. Strengths: warranty-driven commercial positioning and performance credentials.
- Airflow Systems, Inc. (Dallas, Texas, USA) — Custom air filtration and portable collectors for welding and machining. Strengths: tailored solutions and small-to-medium enterprise channel reach.
Strategic takeaways for 2026: incumbents must choose between doubling down on scale (to capture retrofit and large-plant deals) or doubling down on services and channel breadth (to monetize smaller accounts and aftermarket spend). For new entrants, targeting under-served verticals with differentiated service models or energy-focused systems creates a fast track to profitable niches.
Technology, Product and Service Trends to Watch in 2026
- Energy & Performance Optimization: Cartridge and modular systems with reduced power consumption are commanding premium commercial terms where lifecycle cost matters. Case examples by major suppliers demonstrate deployment of energy-saving topologies in welding, laser cutting, and woodworking environments.
- Combustible-Dust Compliance: NFPA 660 alignment is accelerating demand for engineered systems, hazard analyses (DHAs), and integrated suppression/ventilation strategies. Manufacturers that pair engineering advisory with equipment delivery win higher contract values.
- Digitalization & Predictive Maintenance: IoT-enabled filters and predictive algorithms are transitioning from pilot to mainstream. Buyers expect clearer ROI models for condition-based servicing and filter-life optimization.
- Modular & Mobile Units: Construction and service sectors prefer mobile or modular extraction systems for episodic worksites; new product launches at trade shows in 2025–2026 underscore this continuing trend.
Recent Industry Signals Reinforcing Strategic Choices
- Regulatory consolidation via NFPA 660 (effective Dec 2024) and active OSHA enforcement pathways (NEP) are reshaping system specifications and creating urgency for DHAs and compliance upgrades.
- Tariffs on filter media and specialty alloys introduced in 2025 have elevated component cost volatility—prompting procurement teams to reassess nearshoring and vendor qualification strategies.
- Retrofit programs at aging cement and steel facilities, driven by tightened EPA and EU emission rules, are creating concentrated windows of opportunity for large-scale baghouse and cartridge installations.
- Notable vendor activity includes targeted product introductions and trade-show product rollouts in 2025–2026 that emphasize compact, energy-saving extractors and oil-mist/dust hybrid solutions—signaling where short-term demand pockets will appear.
What the PW Consulting Report Provides (Practical Deliverables)
The full PW Consulting market study is structured as an operational toolkit for managers deciding how to allocate capital and commercial resources in 2026. Key deliverables include:
- Dynamic market-sizing models and scenario maps (historical 2020–2025 and forecast 2026–2032) with sensitivity tests for regulation, tariffs, and retrofit uptake.
- A vendor benchmarking suite that evaluates technology, geographic coverage, aftermarket capability, and commercial positioning—presented as an investability matrix to support M&A and partnership screening.
- Practical TCO calculators, retrofit prioritization frameworks, and procurement decision trees to expedite capex approvals.
- Regulatory compliance checklists and a DHA playbook aligned with NFPA 660 and OSHA expectations.
- Commercial templates for subscription-based filter programs, performance guarantees, and service contracts with pricing guidance and margin expectations.
Note: the full report contains granular segmentation, regional/application splits, and unit-level pricing models. These detailed tables and scenario-oriented workbooks are intentionally gated to ensure our clients get the exclusive, high-value models needed to make defensible 2026 decisions.
Final Recommendations for Leaders Planning 2026
- Prioritize compliance-driven retrofit pipelines and align capital allocation to projects with the fastest regulatory or revenue impact.
- Lock in strategic supplier arrangements for critical filter media and specialty alloys, and evaluate nearshoring options to mitigate tariff exposure.
- Invest in service-commercialization: subscription filters, predictive maintenance, and performance contracts meaningfully increase lifetime margins.
- Use targeted M&A or distribution partnerships to accelerate entry into retrofit-heavy geographies or to acquire digital/IoT competencies.
- Deploy the PW Consulting retrofit prioritization and TCO frameworks to de-risk multi-year capex commitments and to create executive-level visibility for 2026 budgets.
For procurement, engineering, and corporate development leaders, the choices made in 2026 will define competitive positions over the next business cycle. PW Consulting’s Worldwide Dust Extraction System Market study translates macro growth (anchored to a 5.8% CAGR through 2032) into executable steps—balancing compliance urgency, supply-chain resilience, and service-led margin expansion. To access the full dataset, segmentation matrices, and decision-support workbooks, please visit the PW Consulting report portal or contact your account representative for an executive briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Dust Extraction System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mini Tractors Market Set to Expand at 5.5% CAGR, Reaching USD 20.75 Billion by 2032
By pmarketresearch, 2026-07-15
Worldwide Mini Tractors Market: Strategic Signals for 2026 Decision-Making
As PW Consulting releases its latest Worldwide Mini Tractors Market study (base year 2025, forecast 2026–2032), corporate leaders, product strategists, and M&A teams must re-evaluate plans against a market that is stabilizing after uneven growth and entering a structurally higher trajectory. Our proprietary analysis synthesizes historical performance (2020–2025), near-term corrections, and a multi-year forecast anchored by a 5.5% compound annual growth rate (CAGR) across the 2026–2032 horizon — delivering the actionable intelligence required to make decisive moves in 2026.
Worldwide Mini Tractors Market
Why this report matters for 2026
-
Macro clarity at a pivotal juncture — The mini tractor market reached a clear inflection in 2025. Our full-model forecasts map a short-term correction followed by a sustained recovery that drives the market into a new, larger scale by the end of the forecast window. Leaders who align product, channel, and capital allocation in early 2026 will capture outsized returns as demand normalizes and structural adoption accelerates.
Worldwide Mini Tractors Market -
Precision for resource allocation — With compressed development cycles and rising regulatory complexity, companies need targeted scenarios that quantify design, compliance, and production trade-offs. The report translates macro trends into capital planning and product roadmap implications tailored to OEMs, suppliers, and financiers.
Worldwide Mini Tractors Market -
Playbooks — Beyond forecasting, we deliver executable playbooks for market entry, portfolio optimization, and channel economics to shorten time-to-profit for new models and regional expansions.
Market trajectory: what the headline numbers reveal
Our market model shows the worldwide mini tractors market consolidating to a new baseline in 2025, followed by a near-term adjustment in 2026 and a steady compound annual growth rate of 5.5% through 2032. By the end of the forecast period, the global market moves materially higher compared with the 2025 base, reflecting sustained mechanization in agriculture, renewed investments in landscaping and urban utility applications, and incremental replacement demand.
For decision-makers, the practical implication is twofold: (1) margin recovery and network optimization will matter as aftermarket and parts revenue streams scale with installed bases, and (2) the timing of capex and product launches becomes a differentiator — launching into the upswing versus the correction materially affects ROI horizons.
Practical content inside the report
-
Dynamic demand scenarios: interactive demand curves keyed to commodity cycles, subsidy regimes, and infrastructure spending. These scenarios enable CFOs and business unit heads to stress-test revenue and cashflow under alternative macro outcomes.
-
Policy and regulation impact matrices: quantified cost-and-time impacts of emission standards and trade measures on engine platforms and module sourcing strategies. This includes engineering cost estimates and supplier qualification timelines tied to the most consequential regulatory regimes.
-
Supply-chain risk heatmaps: supplier concentration, critical raw-material exposure (notably high-strength steel and specialty alloys), tariff sensitivities, and mitigation levers (dual sourcing, nearshoring, design for alternative materials).
-
Commercial playbooks: go-to-market frameworks for OEMs and distributors covering pricing, financing structures, trade-in programs, and localized aftersales models that improve lifetime value.
-
M&A and partnership screening: a ranked pipeline of target archetypes, integration checklists, and valuation heuristics appropriate to buyers focused on scale, capability acquisition, or channel consolidation.
Competitive landscape — what separates winners from the rest
The mini tractors market remains dominated by established OEMs with deep channel networks, broad product families, and global manufacturing footprints. Key players that shape industry dynamics include John Deere (Moline, Illinois, USA), Kubota Corporation (Osaka, Japan), Mahindra & Mahindra (Mumbai, India), TYM (Tong Yang Moolsan, South Korea), LS Tractor (LS Mtron, South Korea), Kioti Tractor (Daedong, South Korea), Yanmar (Osaka, Japan), CNH Industrial / New Holland (UK/Italy), AGCO / Massey Ferguson (USA), and VST Tillers Tractors Ltd (India).
Across this competitive set, success factors are converging on a few high-leverage capabilities:
-
Localized cost-to-serve optimization — Manufacturers that combine modular platforms with regional localization of key subassemblies win on price without sacrificing reliability.
-
Aftermarket and financing — Integrated finance offers and strong parts networks materially increase uptake among smaller farms and non-agricultural buyers.
-
Compliance and engineering depth — Meeting tighter emission standards requires investment in engine technologies and after-treatment systems, advantaging firms with in-house powertrain expertise or strong partnerships.
-
Product ergonomics and operator value — Comfort, safety, and ease-of-use increasingly influence purchase decisions in landscaping, horticulture, and smallholder contexts.
Recent product movements underscore these dynamics: Kubota launched an operator-focused Grand L70 series in late 2025; VST rolled out FENTM compact tractors for small and mid-sized farms in 2025; Massey Ferguson introduced upgrades to its utility line targeting comfort and efficiency; and LS Mtron expanded its North American compact tractor range earlier in 2025. These introductions signal an industry emphasis on operator experience, fuel efficiency, and platform versatility.
Regulation, raw materials, and policy — the hidden drivers
Regulatory developments and raw-material volatility are not peripheral risks — they are primary determinants of product architecture and cost. The EU Stage V emissions requirements impose more sophisticated injection and after-treatment solutions on compact tractors, raising engineering and production costs that cascade through supplier agreements and pricing strategies. At the same time, fluctuations in high-strength steel and specialized alloy prices directly affect chassis and axle manufacturing economics, and tariff regimes (including certain steel and component levies) continue to shape sourcing choices in key markets.
On the demand side, national subsidy and credit programs remain powerful accelerants for adoption. For example, recent allocations in India to support farm mechanization materially improve access to finance for smallholders and shift purchase timing — a vector that global OEMs must incorporate into regional go-to-market plans.
Strategic recommendations for 2026
-
Prioritize platform modularity and options portfolios. Invest in modular chassis and powertrain architectures that allow rapid region-specific adaptations without full redesigns.
-
Lock in strategic suppliers and hedging arrangements for critical metals and alloy inputs. Short-term price swings can erode margins faster than demand shocks.
-
Embed financing and aftersales at launch. Bundling financing and predictable maintenance offerings increases conversion and reduces churn among first-time mechanization buyers.
-
Target product launches to the early phase of projected recovery windows. Timing new model introductions to pre-empt market resupply cycles yields superior market share gains.
-
Use M&A selectively to buy capabilities — not just scale. Target acquisitions that add emission-compliant powertrain tech, telematics, or distribution density rather than only revenue lifts.
Scenario planning — what to prepare for
Our scenario suite includes a baseline that assumes steady policy support and manageable raw-material inflation, a downside where protectionist trade measures and accelerated material cost increases compress margins, and an upside driven by faster-than-expected smallholder mechanization and urban landscaping demand. Each scenario includes discrete triggers and timelines tied to capital allocation recommendations so that executives can convert insight into quarterly actions.
What the report does not give away — and why that matters
Consistent with PW Consulting’s “trailer” approach, this release demonstrates the analytical depth and strategic prism used to produce the study while deliberately omitting granular segmentation tables and region/application-specific financials that form the core, proprietary deliverables. Those datasets — including our full model outputs, regional demand curves, and high-resolution price-elasticity matrices — are central to tactical decisions such as SKU rationalization, plant footprint shifts, and targeted dealer incentives. They are available through our report portal for clients who require the full evidence base to execute with precision.
Next steps and how to access the full intelligence
Leaders who require detailed scenario models, market-by-region and application breakouts, supplier-level risk assessments, and the full competitive database (including detailed product mappings and recent developments) should consult the complete Worldwide Mini Tractors Market report (base year 2025). The report provides the exact numerical matrices and downloadable model files that underpin the strategic recommendations summarized here.
For executives preparing budgets and product roadmaps in early 2026, the window to align launches, finance programs, and supply-chain interventions to the market’s next upswing is narrow. PW Consulting’s detailed datasets and execution checklists are designed to convert foresight into measurable business outcomes.
Contact PW Consulting or visit our report page to request an executive briefing, obtain sample model outputs, or arrange a custom deep-dive tailored to your organization’s position in the mini tractors value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Mini Tractors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Exterior Solar Shading Systems Market at USD 8,850 Million in 2025 — Europe Leads with USD 3,675.42 Million; 4.65% CAGR to USD 12,165.16 Million by 2032
By pmarketresearch, 2026-07-15
Worldwide Exterior Solar Shading Systems Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
PW Consulting’s latest market intelligence positions the Worldwide Exterior Solar Shading Systems market at a pivotal inflection point as organizations prepare strategy in 2026. Using 2025 as the base year, our market model estimates the global market at approximately USD 8,850 million (USD Million reporting basis) and forecasts expansion through 2032 to roughly USD 12,165 million, implying a compound annual growth rate (CAGR) of 4.65% across the 2026–2032 forecast window. This growth is underpinned by regulatory pressure for energy efficiency, rising demand for façade-level building performance solutions, and rapid product innovation around automation and integrated photovoltaics.
Worldwide Exterior Solar Shading Systems Market
Why this report matters for enterprise decisions in 2026
- Strategic timing: 2026 is the first full planning year after major regional regulatory shifts and material-market shocks—companies that translate these signals into procurement, R&D and M&A actions early will secure disproportionate advantage.
- Actionable intelligence: The report synthesizes macro drivers, scenario-tested forecasts, and vendor-level playbooks so executives can convert market momentum into defensible 12–36 month plans.
- Risk-adjusted planning: We combine price volatility scenarios with supply-chain contingency templates to quantify margin and specification risk for manufacturers, distributors and large buyers.
Market trajectory and what the headline numbers conceal
The market’s headline trajectory—mid-single-digit CAGR to 2032—belies important structural complexity. Growth is consistent but uneven: pockets of high-value demand linked to retrofit programs, sustainable certifications and commercial façade upgrades coexist with price-sensitive residential retrofits. The market remains fragmented: the combined share of the largest suppliers remains low enough to indicate substantial space for scale consolidation and local-specialist win strategies. For incumbents and new entrants alike, this creates simultaneous opportunities to expand through bolt-on acquisitions and to capture margin through system-level integration (shading + controls + services).
Worldwide Exterior Solar Shading Systems Market
Competitive landscape — strategic positioning of core players
The competitive field is characterized by a mix of global platform leaders, automation specialists, façade systems manufacturers and regional premium artisans. Our review of the industry’s leading names reveals repeatable strategic archetypes:
Worldwide Exterior Solar Shading Systems Market
- Global platform integrators (example: Hunter Douglas): Broad product portfolios and distribution networks; advantage in design-led, energy-focused offerings that serve both commercial and high-end residential channels.
- Automation and controls specialists (example: Lutron, Somfy): Edge in smart integration, building-management-system connectivity and occupant-centric controls — critical as shading becomes part of whole-building energy strategies.
- Façade and aluminum systems providers (example: Kawneer/Arconic): Strength in architectural-grade extrusions, integration with curtain walls and performance-driven façade specifications.
- Regional engineering & premium manufacturers (examples: WAREMA, Griesser, Levolux): Competitive advantage through high-quality customization, local codes expertise and contractor relationships.
- Value-focused & commercial suppliers (examples: Skyco, Draper, Insolroll): Deliver pragmatic, cost-optimized systems for large-scale commercial deployments.
For decision-makers, the implication is practical: competing on product alone will be insufficient. The winning business models combine hardware, software-enabled services (commissioning, predictive maintenance), and channel partnerships that reduce specification friction for architects and building owners.
Supply chain, cost pressures and regulatory inflection points
Raw-material volatility surfaced as a dominant near-term risk in our 2026 model. Aluminium—central to extruded profiles and many shading frames—experienced notable price escalation in the recent 12–18 months, with widely reported year-on-year rises and elevated LME settlement levels during early 2026. Such movements materially affect bill-of-materials for exterior systems and force margin compression unless mitigated by pricing strategies, hedging, or material substitution.
Concurrently, regulatory changes are accelerating product demand in specific specification channels. Examples include updated conservation and overheating guidance that emphasize exterior shading as a primary solution to manage solar heat gain, and carbon-border mechanisms that shift incentives toward materials with verified low-carbon footprints. These forces increase demand for circular-material inputs and favor manufacturers who can demonstrate end-to-end compliance and carbon accounting.
Technology and innovation trends shaping procurement and product strategy
- Smart, AI-driven controls: Recent product introductions demonstrate that shading is transitioning from manual or schedule-based operation to AI-augmented behavior that optimizes daylighting, glare control and HVAC load in real time.
- Distributed power and solar integration: Innovations such as rollable screens with integrated solar foils and solar-powered motors reduce wiring complexity and enable net-zero-aligned solutions for retrofits.
- Micro-structure and glazing synergy: Acquisitions and IP plays in micro-structured glazing indicate an emerging sub-layer of shading that blurs the boundary between glass and shading device — creating opportunities for differentiated performance claims.
- Modularization and prefabrication: Offsite modular façade components and plug-and-play shading systems accelerate installation schedules on commercial projects and reduce commissioning risk.
Recent industry moves — signals and strategic takeaways
- Product launches combining synchronization, AI and solar-powered actuation emphasize system-level differentiation rather than component upgrades — manufacturers should prioritize software and systems R&D alongside hardware innovation.
- Targeted acquisitions of IP in glazing and micro-structure engineering illustrate how private investors are financing capability consolidation — strategic buyers should monitor IP-rich small- and mid-cap targets to accelerate time-to-market.
- Industry exhibitions and concentrated product roll-outs in 2026–2027 will create windows for specification wins; vendors who demonstrate live performance (measured energy savings, user comfort metrics) will outperform those relying on aspirational claims.
Strategic implications — five pragmatic actions for 2026
- Recast product roadmaps around systems, not components: Prioritize investments in controls, connectivity and commissioning services that create recurring revenue and specification stickiness.
- Implement a raw-material hedging and procurement playbook: Layer purchasing contracts, selective vertical integration and material-substitution pilots to protect margin against aluminium volatility.
- Pursue targeted IP-led acquisitions or alliances: Look for micro-structure glazing, distributed-solar actuation and AI-control platforms that complement your current capabilities.
- Introduce specification-ready case studies: Deploy pilot projects with verifiable energy and comfort metrics to shorten sales cycles with architects and specifiers subject to evolving building codes.
- Strengthen regulatory and sustainability positioning: Create verified carbon disclosures and recycled-content supply chains to mitigate CBAM and similar import/regulation risks while commanding price premiums.
What PW Consulting’s report delivers — practical content designed for execution
Our full market study goes well beyond headline growth figures. For executive teams preparing 2026 actions, the report provides:
- A transparent market model (2020–2025 historicals; 2026–2032 forecasts) with scenario toggles to stress-test commodity price, regulation and adoption curves.
- Segment-level intelligence (by geography, application and product family) with normalized demand drivers and unit economics — presented to guide prioritization without over-emphasizing transitory peaks.
- In-depth competitor dossiers and capability matrices that map product portfolios, route-to-market, and technology stacks for the leading global and regional suppliers.
- Supply-chain and procurement playbooks including sensitivity analysis, hedging templates and supplier scorecards to operationalize cost-mitigation strategies.
- Commercial tools: RFP language templates, specification checklists, ROI calculators for retrofit vs. new-build, and an investment case toolkit for M&A screening.
- Practical case studies and audited performance data points to support specification and commercial dialogue with architects, owners and developers.
Next steps — where to get the full intelligence
This briefing is a strategic “trailer” intended to surface the major signals and recommended actions for 2026. The full PW Consulting report contains the granular subsegment data, downloadable financial models, and supplier benchmarking that procurement, R&D and corporate development teams need to turn strategy into execution. For access to the complete analysis and the model files that underpin our forecasts, please visit the PW Consulting publications portal or contact your account representative for an enterprise briefing and data license.
PW Consulting stands ready to support scenario planning, commercial due diligence, competitive response design, and procurement optimization for organizations looking to lead in the exterior solar shading systems arena through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Exterior Solar Shading Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Outdoor Industrial Water Storage Tank Market Poised to Reach USD 5,014.9 Million by 2032 at a 5.48% CAGR
By pmarketresearch, 2026-07-15
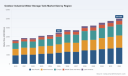
Worldwide Outdoor Industrial Water Storage Tank Market: Strategic Preview for 2026 Decision‑Makers
PW Consulting is pleased to release an executive preview of our upcoming Worldwide Outdoor Industrial Water Storage Tank Market study. As organizations operationalizing capital projects and global water stewardship plans plan for 2026, this briefing synthesizes the report’s most consequential strategic takeaways—demonstrating how the market’s macro trajectory, competitive dynamics, regulatory drivers, and materials economics should shape procurement, manufacturing, and project‑finance decisions next year.
Worldwide Outdoor Industrial Water Storage Tank Market
High‑level market trajectory: a resilient, mid‑single‑digit growth story
The outdoor industrial water storage tank market has recorded steady expansion across the 2020–2025 baseline and is projected to continue its upward trajectory into the 2026–2032 forecast window. Our analysis shows the market reached approximately USD 3.45 Billion (Revenue Unit: Million USD) in the base year 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 5.48% over the 2026–2032 period, approaching an estimated USD 5.01 Billion by 2032.
Worldwide Outdoor Industrial Water Storage Tank Market
For executives, two implications emerge immediately. First, capacity planning and supplier selection should be informed by a market that is growing but not hyper‑consolidating—demand is sufficient to support strategic investments yet remains distributed across many projects and end‑use sectors. Second, a predictable growth profile creates an environment where targeted product and service differentiation (for durability, speed of installation, or low lifecycle O&M) can readily translate into outsized commercial returns.
Worldwide Outdoor Industrial Water Storage Tank Market
What the full PW Consulting report includes (practical, transaction‑ready content)
-
Actionable financial models calibrated to 2020–2025 historical performance and 2026–2032 forecasts, enabling scenario analysis for capex, payback and NPV under alternative material, installation and maintenance strategies.
-
Decision‑grade procurement playbooks for owner‑operators, EPCs and large industrial buyers that cover contracting models (turnkey vs. modular supply), risk allocation, warranty negotiation points, and certified‑material requirements for potable and industrial water applications.
-
A supplier due‑diligence framework that operationalizes technical and commercial criteria—manufacturing footprint, coating systems and standards compliance, warranty strings, proven install base, and spare‑parts logistics—so buyers can convert insight into RFP language.
-
Project deployment templates that reduce schedule risk (prefab vs. field assembly), quantify labor and lifting equipment needs, and benchmark installation timeframes for comparative tender evaluation.
-
Regulatory and standards compendium tailored to cross‑jurisdictional projects, highlighting compliance pathways for potable water certification, interior coating specifications, and prestressed concrete design codes.
-
Risk matrices and mitigation playbooks for raw material volatility, regulatory change, and extreme‑weather resilience—designed to be embedded in CAPEX approval packages.
Competitive landscape: fragmentation, specialized leaders, and the path to commercial differentiation
The market remains fragmented: the three largest suppliers account for under one‑fifth of global share, and the top five suppliers represent just over a quarter. This structure—a CR3 of 18.45% and a CR5 of 27.12%—creates space for regional champions and technologically differentiated entrants to win significant project share without confronting dominant global incumbents.
-
FORGE Global Tanks (Katy, TX) combines in‑house engineering and a strong installed‑base narrative for bolted steel solutions. Their AWWA/NFPA/Eurocode‑aligned coatings and end‑to‑end delivery model are well suited to owners seeking single‑vendor accountability for medium to large projects.
-
CST Industries leverages factory‑applied glass‑fused and epoxy systems that target low life‑cycle maintenance—an attractive positioning for municipal and industrial buyers prioritizing TCO over lowest initial price.
-
SBS Tanks (SBS Group) and other regional modular steel specialists have demonstrated how standardized, ISO‑driven manufacturing practices enable rapid deployment in mining and remote industrial settings.
-
DN Tanks, CROM Corporation and other prestressed concrete specialists maintain strength in very large, long‑durability applications where lifecycle stiffness and corrosion resistance are paramount.
-
Polyethylene and poly‑lined offerings from manufacturers such as Aquamate and recent capacity expansions observed among polyethylene suppliers broaden options where ultraviolet resistance, cost competitiveness and short lead times matter.
For strategic buyers and investors, the practical takeaway is threefold: (1) procurement should match technology to lifecycle objectives rather than presume one material class is “best,” (2) local manufacturing and installation capability remains a decisive differentiator in reducing schedule and logistics risk, and (3) focused supplier development (coatings, liners, modular design) is where incumbents and new entrants can capture premium margins.
Market dynamics shaping procurement and CAPEX in 2026
-
Raw material volatility: Steel and polymer price dynamics materially impact relative unit economics between steel, concrete and polyethylene solutions. For context, steel pricing in the United States averaged about USD 885 per metric ton in mid‑2025, while HDPE resin benchmarks in Europe rose toward USD 1,200 per metric ton later that year. Buyers should integrate sensitivity runs on key raw material indices into capex approvals and consider hedging strategies where feasible.
-
Standards and potable‑water certification: Certification regimes such as NSF/ANSI/CAN 61 and AWWA standards (including AWWA D102 and D110 variants that address coatings and prestressed concrete) are increasingly enforced by owners and financiers. Non‑compliance risks both project delays and long‑term liability; certification status must therefore be a minimum pass/fail criterion in technical evaluation.
-
Installation productivity and modularization: Product design advances—such as bolted designs that reduce installation time by multiple weeks—translate directly into lower mobilization and downtime costs. Our market scoring shows that faster‑to‑install modular systems are being selected more frequently when the value of avoided downtime exceeds the small premium for prefabrication.
-
Application diversification: Industrial buyers are re‑balancing storage needs across wastewater, fire protection, chemical processing and process water. While each application imposes distinct material and coating requirements, integrated suppliers that can manage multiple certifications and service agreements command pricing leverage.
Recent development signals to watch in 2026
-
Capacity shifts in polyethylene: Expansions and UV‑stabilized product introductions among polymer suppliers indicate increasing competitiveness of synthetic tanks for outdoor use where sunlight exposure and durability were previously constraints.
-
Design productivity: Bolted tank design updates that materially shorten installation time are changing the procurement calculus—projects with constrained site access or tight schedules are particularly affected.
-
Large civil projects: Recent completions of large reinforced concrete tanks underscore the sustained demand for high‑volume, long‑life civil solutions, especially in municipally funded treatment and storage projects.
Strategic recommendations for 2026 decision cycles
-
Run material‑agnostic, lifecycle total‑cost analyses. Move beyond first‑cost procurement to models that quantify maintenance, coating re‑application cycles, and downtime impacts over 20–30 year horizons.
-
Embed standards compliance as a gating criterion in RFPs and contract milestones. Require certification documentation up front and link milestone payments to compliance verification.
-
Pursue supply‑chain redundancy for critical coatings and liners. Given raw material price swings and regional supply constraints, dual‑sourcing or pre‑procurement of long‑lead coating systems reduces schedule risk.
-
Prioritize suppliers with proven modular and rapid‑install capability for projects with time‑sensitive commissioning windows; quantify time‑to‑first‑service as a decision metric alongside CapEx.
-
Consider staged capex with option clauses to expand capacity or retrofit lining systems—this hedges against uncertainty in material pricing and regulatory evolution.
Why PW Consulting’s full report is a 2026 strategic asset
Our full study goes beyond headline growth numbers to provide transaction‑ready tools: contractual templates, supplier scorecards, CAPEX/OPEX model workbooks, and a granular risk register mapped to mitigation actions. The preview you are reading offers the directional intelligence required to frame 2026 budgets; the full report supplies the executable playbooks procurement teams and project sponsors need to act decisively.
Next steps
Organizations preparing 2026 budgets or large water infrastructure projects should request PW Consulting’s full report and associated modeling pack. The complete deliverable contains the detailed segmentation analysis, comprehensive supplier profiles, and downloadable financial models that senior leaders and project teams need to convert market insight into lower‑risk, higher‑value outcomes. For those who prefer an interactive briefing, our senior analysts are available to walk through scenario runs and supplier shortlists tailored to specific project geographies and application requirements.
PW Consulting remains committed to translating market intelligence into operational advantage. Contact our research team to schedule a briefing and to learn how the full Worldwide Outdoor Industrial Water Storage Tank Market report can be integrated into 2026 decision workflows.
For detailed analysis of this topic, please visit the official page: Worldwide Outdoor Industrial Water Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Water‑Based Acrylates Copolymer Rheology Modifiers Market Poised to Expand at a 5.34% CAGR Through 2032
By pmarketresearch, 2026-07-15
Worldwide Water-Based Acrylates Copolymer Rheology Modifiers Market — Strategic Outlook for 2026
Executive summary
As companies reset strategies for 2026, the water-based acrylates copolymer rheology modifiers market presents a mix of steady growth, input-cost volatility and accelerating product innovation. Our latest PW Consulting market model places the global market at USD 942.5 Million in the base year (2025) and projects a compound annual growth rate (CAGR) of 5.34% through the 2026–2032 forecast window — a trajectory that implies meaningful expansion in absolute demand and sustained commercial opportunity for formulators, additives suppliers and downstream processors.
Worldwide Water Based Acrylates Copolymer Rheology Modifiers Market
Why this report matters for 2026 corporate decisions
Decisions taken in 2026 will determine who captures disproportionate value over the next investment cycle. That is because the sector now sits at the intersection of four structural forces:
Worldwide Water Based Acrylates Copolymer Rheology Modifiers Market
- raw-material cost volatility and regional feedstock imbalances;
- an industry-wide push for sustainable and bio-derived chemistries;
- a gradual but persistent shift to waterborne formulations across paints, personal care and home care; and
- consolidation dynamics where a small set of global suppliers wield market influence while a long tail of regional players addresses niche needs.
For C-suite leaders — procurement, R&D, corporate development and commercial heads — the report converts market scale and growth expectations into specific, executable options: where to allocate R&D dollars, how aggressively to pursue price and margin protection, which partners to consider for co-development, and how to prioritize geographies for capacity investment or divestiture.
Worldwide Water Based Acrylates Copolymer Rheology Modifiers Market
Practical contents: what the report delivers
This study is designed as a decision-ready dossier for 2026. Key pragmatic deliverables include:
- Comprehensive market model (historical 2020–2025, forecast 2026–2032) with top-line sizing, growth drivers and scenario variants;
- Segment mapping by technology, application family and region, with qualitative and quantitative demand levers highlighted (note: detailed sub-segment tables are intentionally reserved for the full report);
- Competitive benchmarking: product portfolios, go-to-market models, channel footprints, and supplier positioning matrices;
- Raw-material sensitivity and cost-pass-through tool: scenario analysis on acrylic monomer price swings and logistical cost shocks;
- Commercial playbooks for premiumization, formulators’ win-sets, and value-based pricing strategies;
- M&A and partnership screen: target profiles, strategic rationale, and integration risk checklists;
- Regulatory and sustainability risk matrix, including practical mitigation levers for compliance and claims substantiation;
- Supplier scorecards and procurement negotiation templates tailored to rheology modifier vendors.
Industry dynamics and 2026 implications
Raw material movements in late 2025 and early 2026 have been materially influential. Asia experienced oversupply conditions during 2025 that pushed acrylic acid pricing down significantly, while North American monomer indices showed a moderate softening in Q1 2026. Simultaneously, at least one major producer announced price increases in North America in early 2026, citing energy, logistics and feedstock pressures. These seemingly conflicting signals—regional oversupply versus targeted price increases—create a nuanced procurement landscape:
- Short-term windows of low spot-costs can provide formulators with margin recapture opportunities, but they increase the risk of cyclical inventory obsolescence for upstream players.
- Price announcements by large chemical producers serve more as signaling mechanisms; buyers should prepare flexible contracting frameworks (banded pricing, collars, and rolling hedges) rather than static long-term fixed-price contracts.
- Producers and suppliers must also factor in rising customer demand for sustainability: recent product introductions from incumbent suppliers demonstrate that "bio-aware" or lower-carbon rheology chemistries are moving from R&D novelty to commercial shelf reality.
Competitive landscape — what leading suppliers are doing
The market is characterized by a core group of established international players complemented by specialized regional producers. The competitive dynamics we observe are best understood as a two-track game: global formulary leadership and regional/segment specialization.
- The Dow Chemical Company (USA) leverages established product franchises focused on associative and non-associative acrylates chemistries tailored to personal care and waterborne systems. Their strengths are broad application know-how and deep formulation support.
- BASF SE (Germany) plays to a wide industrial customer base with synthetic rheology modifiers for coatings and aqueous formulations; their recent commercial tactics around raw-material pricing highlight a willingness to protect margin when supply-chain costs warrant.
- Lubrizol Corporation (USA) is positioning aggressively on sustainability and performance parity: a staged rollout of bio-oriented rheology polymers and public performance data demonstrates a capability to challenge incumbent acrylate technologies in high-growth rinse-off personal care segments.
- Arkema, Ashland, Elementis, Clariant, BYK (ALTANA), Akzo Nobel, and Croda each bring differentiated strengths — from coatings additives know-how to sensory/texture optimization in personal care — enabling them to compete on formulation expertise, regulatory support and localized manufacturing footprints.
- Specialist manufacturers such as 3V Sigma, Lamberti and Organik Kimya remain relevant through tight coupling with personal-care formulators and rapid product customization for regional requirements.
Overall, market concentration is moderate: a handful of global suppliers capture a material share of commercial value while regional players retain pockets of influence. This structure creates opportunities for both scale-driven consolidation and bolt-on acquisitions that fill capability or regional gaps.
Strategic implications and recommended actions for 2026
For companies engaged in or adjacent to the acrylates rheology space, we recommend a framework of three parallel actions to be executed in 2026:
- Defensive commercial moves: implement dynamic pricing clauses and indexed contracts tied to acrylic monomer benchmarks; deploy customer-tiered value propositions that trade technical support and formulation co-development for longer-term supply commitments.
- Offensive product and go-to-market plays: accelerate sustainable polymer offerings and invest in demonstrable performance data (benchmarks on clarity, thickening efficiency and sensory metrics). For formulators, prioritize formulations that reduce total cost-in-use while meeting consumer-driven mildness and sustainability criteria.
- Structural portfolio choices: evaluate capacity footprint vis-à-vis regional feedstock realities (e.g., Asia oversupply vs. localized demand growth), and use M&A selectively to acquire either specialty technologies or fill distribution gaps in strategic geographies.
How PW Consulting’s report operationalizes these recommendations
Our report does more than diagnose: it equips teams with executable instruments. Examples include a calibrated raw-material sensitivity model that links acrylic monomer scenarios to margin outcomes at product level; supplier comparison matrices that score technical breadth, geographic reach and commercial flexibility; and a five-scenario strategic road map for M&A and capex prioritization. To preserve commercial value and ensure focused engagement, the public summary intentionally omits the granular sub-segment tables and proprietary scoring that form the heart of our decision tools — these are delivered exclusively with the full report and supporting consultancy services.
Next steps
For leaders who need to convert the market’s macro momentum into defensible advantage in 2026, our full Worldwide Water-Based Acrylates Copolymer Rheology Modifiers Market report provides the quantitative detail, validated supplier assessments and scenario tools required for immediate action. PW Consulting can also tailor a short engagement to apply the models to your P&L and make-ready an operational plan for commercial, procurement and R&D teams.
Contact PW Consulting or visit our report page to access the full dataset, supplier scorecards, and the suite of decision-support tools that will make your 2026 strategic choices evidence-based and execution-ready.
For detailed analysis of this topic, please visit the official page: Worldwide Water Based Acrylates Copolymer Rheology Modifiers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Zeolite Adsorbents Market to Reach USD 7,497.1 Million by 2032, Growing at a 5.38% CAGR
By pmarketresearch, 2026-07-15
Worldwide Zeolite Adsorbents Market: Strategic Outlook for Corporate Decision-Makers in 2026
PW Consulting’s latest market study on Worldwide Zeolite Adsorbents delivers an actionable intelligence package designed to support boardroom and commercial decisions in 2026 and beyond. The zeolite adsorbents market has moved from a niche industrial input to a strategically important material class—driven by emissions control, gas separation, specialty detergents, and emerging sustainable-fuels applications. Our analysis shows the market expanded from roughly USD 4.0 billion in 2020 to about USD 5.2 billion in 2025, and is projected to approach USD 7.5 billion by 2032 under a mid-case path consistent with a 5.38% compound annual growth rate (CAGR) through the forecast window. This growth story masks important inflection points that purchasing teams, technology strategists, and M&A groups must address in 2026.
Worldwide Zeolite Adsorbents Market
Why 2026 is a Pivotal Year
-
Regulatory tightening and emissions enforcement are accelerating demand for zeolite-based solutions in VOC capture, CO2 separation and low-VOC process lines. New and updated standards in major markets mean purchasers and refiners must reassess adsorbent loadings and regeneration strategies this year.
Worldwide Zeolite Adsorbents Market -
Downstream shifts—particularly in fuels and petrochemicals—are creating differentiated requirements for adsorbent life, mechanical integrity and catalytic synergies. The crossover between zeolites as adsorbents and as catalyst components creates opportunity, but also complexity for suppliers and buyers.
Worldwide Zeolite Adsorbents Market -
Supply-side constraints are emerging in the raw material base: synthetic aluminosilicate feedstocks and certain rare earth dopants have experienced price and availability volatility, stressing manufacturing margins and time-to-market for new formulations. Procurement teams must act now to de-risk feedstock exposure.
What This Report Delivers (Practical, Executable Outputs)
-
Integrated market sizing and a dynamic demand model calibrated to 2020–2025 history and a detailed 2026–2032 forecast. The model is delivered in flexible format so teams can test price, regulation and substitution assumptions without re-running base methodology.
-
Boardroom-ready scenario analysis (baseline, sustainability-accelerated and supply-shock disruption) that translates macro outcomes into supplier, product and capital priorities for 2026 decisions.
-
Competitive intelligence toolkit with supplier capability matrices, go-to-market profiles, and a proprietary supplier-strength scoring framework to prioritize partners for long-term contracts, joint development, or acquisition targets.
-
Operational playbooks: adsorbent lifecycle optimization, retrofit vs replacement decision trees, and a regeneration-capex calculator that allows engineering and procurement teams to quantify TCO impacts for alternate adsorbent chemistries.
-
Regulatory and raw-material trackers that translate key policy milestones and feedstock trends into procurement lead-times and margin impact scenarios—vital inputs for 2026 contracting windows.
Competitive Landscape: Strategic Takeaways for 2026
The zeolite adsorbents sector is populated by a mix of global integrators, specialty producers and regionally scaled manufacturers—each pursuing distinct strategic plays. Leading global suppliers have doubled down on integrated solutions (adsorbents + process licensing + aftermarket services), while specialty players emphasize high-performance formulations and close OEM relationships.
-
Honeywell UOP (United States) has reinforced its upstream catalyst and molecular-sieve franchise through a recent acquisition that expands its capabilities across refining and renewable-fuels catalysts—an action that signals continued consolidation among technology-integrated suppliers. Expect a stronger push into bundled process/adsorbent offerings that lock in aftermarket revenue.
-
BASF SE (Germany) continues to invest in pilot and solids processing capacity to accelerate commercialization of advanced zeolite-linked catalyst systems. Their recent facility and product launches indicate a strategy of shortening R&D-to-market timelines for complex formulations used in FCC and emissions control.
-
Tosoh Corporation (Japan), W. R. Grace & Co. (United States), Zeochem AG and Zeolyst International (United States) remain focused on specialty molecular sieves and high-purity powders—positions that favor long-term contracts with gas-processing and high-end industrial customers.
-
Regional producers—including prominent Chinese manufacturers—are scaling capacity for mainstream molecular sieves and adsorbents to serve domestic industrial and environmental markets. Their cost structures and proximity to feedstock sources create competitive pressure on commodity-grade products.
-
Smaller technology players and specialty groups are leveraging partnerships—such as catalyst scale-ups with biofuels technology vendors—to capture growth in sustainable fuels and circular-chemistry opportunities. These collaborations are a reliable signal of where premium-margin work will accrue.
Supply-Chain and Raw-Material Considerations
Manufacturers rely on aluminosilicate feedstocks and process chemistries that are energy intensive and material-sensitive. In 2025–2026 we track three supply-side realities that will shape procurement strategy:
-
Feedstock concentration and processing intensity: high-purity sodium silicate/aluminate streams and controlled hydrothermal synthesis demand predictable energy and logistics. Buyers should stress-test suppliers for feedstock resilience and energy-indexed cost pass-throughs when negotiating multi-year contracts.
-
Dopant and rare-earth volatility: specific catalyst-enhanced zeolite formulations sometimes rely on lanthanum or cerium; export controls and supply tightness have added price variance to these formulations. Where formulations permit, consider substitution pathways or secure multi-source supply.
-
Regional pricing cycles: recent market intelligence showed regional price divergence in late 2025 driven by demand softness in some industrial user segments and steady demand in others. Procurement groups should build flexible purchasing corridors and optionality into renewal clauses.
Regulatory Drivers and Demand Shifts
Stricter industrial emissions standards and sectoral bans (for example, detergent phosphate restrictions) are creating durable new demand vectors for synthetic zeolites. At the same time, air-separation and gas-processing applications are being reshaped by decarbonization programs and fuel-quality requirements. These policy signals are persistent—not transitory—and should inform 2026 capex and product roadmaps.
Scenario Planning and 2026 Strategic Actions
PW Consulting recommends decision-makers use the next 12 months to implement three pragmatic actions aligned to scenario outcomes:
-
Baseline (moderate growth): Prioritize supplier rationalization and negotiate indexed, multi-year supply agreements with technical performance SLAs. Freeze small-scale pilot investments and focus capital on process optimizations that reduce adsorbent consumption.
-
Sustainability-accelerated (policy-driven demand spike): Move rapidly to secure capacity with suppliers who can co-develop low-GHG synthesis routes and offer lifecycle emissions data. Consider strategic partnerships or minority equity in specialty players to lock innovation pathways.
-
Supply-shock (feedstock or dopant disruption): Activate contingency sourcing, accelerate qualification of alternate chemistries, and deploy incremental inventory buffers only where justified by criticality. Use temporary co-fire or surrogate materials for low-risk streams while preserving critical applications.
How PW Consulting Supports Execution
Our Worldwide Zeolite Adsorbents Market report is structured for immediate use by procurement, technology and corporate development teams. Key deliverables include:
-
A live market model with driver-level sensitivity (price, demand elasticity, regulatory steps).
-
Supplier evaluation matrices and recommended contracting frameworks for 12–36 month horizons.
-
Techno-economic appendices for common adsorbent chemistries, and a library of board-level slides summarizing scenario outcomes and action checklists.
-
An M&A and partnership playbook that maps capability gaps to target archetypes and suggests negotiation levers appropriate to the current consolidation wave.
We intentionally present strategic depth while withholding detailed segment-level tables and proprietary pricing curves from this public brief to protect the analytical integrity of our client deliverables. For corporate teams preparing 2026 budgets and strategic plans, the full report provides the granular regional, type and application breakdowns that translate high-level direction into executable procurement and R&D programs.
Next Steps
For executives looking to convert insight into action this year, PW Consulting offers tailored briefings and model walkthroughs that align the report outputs with your organization’s procurement cycles, capex timelines and innovation roadmaps. Contact our industry team to schedule a strategic briefing and to access the complete dataset, supplier scorecards and scenario workbooks that underpin this analysis.
PW Consulting — Strategic clarity for the materials that will shape 2030 outcomes.
For detailed analysis of this topic, please visit the official page: Worldwide Zeolite Adsorbents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Maskless Lithography Market to Expand at 8.76% CAGR from 2026–2032
By pmarketresearch, 2026-07-15
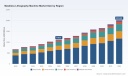
Worldwide Maskless Lithography Machine Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study, covering a historical window from 2020–2025 (base year 2025) and a forward-looking forecast horizon of 2026–2032, establishes a clear, investment-grade roadmap for companies that must make technology, product, and commercial decisions in 2026. The market for maskless lithography machines is on a sustained growth trajectory (CAGR 8.76%), expanding from an assessed global market size of USD 1,120.5 Million in 2025 to a projected USD 2,016.98 Million by 2032. This briefing distills the report’s strategic implications without revealing the granular segmentation tables reserved for subscribers — what follows is the actionable intelligence senior leaders need to prioritize choices in 2026.
Worldwide Maskless Lithography Machine Market
Why 2026 Is an Inflection Year
-
System-level convergence. Advances in light engines (notably high-pixel-count DMD devices), laser direct-write performance, and electron beam platforms are converging with materials and assembly innovations (e.g., hybrid bonding and roll-to-roll processing) to make maskless approaches viable not only for R&D and prototyping, but increasingly for niche and hybrid high-volume flows.
Worldwide Maskless Lithography Machine Market -
Component and compute breakthroughs. Suppliers of DMDs and high-speed optics announced products in late 2024–2025 that materially raise achievable throughput and resolution. These developments address the historical bottlenecks of data-rate and stitching precision by enabling real-time pattern streaming and sub-micron fidelity on larger formats.
Worldwide Maskless Lithography Machine Market -
Regulation and standards are maturing. ISO laser-beam characterization standards and device/medical regulatory requirements (FDA/ISO frameworks) are being codified in ways that affect qualification timelines and capital planning for semiconductor, MEMS, and biomedical device manufacturers.
-
Market structure is neither fragmented nor monopolistic. Our concentration analysis shows a market where leading vendors hold substantial share but a healthy ecosystem of specialists persists — providing multiple options for alliances, white-labeling, and targeted competition.
What the PW Consulting Report Delivers — Practical, Transaction-Ready Outputs
-
Proven market sizing and scenarios: a base-case built on the 2025 baseline, upside/downside scenarios tied to adoption of roll-to-roll and HVM maskless integrations, and modeled sensitivity to DMD supply constraints and standardization timelines.
-
Go-to-market playbooks: tailored strategies for OEMs, system integrators, foundries, and equipment-less embedders — including pricing constructs, service & uptime SLAs, and aftermarket revenue models.
-
Technology roadmaps and IP maps: comparative analysis of optical engines, beam technologies, and patterning software stacks, plus a patent landscaping exercise indicating where freedom-to-operate and blocking IP reside.
-
Vendor scorecards and partner matrices: decision-ready evaluations of machine suppliers based on throughput, resolution, footprint, modularity, and lifecycle cost — enabling rapid shortlisting for pilots and procurement.
-
Operational templates: CAPEX/OPEX calculators, floor-space and utilities modeling for 300/200/150 mm integration, and quality-compliance checklists for FDA/ISO qualification paths.
-
M&A and investment radar: prioritized target lists and value-creation scenarios for tuck-ins, capability buys, or joint ventures aligned to three strategic pathways — scale, specialize, or software-led differentiation.
-
Primary intelligence appendices: annotated interviews with equipment OEMs, foundry adopters, materials suppliers, DMD vendors, and standards bodies, together with trade-show verification and patent citation chains.
Competitive Landscape — Who Matters and What They Bring
The report profiles the full range of incumbent and challenger firms shaping the market: global laser lithography specialists, high-resolution electron-beam vendors, DMD-based system manufacturers, and compact tabletop providers for lab-scale work. Key players include established OEMs that bring high-precision laser and direct-write platforms, suppliers pushing high-throughput maskless exposure tailored for advanced packaging, and a cohort of niche firms delivering table-top and grayscale capabilities for photonics and microfluidics.
From a strategic vantage point:
- Leaders with high-precision direct-write portfolios are best positioned to protect premium R&D and production niches but face pressure to scale throughput.
- Vendors investing in DMD/optics partnerships and roll-to-roll integrations are the most likely to displace masked flows in flexible-electronics and some advanced-packaging segments.
- Smaller, nimble vendors excel in rapid prototyping, specialized microfabrication, and research markets — making them attractive acquisition targets for larger OEMs seeking to broaden product stacks quickly.
Market concentration metrics in the report quantify this competitive reality and show meaningful incumbency among top manufacturers while leaving room for disruptive entrants and targeted consolidation.
Recent Industry Signals You Must Act On
-
New high-pixel-count DMDs and optics announced by component suppliers materially change throughput economics — creating a clear technology adoption pathway for maskless systems in tighter-tolerance production domains.
-
Major OEMs are transitioning from demonstration to commercialization platforms: co-creation facilities and trade-show deployments reflect shortened lead times from lab to factory.
-
Product upgrades among leading direct-write suppliers underscore a near-term product refresh cycle. Buyers and partners should anticipate hardware and software versioning implications for qualification windows in 2026–2027.
-
Regulatory and standards developments can add lead time to qualification and customer acceptance; proactive compliance roadmaps reduce time-to-revenue risk.
Five Strategic Moves for 2026
-
Prioritize integration pilots where maskless systems complement existing masked flows rather than attempting wholesale replacement. Focus pilot selection on high-margin, short-feedback applications (e.g., advanced packaging and flexible-device sub-runs).
-
Lock in critical optics and DMD supply lines now. Component lead times and node-specific performance will determine throughput ceilings; supplier agreements should include roadmap commitments and supply guarantees.
-
Invest in the software-data axis. The highest commercial leverage lies in patterning pipelines — compression, error correction, and adaptive exposure control are differentiators that shift TCO in your favor.
-
Pursue modular solutions and service-led business models. Machines with modular upgrades and strong service ecosystems lower buyer risk and open recurring revenue opportunities.
-
Use M&A to acquire capability fast. Identify small-to-mid-sized innovators in grayscale lithography, microfluidics patterning, or high-precision direct-write as tuck-in targets to accelerate roadmap delivery.
Risk Profile and Mitigation
Key risks include component supply cyclicality (particularly DMDs and high-spec optics), standards-induced qualification delays, and the perennial tension between throughput and resolution. The report provides a quantified risk matrix linking each risk to revenue impact scenarios and prescribes mitigations — for example, multi-sourcing strategies, staged qualification approaches, and insurance-like service agreements to protect early adopters.
How to Use This Report in Your 2026 Planning Cycle
Procurement teams should pair the report’s vendor scorecards with 12–18 month pilot timetables to ensure equipment qualification aligns with product launches. R&D and product leaders will find the technology roadmaps and IP landscapes essential for prioritizing internal programs versus sourcing external capabilities. Finance and corporate development functions will benefit from the scenario-driven valuation models when allocating capital between greenfield fabs, co-development partnerships, and M&A.
Closing — A Strategic Teaser
Maskless lithography is no longer a pure R&D curiosity; it is a maturing set of technologies creating practical options for companies that need faster design iteration, lower tooling risk, and new form-factor production capability. PW Consulting’s report combines rigorous market sizing (base year 2025), an 8.76% CAGR projection across 2026–2032, vendor concentration analysis, and operation-ready playbooks to make 2026 procurement, investment, and partnership decisions less risky and more opportunistic.
To access the full dataset, vendor scorecards, and the actionable annexes that contain the granular segmentation and financial models reserved for report subscribers, please consult the official PW Consulting distribution channels. The full report includes the detailed splits and appendices that underpin the strategic recommendations summarized here.
PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Worldwide Maskless Lithography Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com