

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Maskless Lithography Market to Expand at 8.76% CAGR from 2026–2032

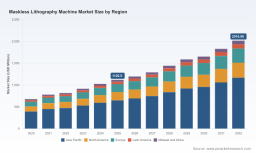
Worldwide Maskless Lithography Machine Market — Strategic Briefing for 2026 Decision-Makers
PW Consulting’s latest market study, covering a historical window from 2020–2025 (base year 2025) and a forward-looking forecast horizon of 2026–2032, establishes a clear, investment-grade roadmap for companies that must make technology, product, and commercial decisions in 2026. The market for maskless lithography machines is on a sustained growth trajectory (CAGR 8.76%), expanding from an assessed global market size of USD 1,120.5 Million in 2025 to a projected USD 2,016.98 Million by 2032. This briefing distills the report’s strategic implications without revealing the granular segmentation tables reserved for subscribers — what follows is the actionable intelligence senior leaders need to prioritize choices in 2026.
Worldwide Maskless Lithography Machine Market
Why 2026 Is an Inflection Year
-
System-level convergence. Advances in light engines (notably high-pixel-count DMD devices), laser direct-write performance, and electron beam platforms are converging with materials and assembly innovations (e.g., hybrid bonding and roll-to-roll processing) to make maskless approaches viable not only for R&D and prototyping, but increasingly for niche and hybrid high-volume flows.
Worldwide Maskless Lithography Machine Market -
Component and compute breakthroughs. Suppliers of DMDs and high-speed optics announced products in late 2024–2025 that materially raise achievable throughput and resolution. These developments address the historical bottlenecks of data-rate and stitching precision by enabling real-time pattern streaming and sub-micron fidelity on larger formats.
Worldwide Maskless Lithography Machine Market -
Regulation and standards are maturing. ISO laser-beam characterization standards and device/medical regulatory requirements (FDA/ISO frameworks) are being codified in ways that affect qualification timelines and capital planning for semiconductor, MEMS, and biomedical device manufacturers.
-
Market structure is neither fragmented nor monopolistic. Our concentration analysis shows a market where leading vendors hold substantial share but a healthy ecosystem of specialists persists — providing multiple options for alliances, white-labeling, and targeted competition.
What the PW Consulting Report Delivers — Practical, Transaction-Ready Outputs
-
Proven market sizing and scenarios: a base-case built on the 2025 baseline, upside/downside scenarios tied to adoption of roll-to-roll and HVM maskless integrations, and modeled sensitivity to DMD supply constraints and standardization timelines.
-
Go-to-market playbooks: tailored strategies for OEMs, system integrators, foundries, and equipment-less embedders — including pricing constructs, service & uptime SLAs, and aftermarket revenue models.
-
Technology roadmaps and IP maps: comparative analysis of optical engines, beam technologies, and patterning software stacks, plus a patent landscaping exercise indicating where freedom-to-operate and blocking IP reside.
-
Vendor scorecards and partner matrices: decision-ready evaluations of machine suppliers based on throughput, resolution, footprint, modularity, and lifecycle cost — enabling rapid shortlisting for pilots and procurement.
-
Operational templates: CAPEX/OPEX calculators, floor-space and utilities modeling for 300/200/150 mm integration, and quality-compliance checklists for FDA/ISO qualification paths.
-
M&A and investment radar: prioritized target lists and value-creation scenarios for tuck-ins, capability buys, or joint ventures aligned to three strategic pathways — scale, specialize, or software-led differentiation.
-
Primary intelligence appendices: annotated interviews with equipment OEMs, foundry adopters, materials suppliers, DMD vendors, and standards bodies, together with trade-show verification and patent citation chains.
Competitive Landscape — Who Matters and What They Bring
The report profiles the full range of incumbent and challenger firms shaping the market: global laser lithography specialists, high-resolution electron-beam vendors, DMD-based system manufacturers, and compact tabletop providers for lab-scale work. Key players include established OEMs that bring high-precision laser and direct-write platforms, suppliers pushing high-throughput maskless exposure tailored for advanced packaging, and a cohort of niche firms delivering table-top and grayscale capabilities for photonics and microfluidics.
From a strategic vantage point:
- Leaders with high-precision direct-write portfolios are best positioned to protect premium R&D and production niches but face pressure to scale throughput.
- Vendors investing in DMD/optics partnerships and roll-to-roll integrations are the most likely to displace masked flows in flexible-electronics and some advanced-packaging segments.
- Smaller, nimble vendors excel in rapid prototyping, specialized microfabrication, and research markets — making them attractive acquisition targets for larger OEMs seeking to broaden product stacks quickly.
Market concentration metrics in the report quantify this competitive reality and show meaningful incumbency among top manufacturers while leaving room for disruptive entrants and targeted consolidation.
Recent Industry Signals You Must Act On
-
New high-pixel-count DMDs and optics announced by component suppliers materially change throughput economics — creating a clear technology adoption pathway for maskless systems in tighter-tolerance production domains.
-
Major OEMs are transitioning from demonstration to commercialization platforms: co-creation facilities and trade-show deployments reflect shortened lead times from lab to factory.
-
Product upgrades among leading direct-write suppliers underscore a near-term product refresh cycle. Buyers and partners should anticipate hardware and software versioning implications for qualification windows in 2026–2027.
-
Regulatory and standards developments can add lead time to qualification and customer acceptance; proactive compliance roadmaps reduce time-to-revenue risk.
Five Strategic Moves for 2026
-
Prioritize integration pilots where maskless systems complement existing masked flows rather than attempting wholesale replacement. Focus pilot selection on high-margin, short-feedback applications (e.g., advanced packaging and flexible-device sub-runs).
-
Lock in critical optics and DMD supply lines now. Component lead times and node-specific performance will determine throughput ceilings; supplier agreements should include roadmap commitments and supply guarantees.
-
Invest in the software-data axis. The highest commercial leverage lies in patterning pipelines — compression, error correction, and adaptive exposure control are differentiators that shift TCO in your favor.
-
Pursue modular solutions and service-led business models. Machines with modular upgrades and strong service ecosystems lower buyer risk and open recurring revenue opportunities.
-
Use M&A to acquire capability fast. Identify small-to-mid-sized innovators in grayscale lithography, microfluidics patterning, or high-precision direct-write as tuck-in targets to accelerate roadmap delivery.
Risk Profile and Mitigation
Key risks include component supply cyclicality (particularly DMDs and high-spec optics), standards-induced qualification delays, and the perennial tension between throughput and resolution. The report provides a quantified risk matrix linking each risk to revenue impact scenarios and prescribes mitigations — for example, multi-sourcing strategies, staged qualification approaches, and insurance-like service agreements to protect early adopters.
How to Use This Report in Your 2026 Planning Cycle
Procurement teams should pair the report’s vendor scorecards with 12–18 month pilot timetables to ensure equipment qualification aligns with product launches. R&D and product leaders will find the technology roadmaps and IP landscapes essential for prioritizing internal programs versus sourcing external capabilities. Finance and corporate development functions will benefit from the scenario-driven valuation models when allocating capital between greenfield fabs, co-development partnerships, and M&A.
Closing — A Strategic Teaser
Maskless lithography is no longer a pure R&D curiosity; it is a maturing set of technologies creating practical options for companies that need faster design iteration, lower tooling risk, and new form-factor production capability. PW Consulting’s report combines rigorous market sizing (base year 2025), an 8.76% CAGR projection across 2026–2032, vendor concentration analysis, and operation-ready playbooks to make 2026 procurement, investment, and partnership decisions less risky and more opportunistic.
To access the full dataset, vendor scorecards, and the actionable annexes that contain the granular segmentation and financial models reserved for report subscribers, please consult the official PW Consulting distribution channels. The full report includes the detailed splits and appendices that underpin the strategic recommendations summarized here.
PW Consulting — Senior Strategic Advisor & Chief Industry Analyst
For detailed analysis of this topic, please visit the official page: Worldwide Maskless Lithography Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com