

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Outdoor Industrial Water Storage Tank Market Poised to Reach USD 5,014.9 Million by 2032 at a 5.48% CAGR

Worldwide Outdoor Industrial Water Storage Tank Market: Strategic Preview for 2026 Decision‑Makers
PW Consulting is pleased to release an executive preview of our upcoming Worldwide Outdoor Industrial Water Storage Tank Market study. As organizations operationalizing capital projects and global water stewardship plans plan for 2026, this briefing synthesizes the report’s most consequential strategic takeaways—demonstrating how the market’s macro trajectory, competitive dynamics, regulatory drivers, and materials economics should shape procurement, manufacturing, and project‑finance decisions next year.
Worldwide Outdoor Industrial Water Storage Tank Market
High‑level market trajectory: a resilient, mid‑single‑digit growth story
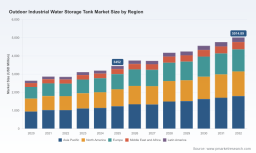
The outdoor industrial water storage tank market has recorded steady expansion across the 2020–2025 baseline and is projected to continue its upward trajectory into the 2026–2032 forecast window. Our analysis shows the market reached approximately USD 3.45 Billion (Revenue Unit: Million USD) in the base year 2025 and is forecast to expand at a compound annual growth rate (CAGR) of 5.48% over the 2026–2032 period, approaching an estimated USD 5.01 Billion by 2032.
Worldwide Outdoor Industrial Water Storage Tank Market
For executives, two implications emerge immediately. First, capacity planning and supplier selection should be informed by a market that is growing but not hyper‑consolidating—demand is sufficient to support strategic investments yet remains distributed across many projects and end‑use sectors. Second, a predictable growth profile creates an environment where targeted product and service differentiation (for durability, speed of installation, or low lifecycle O&M) can readily translate into outsized commercial returns.
Worldwide Outdoor Industrial Water Storage Tank Market
What the full PW Consulting report includes (practical, transaction‑ready content)
-
Actionable financial models calibrated to 2020–2025 historical performance and 2026–2032 forecasts, enabling scenario analysis for capex, payback and NPV under alternative material, installation and maintenance strategies.
-
Decision‑grade procurement playbooks for owner‑operators, EPCs and large industrial buyers that cover contracting models (turnkey vs. modular supply), risk allocation, warranty negotiation points, and certified‑material requirements for potable and industrial water applications.
-
A supplier due‑diligence framework that operationalizes technical and commercial criteria—manufacturing footprint, coating systems and standards compliance, warranty strings, proven install base, and spare‑parts logistics—so buyers can convert insight into RFP language.
-
Project deployment templates that reduce schedule risk (prefab vs. field assembly), quantify labor and lifting equipment needs, and benchmark installation timeframes for comparative tender evaluation.
-
Regulatory and standards compendium tailored to cross‑jurisdictional projects, highlighting compliance pathways for potable water certification, interior coating specifications, and prestressed concrete design codes.
-
Risk matrices and mitigation playbooks for raw material volatility, regulatory change, and extreme‑weather resilience—designed to be embedded in CAPEX approval packages.
Competitive landscape: fragmentation, specialized leaders, and the path to commercial differentiation
The market remains fragmented: the three largest suppliers account for under one‑fifth of global share, and the top five suppliers represent just over a quarter. This structure—a CR3 of 18.45% and a CR5 of 27.12%—creates space for regional champions and technologically differentiated entrants to win significant project share without confronting dominant global incumbents.
-
FORGE Global Tanks (Katy, TX) combines in‑house engineering and a strong installed‑base narrative for bolted steel solutions. Their AWWA/NFPA/Eurocode‑aligned coatings and end‑to‑end delivery model are well suited to owners seeking single‑vendor accountability for medium to large projects.
-
CST Industries leverages factory‑applied glass‑fused and epoxy systems that target low life‑cycle maintenance—an attractive positioning for municipal and industrial buyers prioritizing TCO over lowest initial price.
-
SBS Tanks (SBS Group) and other regional modular steel specialists have demonstrated how standardized, ISO‑driven manufacturing practices enable rapid deployment in mining and remote industrial settings.
-
DN Tanks, CROM Corporation and other prestressed concrete specialists maintain strength in very large, long‑durability applications where lifecycle stiffness and corrosion resistance are paramount.
-
Polyethylene and poly‑lined offerings from manufacturers such as Aquamate and recent capacity expansions observed among polyethylene suppliers broaden options where ultraviolet resistance, cost competitiveness and short lead times matter.
For strategic buyers and investors, the practical takeaway is threefold: (1) procurement should match technology to lifecycle objectives rather than presume one material class is “best,” (2) local manufacturing and installation capability remains a decisive differentiator in reducing schedule and logistics risk, and (3) focused supplier development (coatings, liners, modular design) is where incumbents and new entrants can capture premium margins.
Market dynamics shaping procurement and CAPEX in 2026
-
Raw material volatility: Steel and polymer price dynamics materially impact relative unit economics between steel, concrete and polyethylene solutions. For context, steel pricing in the United States averaged about USD 885 per metric ton in mid‑2025, while HDPE resin benchmarks in Europe rose toward USD 1,200 per metric ton later that year. Buyers should integrate sensitivity runs on key raw material indices into capex approvals and consider hedging strategies where feasible.
-
Standards and potable‑water certification: Certification regimes such as NSF/ANSI/CAN 61 and AWWA standards (including AWWA D102 and D110 variants that address coatings and prestressed concrete) are increasingly enforced by owners and financiers. Non‑compliance risks both project delays and long‑term liability; certification status must therefore be a minimum pass/fail criterion in technical evaluation.
-
Installation productivity and modularization: Product design advances—such as bolted designs that reduce installation time by multiple weeks—translate directly into lower mobilization and downtime costs. Our market scoring shows that faster‑to‑install modular systems are being selected more frequently when the value of avoided downtime exceeds the small premium for prefabrication.
-
Application diversification: Industrial buyers are re‑balancing storage needs across wastewater, fire protection, chemical processing and process water. While each application imposes distinct material and coating requirements, integrated suppliers that can manage multiple certifications and service agreements command pricing leverage.
Recent development signals to watch in 2026
-
Capacity shifts in polyethylene: Expansions and UV‑stabilized product introductions among polymer suppliers indicate increasing competitiveness of synthetic tanks for outdoor use where sunlight exposure and durability were previously constraints.
-
Design productivity: Bolted tank design updates that materially shorten installation time are changing the procurement calculus—projects with constrained site access or tight schedules are particularly affected.
-
Large civil projects: Recent completions of large reinforced concrete tanks underscore the sustained demand for high‑volume, long‑life civil solutions, especially in municipally funded treatment and storage projects.
Strategic recommendations for 2026 decision cycles
-
Run material‑agnostic, lifecycle total‑cost analyses. Move beyond first‑cost procurement to models that quantify maintenance, coating re‑application cycles, and downtime impacts over 20–30 year horizons.
-
Embed standards compliance as a gating criterion in RFPs and contract milestones. Require certification documentation up front and link milestone payments to compliance verification.
-
Pursue supply‑chain redundancy for critical coatings and liners. Given raw material price swings and regional supply constraints, dual‑sourcing or pre‑procurement of long‑lead coating systems reduces schedule risk.
-
Prioritize suppliers with proven modular and rapid‑install capability for projects with time‑sensitive commissioning windows; quantify time‑to‑first‑service as a decision metric alongside CapEx.
-
Consider staged capex with option clauses to expand capacity or retrofit lining systems—this hedges against uncertainty in material pricing and regulatory evolution.
Why PW Consulting’s full report is a 2026 strategic asset
Our full study goes beyond headline growth numbers to provide transaction‑ready tools: contractual templates, supplier scorecards, CAPEX/OPEX model workbooks, and a granular risk register mapped to mitigation actions. The preview you are reading offers the directional intelligence required to frame 2026 budgets; the full report supplies the executable playbooks procurement teams and project sponsors need to act decisively.
Next steps
Organizations preparing 2026 budgets or large water infrastructure projects should request PW Consulting’s full report and associated modeling pack. The complete deliverable contains the detailed segmentation analysis, comprehensive supplier profiles, and downloadable financial models that senior leaders and project teams need to convert market insight into lower‑risk, higher‑value outcomes. For those who prefer an interactive briefing, our senior analysts are available to walk through scenario runs and supplier shortlists tailored to specific project geographies and application requirements.
PW Consulting remains committed to translating market intelligence into operational advantage. Contact our research team to schedule a briefing and to learn how the full Worldwide Outdoor Industrial Water Storage Tank Market report can be integrated into 2026 decision workflows.
For detailed analysis of this topic, please visit the official page: Worldwide Outdoor Industrial Water Storage Tank Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com