

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Mini Tractors Market Set to Expand at 5.5% CAGR, Reaching USD 20.75 Billion by 2032

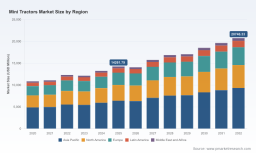
Worldwide Mini Tractors Market: Strategic Signals for 2026 Decision-Making
As PW Consulting releases its latest Worldwide Mini Tractors Market study (base year 2025, forecast 2026–2032), corporate leaders, product strategists, and M&A teams must re-evaluate plans against a market that is stabilizing after uneven growth and entering a structurally higher trajectory. Our proprietary analysis synthesizes historical performance (2020–2025), near-term corrections, and a multi-year forecast anchored by a 5.5% compound annual growth rate (CAGR) across the 2026–2032 horizon — delivering the actionable intelligence required to make decisive moves in 2026.
Worldwide Mini Tractors Market
Why this report matters for 2026
-
Macro clarity at a pivotal juncture — The mini tractor market reached a clear inflection in 2025. Our full-model forecasts map a short-term correction followed by a sustained recovery that drives the market into a new, larger scale by the end of the forecast window. Leaders who align product, channel, and capital allocation in early 2026 will capture outsized returns as demand normalizes and structural adoption accelerates.
Worldwide Mini Tractors Market -
Precision for resource allocation — With compressed development cycles and rising regulatory complexity, companies need targeted scenarios that quantify design, compliance, and production trade-offs. The report translates macro trends into capital planning and product roadmap implications tailored to OEMs, suppliers, and financiers.
Worldwide Mini Tractors Market -
Playbooks — Beyond forecasting, we deliver executable playbooks for market entry, portfolio optimization, and channel economics to shorten time-to-profit for new models and regional expansions.
Market trajectory: what the headline numbers reveal
Our market model shows the worldwide mini tractors market consolidating to a new baseline in 2025, followed by a near-term adjustment in 2026 and a steady compound annual growth rate of 5.5% through 2032. By the end of the forecast period, the global market moves materially higher compared with the 2025 base, reflecting sustained mechanization in agriculture, renewed investments in landscaping and urban utility applications, and incremental replacement demand.
For decision-makers, the practical implication is twofold: (1) margin recovery and network optimization will matter as aftermarket and parts revenue streams scale with installed bases, and (2) the timing of capex and product launches becomes a differentiator — launching into the upswing versus the correction materially affects ROI horizons.
Practical content inside the report
-
Dynamic demand scenarios: interactive demand curves keyed to commodity cycles, subsidy regimes, and infrastructure spending. These scenarios enable CFOs and business unit heads to stress-test revenue and cashflow under alternative macro outcomes.
-
Policy and regulation impact matrices: quantified cost-and-time impacts of emission standards and trade measures on engine platforms and module sourcing strategies. This includes engineering cost estimates and supplier qualification timelines tied to the most consequential regulatory regimes.
-
Supply-chain risk heatmaps: supplier concentration, critical raw-material exposure (notably high-strength steel and specialty alloys), tariff sensitivities, and mitigation levers (dual sourcing, nearshoring, design for alternative materials).
-
Commercial playbooks: go-to-market frameworks for OEMs and distributors covering pricing, financing structures, trade-in programs, and localized aftersales models that improve lifetime value.
-
M&A and partnership screening: a ranked pipeline of target archetypes, integration checklists, and valuation heuristics appropriate to buyers focused on scale, capability acquisition, or channel consolidation.
Competitive landscape — what separates winners from the rest
The mini tractors market remains dominated by established OEMs with deep channel networks, broad product families, and global manufacturing footprints. Key players that shape industry dynamics include John Deere (Moline, Illinois, USA), Kubota Corporation (Osaka, Japan), Mahindra & Mahindra (Mumbai, India), TYM (Tong Yang Moolsan, South Korea), LS Tractor (LS Mtron, South Korea), Kioti Tractor (Daedong, South Korea), Yanmar (Osaka, Japan), CNH Industrial / New Holland (UK/Italy), AGCO / Massey Ferguson (USA), and VST Tillers Tractors Ltd (India).
Across this competitive set, success factors are converging on a few high-leverage capabilities:
-
Localized cost-to-serve optimization — Manufacturers that combine modular platforms with regional localization of key subassemblies win on price without sacrificing reliability.
-
Aftermarket and financing — Integrated finance offers and strong parts networks materially increase uptake among smaller farms and non-agricultural buyers.
-
Compliance and engineering depth — Meeting tighter emission standards requires investment in engine technologies and after-treatment systems, advantaging firms with in-house powertrain expertise or strong partnerships.
-
Product ergonomics and operator value — Comfort, safety, and ease-of-use increasingly influence purchase decisions in landscaping, horticulture, and smallholder contexts.
Recent product movements underscore these dynamics: Kubota launched an operator-focused Grand L70 series in late 2025; VST rolled out FENTM compact tractors for small and mid-sized farms in 2025; Massey Ferguson introduced upgrades to its utility line targeting comfort and efficiency; and LS Mtron expanded its North American compact tractor range earlier in 2025. These introductions signal an industry emphasis on operator experience, fuel efficiency, and platform versatility.
Regulation, raw materials, and policy — the hidden drivers
Regulatory developments and raw-material volatility are not peripheral risks — they are primary determinants of product architecture and cost. The EU Stage V emissions requirements impose more sophisticated injection and after-treatment solutions on compact tractors, raising engineering and production costs that cascade through supplier agreements and pricing strategies. At the same time, fluctuations in high-strength steel and specialized alloy prices directly affect chassis and axle manufacturing economics, and tariff regimes (including certain steel and component levies) continue to shape sourcing choices in key markets.
On the demand side, national subsidy and credit programs remain powerful accelerants for adoption. For example, recent allocations in India to support farm mechanization materially improve access to finance for smallholders and shift purchase timing — a vector that global OEMs must incorporate into regional go-to-market plans.
Strategic recommendations for 2026
-
Prioritize platform modularity and options portfolios. Invest in modular chassis and powertrain architectures that allow rapid region-specific adaptations without full redesigns.
-
Lock in strategic suppliers and hedging arrangements for critical metals and alloy inputs. Short-term price swings can erode margins faster than demand shocks.
-
Embed financing and aftersales at launch. Bundling financing and predictable maintenance offerings increases conversion and reduces churn among first-time mechanization buyers.
-
Target product launches to the early phase of projected recovery windows. Timing new model introductions to pre-empt market resupply cycles yields superior market share gains.
-
Use M&A selectively to buy capabilities — not just scale. Target acquisitions that add emission-compliant powertrain tech, telematics, or distribution density rather than only revenue lifts.
Scenario planning — what to prepare for
Our scenario suite includes a baseline that assumes steady policy support and manageable raw-material inflation, a downside where protectionist trade measures and accelerated material cost increases compress margins, and an upside driven by faster-than-expected smallholder mechanization and urban landscaping demand. Each scenario includes discrete triggers and timelines tied to capital allocation recommendations so that executives can convert insight into quarterly actions.
What the report does not give away — and why that matters
Consistent with PW Consulting’s “trailer” approach, this release demonstrates the analytical depth and strategic prism used to produce the study while deliberately omitting granular segmentation tables and region/application-specific financials that form the core, proprietary deliverables. Those datasets — including our full model outputs, regional demand curves, and high-resolution price-elasticity matrices — are central to tactical decisions such as SKU rationalization, plant footprint shifts, and targeted dealer incentives. They are available through our report portal for clients who require the full evidence base to execute with precision.
Next steps and how to access the full intelligence
Leaders who require detailed scenario models, market-by-region and application breakouts, supplier-level risk assessments, and the full competitive database (including detailed product mappings and recent developments) should consult the complete Worldwide Mini Tractors Market report (base year 2025). The report provides the exact numerical matrices and downloadable model files that underpin the strategic recommendations summarized here.
For executives preparing budgets and product roadmaps in early 2026, the window to align launches, finance programs, and supply-chain interventions to the market’s next upswing is narrow. PW Consulting’s detailed datasets and execution checklists are designed to convert foresight into measurable business outcomes.
Contact PW Consulting or visit our report page to request an executive briefing, obtain sample model outputs, or arrange a custom deep-dive tailored to your organization’s position in the mini tractors value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Mini Tractors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com