

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Body Comfort System Market Reaches USD 100.26 Billion in 2025; Set to Expand at 7.11% CAGR to USD 162.19 Billion by 2032

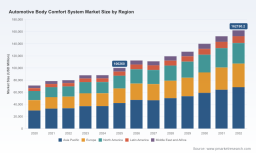
Worldwide Automotive Body Comfort System Market — Strategic Outlook for 2026 Decisions
PW Consulting’s latest market study on the Worldwide Automotive Body Comfort System market establishes a clear, actionable foundation for corporate strategy in 2026. Using 2025 as the base year and a consistent historical window (2020–2025), the report quantifies an upswing from roughly USD 71.2 billion in 2020 to about USD 100.3 billion in 2025. Looking ahead, our 2026–2032 forecast models a compound annual growth rate (CAGR) of 7.11%, projecting the market to surpass USD 162.2 billion by 2032. These headline figures set the stage for a deeper, operationally focused discussion about where leadership and investment must land in the coming 12–18 months.
Worldwide Automotive Body Comfort System Market
Why this report matters for 2026 decision cycles
- Prioritizing R&D and product roadmaps: The growth profile and technology tailwinds identified in the study help OEMs and Tier‑1s prioritize development of thermal comfort, active seating, and sensor‑enabled occupant monitoring features that will meaningfully differentiate next‑generation vehicles.
- Strategic sourcing and supplier selection: The report arms procurement and sourcing teams with supplier scorecards, technology fit analyses, and risk indexes so they can rationalize vendor portfolios and negotiate from informed positions.
- M&A and partnership screening: Investors and corporate development teams receive a short list of capabilities that will unlock near‑term value (software platforms, domain controllers, low‑power communications, precision actuators) together with scenario analyses for consolidation plays.
- Regulatory and compliance planning: We map regulatory triggers—particularly those impacting occupant monitoring and electronics architectures—to product release schedules and certification milestones to avoid costly rework.
- Sustainability and materials transition: The report offers material substitution pathways and cost impact models tied to industry targets for recycled and renewable plastics, enabling procurement and engineering to operationalize sustainability goals without margin erosion.
Data-driven signals: what the numbers reveal (and what they intentionally leave to the report)
At headline scale, the market’s steady compound growth through 2032 is not uniform; it is being driven by a convergence of structural and tactical forces. Electrification increases the importance of HVAC and seat thermal management as battery‑powered vehicles reshape load management and comfort‑energy tradeoffs. Software‑defined vehicle architectures are creating new monetization vectors for comfort features (OTA updates, feature‑as‑a‑service), while new in‑cab sensors and control units turn what were mechanical features into software and electronics plays.
Worldwide Automotive Body Comfort System Market
Regulatory and standards developments are amplifying integration complexity. For example, the EU General Safety Regulation’s emphasis on Driver Monitoring Systems is accelerating the embedding of occupant monitoring functions into broader body and comfort electronics architectures. Likewise, next‑generation communications and transceiver standards (e.g., CAN FD SIC implementations aligned to the latest ISO edition) are enabling lower‑power modes and richer in‑vehicle sensor fabrics, which in turn influence module architecture and supplier selection.
Worldwide Automotive Body Comfort System Market
Material supply and sustainability targets are another near‑term focus. OEMs and suppliers are pushing to increase recycled and renewable plastics in interior trim and comfort components—programs we model explicitly to show both cost delta and carbon benefit across alternative sourcing scenarios. Taken together, these forces create both upside opportunities (new features, higher ASPs for software‑enabled comfort) and risks (component lead times, raw material price volatility, regulatory rework).
Competitive landscape — strengths, gaps and strategic moves
The market remains competitive but not hyper‑concentrated. Our concentration metrics indicate a market in which the top three players account for roughly one‑third of global share, and the top five approach the mid‑40s percentage range—enough scale for incumbents to influence standards and supply chains, but also enough fragmentation to enable specialist challengers and vertical integrators.
- Gentherm (United States): A specialist in seat thermal management and active cooling, Gentherm’s strong IP base in thermal comfort positions it well for OEM programs seeking differentiated HVAC/seat bundles. Expect continued investment in thermoelectric and active cooling modules and in licensing arrangements for platformized thermal systems.
- Lear Corporation (United States): Lear’s complete seating systems and integration capability—combining mechanical architectures with electronics for massage, lumbar and dynamic adjust—make it a natural partner for OEMs seeking turnkey seating solutions. The company’s scale supports system‑level integration and margin capture on electrical architectures.
- Adient plc (Ireland): Adient has doubled down on ergonomic and safety‑linked comfort features, releasing new seating solutions that integrate safety pretensioners and smart airbags. Their August 2025 product introduction highlights a strategy that blends occupant protection with comfort as a combined differentiation vector.
- FORVIA (Faurecia), Magna, Continental, Bosch, Denso, Valeo: These diversified Tier‑1s leverage broad portfolios—seat systems, HVAC, body electronics, and sensing—to offer integrated packages that align with OEM consolidation strategies. Their advantage lies in systems integration, global manufacturing footprint, and relationships across powertrain and electronics domains.
- Toyota Boshoku, Kongsberg, Alfmeier Präzision: These players bring focused capabilities—precision actuators, pneumatic components, and seat manufacturing expertise—that are critical to modular architectures and cost optimization strategies.
Recent industry commentary underscores strategic urgency. A March 2026 BCG industry study highlighted interior and body systems as high‑leverage areas for OEM differentiation, reinforcing the timing for investment decisions. Against this backdrop, the market’s concentration dynamics suggest acquisition opportunities for firms seeking either to add software/electronics capability or to broaden product portfolios into adjacent comfort domains.
What the report contains — practical, executable deliverables
- Validated market sizing & scenario‑based forecasts: A baseline and three alternate scenarios (conservative, base, upside) for 2026–2032 with sensitivity to EV penetration, regulatory timing and material price shocks.
- Supplier & capability heatmaps: Comparative profiles across electrical control units, actuators, sensors, and thermal systems covering technology readiness, margin bands, IP ownership and partnership fit.
- Technology and architecture playbooks: Recommended reference architectures for body control and comfort subsystems, including CAN FD/ethernet edge tradeoffs, domain controller partitioning and software update paths.
- Cost and materials models: Bottom‑up BOM and cost‑to‑serve models, plus scenarios for recycled‑content adoption and alternate sourcing strategies that show total landed cost and CO2 implications.
- Regulatory impact matrices: Time‑phased maps linking regulations and standards to required product features, testing regimes, and certification windows.
- Commercial & go‑to‑market frameworks: Pricing strategies for feature bundles (hardware + software), subscription monetization options, and channel strategies for Tier‑1/OEM partnerships.
- Actionable M&A signal lists: Capability gaps where targeted acquisitions would improve time‑to‑market, plus diligence checklists aligned to performance and technology metrics.
To honor the “trailer” principle and preserve the strategic value of our granular analyses, detailed regional and application splits, supplier share tables, and per‑segment revenue figures are reserved for the full report and bespoke client deliverables.
How executives can act in 2026 — six prioritized moves
- Rebase product roadmaps on software and systems integration: Reallocate R&D budgets to control software stacks, OTA capability and domain controllers that host comfort features, rather than only on mechanical upgrades.
- Hedge supply risk with dual‑sourcing and localized content: Identify single‑sourced precision components and secure secondary suppliers or near‑shore capacity for critical actuators and control modules.
- Embed sustainability targets into sourcing contracts: Negotiate recycled‑content clauses and long‑term offtake agreements to smooth price and certification risks tied to polymer supply.
- Accelerate partnerships for occupant sensing: Integrate driver/occupant monitoring early with body electronics roadmaps to meet regulatory windows and to unlock occupant‑aware comfort features.
- Use M&A to fill software/electronics gaps: Target small‑to‑mid cap specialists with proven domain controller IP or sensor fusion stacks to compress time‑to‑market for higher‑margin software services.
- Operationalize cost‑to‑feature tradeoffs: Use our BOM models to assess where premium comfort features can be adopted with minimal margin impact (e.g., modularizing heating and ventilation across vehicle platforms).
Final note — how PW Consulting’s intelligence translates into decisions
For 2026 planning cycles, the combination of validated headline market growth (a multiyear compound expansion at ~7.11% CAGR), regulatory accelerants, and technology inflection points makes the body comfort domain a high‑priority investment area. Executives who align product roadmaps, supplier strategies and M&A activity to the signals in this study will create disproportionate optionality: from new revenue streams enabled by software to lower operational risk through smarter sourcing.
PW Consulting’s full report contains the granular segmentation, regional and application detail, and supplier share tables required to operationalize these recommendations. Clients who need immediate decision support can request tailored briefings, scenario workshops, and due diligence packages that map directly to program timelines and capital allocation cycles for 2026.
For access to the complete dataset, supplemental models, and to schedule a strategic briefing, please refer to the PW Consulting report page or contact our Automotive Practice team.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Body Comfort System Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com