

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Aliphatic Polysulfide Market to Expand at a 4.89% CAGR During 2026–2032

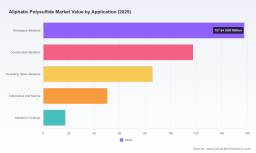
Worldwide Aliphatic Polysulfide Market — Strategic Preview for 2026 Decision-Makers
Executive summary
PW Consulting's latest Worldwide Aliphatic Polysulfide Market report (base year 2025, forecast 2026–2032) distills the market forces that will shape capital allocation, product development and go-to-market decisions for the coming cycle. The aliphatic polysulfide market has demonstrated steady recovery and resilience through 2020–2025, with total market revenue rising from the low‑hundreds of millions to USD 428.8 Million in 2025. Our forward view estimates a compound annual growth rate (CAGR) of 4.89% for 2026–2032, projecting a global market approaching USD 599 Million by 2032. For executives planning 2026 investments, this report is designed as a tactical playbook: it identifies value pools, supply‑chain inflection points, regulatory crosswinds, and competitor moves — and translates them into near‑term actions that preserve optionality while accelerating return on invested capital.
Worldwide Aliphatic Polysulfide Market
Why this market matters in 2026
Aliphatic polysulfides occupy a niche but strategically important role where chemical resistance, low permeability and long-term flexibility are critical — from aerospace fuel tank sealants to specialty construction applications and insulating glass. The credibly predictable mid‑single digit CAGR masks meaningful pockets of re‑rating driven by regulatory substitution, formulation innovation and supply‑side consolidation. The market concentration is material: the top three and top five global players command a dominant share of supply, underscoring the strategic importance of partnership, capacity planning and differentiated product strategies for new entrants and incumbents alike.
Worldwide Aliphatic Polysulfide Market
Market trajectory and what it means for 2026 planning
-
Historical momentum and near‑term outlook: After a volatile 2020–2022 period, the market stabilized and expanded to USD 428.8 Million in 2025. Our base‑case scenario projects growth at roughly 4.9% annually across the 2026–2032 horizon, reaching nearly USD 599 Million by 2032.
Worldwide Aliphatic Polysulfide Market -
Investment horizons: For corporate strategists, the implication is clear — the market is large enough to justify targeted R&D and process investments, yet concentrated enough that scale and channel relationships will determine commercial success.
-
Timing and optionality: 2026 represents a window to lock in feedstock contracts, advance regulatory‑compliant formulations and pilot higher‑performance aliphatic grades that address specific end‑use pain points (e.g., improved chemical resistance at low temperatures, or epoxy‑terminated offerings for coatings and adhesives).
Dynamics reshaping the competitive landscape
Three dynamics deserve elevated attention in 2026 corporate planning: raw material volatility and regional feedstock asymmetries; regulatory substitution and environmental compliance; and differentiated product launches from leading suppliers.
-
Raw material dynamics: Ethylene dichloride (EDC), a key precursor in aliphatic polysulfide manufacture, shows meaningful regional price dispersion that alters feedstock economics and localized competitiveness. As of Q4 2025 market checks, EDC prices were materially lower in North America relative to key Asian and European markets. These disparities influence sourcing strategies, incremental margin by plant location and the arithmetic of new capacity investments.
-
Regulatory substitution: Ongoing restrictions on legacy lead‑based curing agents across RoHS and REACH jurisdictions — and the practical dominance of manganese dioxide‑cured systems in many advanced markets — are shifting formulation roadmaps. Companies that can accelerate lead‑free curing chemistries and demonstrate compliance under evolving effluent and waste standards will secure privileged access to aerospace, construction and glass OEM supply chains.
-
Environmental and discharge standards: U.S. EPA guidance under 40 CFR Part 414 continues to frame capital outlays for treatment and pretreatment in facilities handling organic chemicals and related processes. Anticipating these compliance costs is a non‑trivial component of new project economics and M&A diligence in 2026.
Competitive picture — capabilities, moves and implications
The market is characterized by a small set of technically sophisticated producers and several regional players that serve localized demand patterns. Key profiles and strategic implications include:
-
Nouryon: As the most prominent global producer of liquid polysulfide polymers under the Thioplast® umbrella, Nouryon's recent introduction of an epoxy‑terminated aliphatic grade designed specifically for harsh environments signals a deliberate pivot up the value chain. For competitors and customers alike, this accentuates the importance of formulation partnerships and co‑development agreements that can leverage the enhanced chemical resistance and low‑temperature flexibility of next‑generation aliphatic grades.
-
Toray Fine Chemicals: The sole Japanese manufacturer of polysulfide polymers offers mercaptan‑terminated base polymers that remain integral to high‑performance sealants in construction and civil engineering. Toray's positioning underscores the relevance of reliable domestic supply for geographies with elevated import risk and the premium buyers are willing to pay for regional sourcing, traceability and tailored technical support.
-
Kazan Synthetic Rubber Plant (KSRP): A major producer with a diversified customer base, KSRP emphasizes chemical‑resistant elastomers and demonstrates how regional players defend niches by optimizing cost‑to‑performance tradeoffs. For multinationals evaluating entry or expansion, regional incumbents offer lessons in pricing, distribution and technical service models that win in cost‑sensitive segments.
-
PPG Industries (PRC‑DeSoto): PPG’s application‑focused polysulfide formulations for aerospace highlight a recurring strategic theme: high‑margin, specification‑driven applications (aerospace sealants, fuel‑system components) remain the most defensible revenue streams. Partnerships with OEMs, rigorous qualification cycles and proven supply reliability are barriers to entry that favor incumbent suppliers.
What the report contains — practical, transaction‑ready intelligence
PW Consulting’s report is structured to inform decisions across commercial, technical and corporate functions without requiring readers to wade through raw data dumps. Highlights include:
-
Market sizing and scenario forecasts (2026–2032) with sensitivity analyses that isolate the impact of feedstock shocks, regulatory tightening and demand shifts in key end uses.
-
Supply‑chain risk maps and sourcing playbooks that quantify the tradeoffs of regional production footprints under realistic feedstock pricing and permit regimes.
-
Competitor profiles and capability matrices that go beyond product catalogs to assess technical service, qualification lead times, and aftermarket support — the intangible assets that translate to higher win rates in specification‑driven markets.
-
Regulatory and environmental compliance checklists tailored for plant operations, R&D laboratories and commercial teams to streamline permit planning and minimize time‑to‑qualification for lead‑free curing systems.
-
M&A and JV decision frameworks including valuation sensitivities tied to concentration metrics and barriers to entry — essential for boards and corporate development teams considering bolt‑on acquisitions in 2026.
Actionable recommendations for 2026
Based on our analysis, PW Consulting recommends a prioritized set of actions for companies with exposure to aliphatic polysulfides:
-
De‑risk feedstock exposure: Negotiate multi‑year EDC contracts with price collars or pursue integrated procurement arrangements where feasible. For firms evaluating greenfield capacity, model scenarios using region‑specific EDC economics and include EPA compliance capex in early stage NPV runs.
-
Accelerate lead‑free formulation roadmaps: Convert R&D roadmaps into qualification pipelines with target OEMs. Early demonstration of manganese dioxide‑cured systems or alternative curing agents will be a decisive commercial advantage, particularly in RoHS/REACH jurisdictions.
-
Prioritize specifications over commodities: Move up the value chain by developing formulation IP for demanding end uses (aerospace, insulating glass) and align commercial incentives with aftermarket service and qualification support.
-
Use concentration dynamics strategically: For smaller suppliers, consider capacity consolidation or selective partnerships with incumbent global manufacturers to broaden market access. For larger firms, evaluate bolt‑on acquisitions to secure feedstock access and shorten qualification cycles.
-
Embed regulatory cost into pricing models: Ensure that sales and commercial teams understand the capital and operating costs of effluent control and chemical‑handling compliance — these are no longer peripheral but core to margin management.
How to use this intelligence in boardroom deliberations
An effective 2026 board deck should separate three decision layers: (1) short‑term supply and contract actions to stabilize margins over the next 12 months; (2) medium‑term product and qualification investments to capture high‑value segments; and (3) long‑term portfolio moves including M&A and vertical integration. PW Consulting’s report supplies the data templates, risk matrices and scenario outputs that map directly to these decision gates, enabling CFOs and strategy leaders to translate market outlooks into executable commitments.
Conclusion — the strategic dividend of focused insight
The aliphatic polysulfide market is neither explosive nor stagnant; it is a measured growth market with concentrated supply and substantial regulatory and feedstock‑driven inflection points. For 2026, the most valuable corporate responses will be those that convert regulatory pressure and feedstock dispersion into competitive advantage — through lead‑free formulations, disciplined sourcing strategies and specification‑led commercialization. PW Consulting’s Worldwide Aliphatic Polysulfide Market report provides the practical, transaction‑ready intelligence to make those calls with confidence.
Call to action
This release is intended as a strategic preview. For full segment‑level analysis, granular regional forecasts, supplier benchmarking, and the complete set of operational playbooks and financial models referenced above, please consult the full PW Consulting Worldwide Aliphatic Polysulfide Market report. Access to the complete dataset and model templates will enable teams to run bespoke scenarios tailored to their cost base, product mix and investment horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Aliphatic Polysulfide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com