

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Oblong Jar Market to Expand at a 5.85% CAGR During 2026–2032, New Report Finds

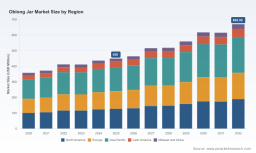
Worldwide Oblong Jar Market — Strategic Preview for 2026 Decision Makers
PW Consulting’s newest market study on the Worldwide Oblong Jar Market (base year 2025) delivers an actionable intelligence package for senior executives, corporate strategists, and investment committees preparing plans and capital allocations in 2026. The market has demonstrated steady expansion through the recent cycle and—based on our scenario modelling—enters the 2026 decision window with a clear, investible trajectory: after rising from the early‑2020s level to an estimated USD 450 million in 2025, the market is projected to continue growing at a compound annual rate of approximately 5.85% across the forecast horizon (2026–2032).
Worldwide Oblong Jar Market
Why this report matters for 2026 strategies
-
Timing: 2026 is the inflection year for packaging players facing simultaneous cost, regulatory and sustainability pressures. The report isolates actionable moves that fit a 12–36 month execution cadence—precisely the window in which boardroom decisions made now will begin to show impact.
Worldwide Oblong Jar Market -
Commercial focus: We translate market momentum into commercial priorities—how to pivot product portfolios, where to capture margin through design and procurement, and what partnership models accelerate market access.
Worldwide Oblong Jar Market -
Risk‑calibrated planning: Our supply‑side stress tests and scenario sets let leaders recalibrate CAPEX and sourcing strategies against raw material spikes, changing trade flows and Extended Producer Responsibility (EPR) regimes.
Executive snapshot — macro picture and concentration
The oblong jar market is mature but dynamic. After a period of steady recovery and product substitution trends in the early 2020s, total industry revenue stood close to USD 450 million in 2025 and—under our central forecast—moves toward a materially larger market by 2032. Market structure remains fragmented: the three‑firm and five‑firm concentration ratios are low, underscoring a competitive landscape where national and regional players retain strong negotiating power with large consumer goods customers. That fragmentation creates both opportunity for value consolidation and risk for firms that fail to differentiate.
What’s inside the full report (practical deliverables)
-
Market sizing and 7‑year forecast (2026–2032) built from bottom‑up SKU and channel modelling, with sensitivity bands tied to raw material and regulatory scenarios.
-
Go‑to‑market playbooks for manufacturers and converters that include pricing frameworks, assortment rationalization templates, and retail pack‑out optimization checklists.
-
Supplier risk matrix and near‑term mitigation tactics (dual sourcing, strategic inventory, contract clause templates) calibrated to volatility observed across glass and plastics supply chains.
-
Sustainability and compliance toolkit: practical steps to meet looming EPR obligations, a roadmap for recycled content implementation, and a supplier audit checklist to verify recyclability claims.
-
Scenario planning engine and M&A screening filters that identify target profiles most likely to accelerate scale or capability (e.g., circularity tech, automation in thermoforming, specialized neck finish tooling).
-
Commercial benchmarking and margin levers for packaging buyers—detailing where to capture 1–3% incremental margin through specs simplification, fill‑line harmonization and closure standardization.
Competitive landscape — strategic implications for 2026
The market’s leading suppliers and distributors occupy distinct roles across scale, channel focus and technical capability. PW Consulting’s assessment of key firms surfaces tactical plays buyers and competitors should anticipate.
- Berlin Packaging (United States): a high‑volume supplier specializing in warehouse‑retailer formats. Their scale orientation makes them a natural partner for CPG players seeking margin‑effective packaging at high throughput; competitors should expect continued emphasis on integrated service offerings (warehousing + packaging) that blur the supplier/customer line.
- The Cary Company (United States): known for industrial‑grade plastic oblong jars with functional features (handles, wide mouths). Their strength is niche product engineering—an area ripe for premiumization and industrial OEM partnerships.
- Parkway Plastics (Parkway Jars) (United States): legacy expertise in reusable and recyclable plastics. Parkway’s long heritage positions them to lead on circular packaging pilots, especially where brand customers demand both reuse and recycled content options.
- SKS Bottle and Packaging (United States): a broad catalog provider across glass and plastics; their value rests in fast SKU availability and finishing options, serving mid‑market formulators that prioritize speed to shelf.
- O.Berk (United States): established for pharmaceutical and specialty personal‑care jars—expect continued traction where compliance and traceability matter most.
- Silgan Plastics (United States): strong in food and condiment segments; their manufacturing depth makes them a key supplier for large food processors adapting to changing service levels and sustainability targets.
- FH Packaging (United States): global reach across glass and plastic jar formats; their strategic playbook centers on bundling design, compliance and logistics for multinational customers.
- Illing Company (United States): focused on industrial application containers; their portfolio is attractive to B2B customers needing technical resin expertise and custom tooling.
For buyers, the strategic takeaway is clear: partner selection in 2026 will be a choice between scale/value (cost and logistics), technical differentiation (closures, engineered features), and circularity (recycled content, reuse models). Suppliers should align one of these value propositions as a core competency and build partnerships to fill gaps.
Regulatory and raw‑material dynamics that will shape 2026 moves
-
Extended Producer Responsibility (EPR): multiple U.S. states have implemented EPR regimes that shift end‑of‑life costs onto producers. California’s phased recycling targets (30% by 2028, 40% by 2030, 65% by 2032) are a bellwether—brands and packagers must embed compliance costs into 2026 price models and product roadmaps.
-
Raw material pressures: industry indicators point to continued pressure in glass manufacturing inputs (for example, producer price indices are elevated), and mass‑produced soda‑lime jars trade at commodity FOB ranges that compress low‑margin converters. Our stress tests model both short spikes and prolonged price regimes to indicate when cost pass‑through is viable versus when product redesign is necessary.
-
Policy uncertainty: states continuing to consider EPR (and new policy layers) will create asynchronous compliance burdens—favour those supplier relationships that include compliance support and flexible contract terms.
Concrete 2026 playbook—five priority actions
-
Re‑baseline packaging economics: update costing models to include EPR liabilities, realistic recycled content premiums, and a 12–18 month raw‑material stress surcharge schedule. Tie these models directly into commercial negotiations.
-
Prioritize a three‑to‑five SKU rationalization: small reductions in SKU complexity can unlock outsized savings on tooling, fill‑line changeover and freight. Our benchmarking shows this is one of the fastest ways to crystallize margin improvement in the near term.
-
Accelerate circular pilots with measurable KPIs: design 6–12 month pilots for recycled content and reuse programs with grocery or direct‑to‑consumer partners—embed obligations and exit criteria up front.
-
Lock strategic supply options: enter selective medium‑term purchase agreements that incorporate indexed pricing, capacity reservation, and optionality for material substitution between PET, polypropylene and glass where technically feasible.
-
Scan for bolt‑on M&A: prioritize targets that add automation, secondary finishing capabilities (neck/thread tooling), or downstream recycling aggregation—these generate the quickest ROI in a fragmented supplier market.
What we withhold—and why
In this preview we have deliberately showcased frameworks, strategic recommendations and headline market trajectories to help you prioritize boardroom attention in 2026. To preserve the integrity of ongoing commercial negotiations and to ensure our clients derive proprietary advantage, we do not publish the detailed sub‑segment revenue splits and region/application percentiles in public summaries. The full report contains the granular breakdowns, channel and SKU‑level forecasts, and supplier scorecards that undergird the strategic guidance above.
How to access the full intelligence
For companies making procurement, portfolio or investment decisions in 2026, accessing the full data pack is the difference between an informed hedge and a surprised balance sheet. PW Consulting offers the comprehensive report, downloadable datasets, and bespoke briefing sessions with our senior analysts. Contact your PW Consulting representative or visit our report page to arrange a tailored walk‑through and to obtain the confidential appendices (including SKU‑level demand curves, supplier scorecards, and the scenario modelling workbook).
PW Consulting’s Worldwide Oblong Jar Market study is designed to convert market insight into boardroom action. If your 2026 plan touches packaging, procurement, sustainability compliance or M&A in this space, this is the intelligence you should be building your decisions on.
For detailed analysis of this topic, please visit the official page: Worldwide Oblong Jar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com