

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Thiochemicals Market Reaches USD 3,260.5 Million in 2025; Forecast 2026–2032 to Grow at 4.51% CAGR

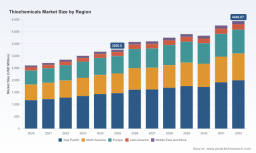
Worldwide Thiochemicals Market — Strategic Insights for 2026 Corporate Decision-Making
As global commodity and specialty chemical value chains recalibrate for a post-pandemic, energy-transition era, thiochemicals occupy a uniquely strategic niche. PW Consulting’s latest market study shows the global thiochemicals market reached approximately USD 3,260.5 million in 2025 and is expected to strengthen in the near term — reaching roughly USD 3,577.3 million in 2026 — before progressing at a compound annual growth rate (CAGR) of 4.51% over the 2026–2032 forecast window to about USD 4,440.1 million by 2032. For executives planning capex, procurement, or commercial redeployment in 2026, the report delivers the combination of macro clarity and practicable options required to translate market movement into defensible, value-accretive decisions.
Worldwide Thiochemicals Market
What the report delivers — practical, decision-focused outputs
-
Quantified market baseline and directional scenarios: firm 2025 base-year sizing, 2026 short-term outlook, and detailed 2026–2032 trajectories across demand and supply sides.
Worldwide Thiochemicals Market -
Demand-driver intelligence: sectoral demand drivers and stress scenarios that affect product mix priorities without exposing client-level proprietary splits.
Worldwide Thiochemicals Market -
Cost and margin stress-testing: feedstock-price sensitivity matrices (notably sulfur-linked inputs), break-even curves, and margin-protection playbooks for different product classes.
-
Supply-chain and capacity mapping: verification of global manufacturing footprints, debottlenecking opportunities, and logistics risk heatmaps.
-
Competitive benchmarking and capability mapping of leading producers, including technical strengths, footprint advantages, and likely strategic moves.
-
M&A and partnership playbooks: prioritized target archetypes, valuation lenses, and integration risk checklists tuned to 2026 market conditions.
-
Regulatory & sustainability roadmap: compliance cost estimates, low-emission process options, and transition pathways aligned with evolving ESG thresholds.
Why 2026 is a pivotal planning year
Two sets of dynamics converge in 2026 to make near-term strategic action material to medium-term value creation. First, upstream feedstock volatility has returned as a critical margin lever. Elemental sulfur — the primary upstream feedstock that is converted into H2S and methyl mercaptan for downstream thiochemical synthesis — has experienced pronounced price swings. Industry monitoring indicates contract and spot benchmarks moved sharply in late 2025 and into 2026, creating a short-term squeeze that transmits quickly into operating margins for producers. For certain mercaptan producers, sulfur procurement can represent as much as one quarter of cash cost, underscoring the importance of robust procurement and hedging strategies.
Second, demand-side composition is shifting. Traditional applications such as oil & gas and fertilizer-related demand remain material, while specialty uses in animal nutrition, polymer processing, and pharmaceutical intermediates are evolving in quality and regulatory expectations. These dynamics mean that product portfolio choices — commodity versus specialty, volume versus margin — will determine winners and losers as buyers re-price risk and suppliers optimize capacity.
Competitive landscape: capabilities to watch (select overview)
-
Arkema (France) — a global integrator with a broad organosulfur portfolio and multi-continent manufacturing. Recent disclosures and operational moves (including a 2023 debottlenecking program in North America and the company’s 2024 sustainability reporting) signal a strategy combining capacity optimization and ESG positioning.
-
Chevron Phillips Chemical (United States) — leverages refinery and petrochemical integration to supply mercaptans and thiochemical intermediates for industrial and refinery applications; strong technical and feedstock access positions underpin its market relevance.
-
Specialty and regional producers — a cohort of European, Japanese and Chinese firms (including Merck KGaA, Daicel, Toray Fine Chemicals and multiple Chinese manufacturers) competes on high-purity grades, application-specific formulations, and local cost positions. Many of these players target differentiated niches such as pharmaceutical-grade reagents, cosmetic intermediates, and agrochemical inputs.
-
Market structure — the sector shows a moderate level of concentration: a mix of global leaders with broad portfolios and numerous regional specialists. The implication is dual-track competition — scale plays for commodity lines, and technical specialization for higher-margin segments.
Strategic implications for executives in 2026
Our analysis crystallizes seven cross-functional imperatives that should inform board-room deliberations, capital planning and commercial strategy in 2026.
-
Hedge and secure feedstocks proactively. Given sulfur-price volatility and its outsized effect on methyl-mercaptan cash costs, companies should deploy multi-layered procurement approaches: long-term contracts with indexed clauses, strategic spot exposure limits, and evaluation of upstream integration (H2S capture or sulfur recycling) where capex economics permit.
-
Prioritize portfolio clarity: balance volume with margin. Use product-level margin simulation to reallocate R&D and commercialization spend toward higher-margin specialty thiochemicals where technical barriers limit new entrants, while rationalizing low-margin commodity lines through consolidation or tolling agreements.
-
Strengthen manufacturing resilience. Multi-site manufacturing footprints reduce single-point failures; debottlenecking and short-cycle capacity flex (e.g., tolling partnerships or modular units) enable faster response to demand spikes without large fixed investments.
-
Adopt targeted sustainability investments. Low-emission process upgrades and feedstock-efficiency gains can be both differentiation and compliance drivers. Prepare to translate sustainability investments into customer-facing claims that buyers in regulated industries will value.
-
Reassess pricing architectures. Move beyond transactional spot pricing to value-based pricing in specialty channels, and implement clause-driven contracts that share feedstock cost volatility with buyers where trust and market position allow.
-
Scan for M&A and partnership vectors. In a market with clear adjacent capabilities and regional strengths, bolt-on acquisitions, JV manufacturing for local markets, and IP/technology licensing are high-leverage options to accelerate market access without greenfield timelines.
-
Embed advanced analytics into the commercial engine. Demand-sensing using end-market telemetry (e.g., fertilizer and animal feed indicators), combined with cost-to-serve models, enables dynamic allocation of limited production to most valuable channels in short-cycle environments.
Competitive moves to watch in 2026
Several near-term moves will determine market share trajectories through the late 2020s. Watch for:
-
Capacity optimization and debottlenecking by global leaders pursuing incremental tonnage in high-value lines — actions which can temporarily compress spreads but drive longer-term volume leadership.
-
Regional capacity additions in cost-advantaged geographies, particularly from mid-sized Chinese producers that continue to scale production of intermediates and fine sulfur chemicals.
-
Strategic alliances between feedstock holders and specialty producers to lock supply chains and create preferred-supplier ecosystems for sensitive applications (e.g., pharma and high-purity reagents).
-
Regulatory and sustainability-driven product differentiation: expect new grades and processes to be promoted to buyers focused on life-cycle impacts.
How PW Consulting supports 2026 decision cycles
PW Consulting brings a practitioner-first suite of services tailored to the thiochemicals agenda:
-
Scenario-based valuation and capex prioritization — including sulfur-price stress tests and break-even mapping by product family.
-
Commercial playbooks for portfolio shift — from go-to-market segmentation to value-based pricing and distributor redesign.
-
M&A diligence and integration playbooks — target screening by capability archetype, synergies quantification, and post-merger integration sequencing.
-
Procurement optimization — contract design, hedging strategies, and supplier consolidation plans focused on feedstock volatility mitigation.
-
Operational improvement — debottlenecking blueprints, modular capacity options, and OPEX-driven margin recovery programs.
Final note: where to find the data you need
This briefing is a concise distillation of the report’s strategic findings. PW Consulting’s full Worldwide Thiochemicals Market report contains the complete datasets, regional and product-level forecasts, and the granular scenario models that underpin the recommendations summarized here. The report’s methodological frame is anchored on a 2025 base year, historical analysis for 2020–2025, and a forecast period covering 2026–2032 (currency: USD, revenue units in millions). For procurement teams, commercial leaders and corporate strategists preparing 2026 plans, the full report provides the calibrated segment-level intelligence and downloadable models necessary to operationalize the strategic directions outlined above.
To engage PW Consulting for a customized workshop, model adaptation, or acquisition due diligence support tied to the thiochemicals value chain, contact our industry team for a confidential consultation and access to the full dataset.
For detailed analysis of this topic, please visit the official page: Worldwide Thiochemicals Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com