

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Digital Olfactory Market Set to Climb from USD 185.5 Million in 2025 to USD 310.5 Million by 2032 at a 7.63% CAGR — E‑Nose Sensors Lead, North America Tops, Top‑5 Hold 48%

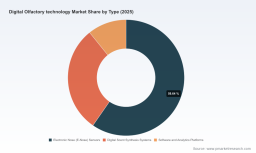
Digital Olfactory Technology Market: Strategic Imperatives for 2026 — PW Consulting Highlights from Our New Market Report
Executive snapshot
PW Consulting’s latest market study on Digital Olfactory technology provides a forward-looking, operationally oriented assessment designed to influence enterprise strategy in 2026. The report, based on a 2025 base year with historical coverage from 2020–2025 and a detailed forecast out to 2032, synthesizes primary research, vendor interviews, regulatory mapping, and a proprietary market model. At a macro level, the market is on a sustained growth trajectory driven by advances in sensor microfabrication, AI-enabled signal processing, and emergent commercial use cases — reflected in a compound annual growth rate of 7.63% for the forecast period and a projected market expansion from an estimated USD 185.5 Million in 2025 to approximately USD 310.5 Million by 2032.
Digital Olfactory technology Market
Why this matters to corporate decision-makers in 2026
-
Timing and scale: With mid-single-digit to high-single-digit CAGR and a near-term inflection in commercialization activity, executives must decide now whether to invest in internal capability, partner with specialist vendors, or remain a fast follower. The market is large enough to matter for product differentiation, yet still fragmented enough to allow for strategic entry points.
Digital Olfactory technology Market -
Technology stack bets: The interplay between sensor hardware, signal-conditioning electronics, and machine-learning analytics creates multiple levers for value capture. Choices made in 2026 about which layer to own will determine margin profiles and exit options three to five years out.
Digital Olfactory technology Market -
Regulatory and standards design: Ongoing efforts to create interoperability and medically compliant devices are moving from academic debate into regulatory practice. Firms considering clinical or safety-critical applications must align product development and clinical validation strategies with evolving standards.
Key market dynamics — what the report reveals
-
Commercial momentum: Investment in scale-up, patenting activity, and go-to-market infrastructure has accelerated. Notably, several market participants have advanced from R&D demonstrations to manufacturing and commercial deployments within the last 18 months, signaling a shift from experimentation to industrialization.
-
Concentration and competitive structure: The market shows moderate concentration. The top three firms account for roughly one-third of market activity, with the top five approaching roughly half — a structure that supports both competitive rivalry and partnership opportunities for challengers.
-
Standards and certification as adoption levers: ISO and industry-specific certification pathways are increasingly determining procurement decisions in regulated segments such as healthcare and environmental monitoring. Compliance is becoming a market-entry gatekeeper.
-
Hardware bottlenecks persist: Sensor drift, environmental sensitivity (temperature, humidity), and calibration overhead remain primary technical constraints that affect long-term reliability and operational cost. These are the issues procurement and engineering teams must solve in parallel with algorithmic improvements.
Competitive landscape — where incumbent and emerging vendors stand
The report includes a disciplined vendor assessment of core players shaping the ecosystem. Below we summarize strategic positioning without disclosing granular market splits.
-
Osmo (Elizabeth, NJ, USA) — Positioned as an AI-first digital olfaction company, Osmo has combined model-led scent mapping with a commercialization push. Recent actions include major patenting activity and the opening of a large headquarters and manufacturing facility in 2026, signaling an aggressive move to scale production and commercial deployment of an “Olfactory Intelligence” platform. For product teams, Osmo represents a vertically oriented competitor with strong IP and manufacturing intent.
-
Ainos, Inc. (Houston, TX, USA) — Ainos’ full-stack AI Nose platform and recent commercial module launch reflect a strategy of selling turnkey sensor modules plus cloud analytics via a SmellTech-as-a-Service model. Their emphasis on MEMS sensor integration and ppb-level sensitivity makes them a direct competitor for industrial and semiconductor use cases where detection limits and integration simplicity matter.
-
Aryballe Technologies (Grenoble, France) — With a focus on biomimicry, optics, and ML, Aryballe is notable for solutions oriented toward industrial monitoring and healthcare analytics. Their technology roadmap prioritizes robustness in noisy environments — a differentiator for quality-control buyers.
-
Alpha MOS (Toulouse, France) — A long-standing player in electronic noses and tongues, Alpha MOS brings deep domain expertise in sensory profiling and quality control. Large food and beverage firms continue to view Alpha MOS as a reliable partner for sensory analysis workflows.
-
Olorama Technology (Spain) — Focused on scent synthesis and multisensory experiences, Olorama targets entertainment and immersive media. Their patented synthesizer library and work in VR/AR position them as a leader for CX teams exploring olfactory augmentation.
-
Aroma Bit (Japan) — Known for odor-imaging sensor chips, Aroma Bit is a technology supplier for integrators seeking compact, low-power solutions.
-
The eNose Company (Netherlands) — With aeoNose and devices oriented to medical breath analysis, this firm illustrates the route to clinical validation and certification; they have redesigned products to comply with medical device standards and hold ISO 13485.
-
AIRSENSE Analytics GmbH (Germany) — Specializes in portable analyzers for environmental and industrial odor monitoring; a partner of choice for environmental compliance applications.
Regulatory, standards and ecosystem events to watch in 2026
-
Medical device frameworks: Regulatory classifications for olfactory diagnostics (for example, pathways equivalent to Class II devices in some jurisdictions) will materially affect time-to-market and evidence requirements. Clinical validation plans must be integrated early for any company pursuing healthcare applications.
-
Standards work: Ongoing international efforts are addressing sensor performance, calibration, and interoperability — developments that will reduce buyer friction but will also raise technical compliance costs for vendors that do not anticipate them.
-
Conferences as market accelerants: Industry forums and symposia scheduled in 2026 will catalyze alliances, standards progress, and early commercial partnerships. These venues are strategic touchpoints for business development and talent recruitment.
What the PW Consulting report delivers — practical, decision-ready content
Beyond market sizing and trend narrative, the report is explicitly constructed as a toolkit for corporate strategy teams. Key operational deliverables include:
-
A transparent market model with scenario sensitivity to inputs such as sensor cost declines, algorithm licensing fees, and regulatory time-to-approval — enabling CFOs to test capex vs. opex strategies.
-
Technology maturity and risk matrix mapping hardware, firmware, and AI components to deployment readiness for different industry verticals.
-
Vendor due-diligence playbooks and an RFP template for procurement teams evaluating sensor modules, synthesis systems, or analytics platforms.
-
Compliance and clinical pathway maps for organizations targeting medical or safety-critical certifications, including recommended evidence packages and typical timelines.
-
Use-case playbooks that include commercial models, unit-economics benchmarks, and go-to-market roadmaps for representative applications (quality control, diagnostics, CX/entertainment, and environmental monitoring).
-
A curated supplier and partner directory with capability profiles and suggested partnership archetypes (integrator, technology licensor, manufacturing partner).
Strategic recommendations for executives in 2026
-
Define the value boundary: Decide early whether to compete on hardware, software, or a combined platform. Owning the data layer — while outsourcing commodity sensing — often delivers the highest software-margin upside.
-
Invest in calibration and lifecycle management: Given sensor drift and environmental sensitivity, allocate R&D and operations resources to calibration-as-a-service, remote maintenance, and automated revalidation.
-
Build regulatory-first roadmaps for clinical and safety use cases: Integrate quality systems, clinical validation, and regulatory filing effort into product timelines rather than treating them as afterthoughts.
-
Pursue strategic partnerships: Co-development with specialists — for instance, a sensor OEM with a ML analytics provider — can compress product timelines and share validation burdens.
-
Hedge supply-chain risk: Secure alternative sources for core sensor components and consider localized manufacturing where certifications or scale require it.
-
Monitor IP landscapes and patent activity closely: Aggressive patenting has become a competitive lever; align IP strategy with business model options (licensing vs. exclusivity).
How to use this report in board-level conversations
We designed the report to be directly usable in executive decision cycles. Use the market scenarios to stress-test investment proposals, the vendor playbooks to structure procurement and partnership discussions, and the regulatory maps to estimate compliance-related capex and time-to-revenue. For strategy teams, the report’s actionable templates can reduce sourcing cycle time and improve the quality of go/no-go investment decisions.
Conclusion — a strategic preview, not the whole film
Digital olfaction is transitioning from laboratory curiosity to an industrially relevant technology stack with measurable market momentum. PW Consulting’s analysis shows a market that is growing meaningfully, with identifiable commercial pathways and practical engineering obstacles that can be mitigated with the right choices. This release is intended as a strategic preview: it signals the scale and direction of opportunity, profiles leading players, and offers a playbook for executives. For the granular market splits, vendor scorecards, and the operational templates that powers tactical decisions, access the full report and accompanying datasets on the PW Consulting site.
For detailed analysis of this topic, please visit the official page: Digital Olfactory technology Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com