

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rare Disease CRO Service Market to Reach USD 12,829 Million by 2032 on 10.2% CAGR

Rare Disease CRO Service Market: Strategic Imperatives for 2026
PW Consulting’s new market research brief on the Rare Disease Contract Research Organization (CRO) Service Market synthesizes commercial, regulatory and operational intelligence that will shape outsourcing decisions through 2026 and beyond. Built on a detailed base year of 2025 and a 2026–2032 forecast horizon, the study combines rigorous market-sizing with actionable playbooks for sponsors, CROs, investors and policy teams. Key macro signals — including a projected compound annual growth rate (CAGR) of 10.2% and an escalating total market that more than doubles over the forecast period — make 2026 a pivotal planning year for firms that must balance capacity, capability and compliance in complex, low-volume development programs.
Rare Disease CRO Service Market
Market Trajectory in Context
Between 2020 and 2025 the rare disease CRO market experienced a sustained expansion, reflecting accelerating investment in orphan-drug pipelines, advanced therapies and trial models tailored to dispersed patient populations. Our base-year analysis (2025) anchors the study and the 2026–2032 forecast quantifies the continuation of that momentum: at a 10.2% CAGR the market is expected to more than double from its early‑decade scale by the end of the forecast window. This growth reflects both a rising number of programs in gene, cell and RNA modalities and the premium per‑patient economics that rare disease trials entail.
Rare Disease CRO Service Market
Why 2026 Is an Inflection Year
-
Regulatory harmonization and flexibility: Initiatives such as the FDA’s Rare Disease Innovation Hub and the Rare Disease Evidence Principles (announced in 2025) are lowering traditional evidentiary barriers for ultra‑rare conditions, but they also place a premium on adaptive statistical planning and specialized regulatory strategy.
Rare Disease CRO Service Market -
Guidelines and operational adaptation: ICH E6(R3) finalized in 2025 emphasizes risk‑based monitoring and flexible trial designs, accelerating adoption of decentralized assessments, remote endpoints and hybrid models — all of which require CROs to retool platforms and talent pools in 2026.
-
Data privacy and cross‑border complexity: Cross‑border genomic data flows continue to be constrained by GDPR, HIPAA and related regimes. Sponsors must reconcile global recruitment ambitions with data governance plans that protect patient privacy without compromising analytic utility.
-
M&A and capability consolidation: Recent sector moves and announced transactions show buyers prioritizing endpoint‑data integration, specialized patient recruitment networks and Centers of Expertise. These trends create both scale opportunities and integration risks for acquirers and targets alike.
Competitive Structure and Strategic Players
The market remains moderately concentrated: the top three and top five vendor groups capture meaningful shares of activity and capacity, yet a diverse array of specialized and regional players continues to compete for protocol‑specific mandates. Market concentration metrics embedded in the report highlight a landscape where leading full‑service CROs coexist with niche specialists focused on biomarker analytics, decentralized execution and ultra‑rare recruitment strategies.
Key organizations profiled in the study include established global CROs and specialized firms that represent distinct strategic archetypes:
-
Medpace — an end‑to‑end clinical development partner with deep neuroscience, metabolic and ophthalmology expertise and hundreds of rare disease studies informing standardized playbooks for complex protocols.
-
Precision for Medicine — a biomarker- and lab-integrated specialist that brings “Rarefied Thinking” to cell and gene programs through tight lab-clinic integration across multiple indications.
-
Parexel and ICON — large global CROs offering integrated clinical, regulatory and access consulting able to support gene and nucleic acid therapy trials at scale.
-
PPD (Thermo Fisher) and IQVIA — data- and endpoint-focused players investing in systems to reduce per-patient operational friction and to accelerate go/no‑go decisions.
-
Specialists such as TFS HealthScience, Ergomed, Allucent, Fortrea and Veristat — firms that combine tailored patient-finding, operational agility and therapeutic‑area centers of excellence to serve ultra‑rare and pediatric programs.
-
Worldwide Clinical Trials and other mid‑market firms — consolidators that expand capability sets through acquisitions to penetrate adjacent therapy areas and functional service platforms.
The competitive profiles in the report balance quantitative benchmarking with qualitative decision heuristics — allowing clients to compare capability gaps and partnership fit without divulging commercially sensitive segment-level metrics in this public summary.
Operational and Commercial Dynamics That Will Drive Decisions in 2026
-
Cost per patient remains materially higher in ultra‑rare Phase III programs, driven by specialized navigators, bespoke endpoint collection and geographically dispersed cohorts. Sponsors must decide whether to internalize rare disease competencies or to form longer-term strategic partnerships with CROs that have embedded rare-disease infrastructures.
-
Patient recruitment sophistication is now a competitive moat: firms that combine patient‑registry analytics, advocacy partnerships and decentralized enrollment solutions reduce screen‑fail rates and compress timelines.
-
Endpoint data integration and electronic source systems are no longer optional. Recent announced integrations in the sector reflect buyer demand for data harmonization across lab, imaging and wearable streams.
-
Regulatory strategy and evidence planning must be front‑loaded. Adaptive designs, registry‑based controls and natural history alignment require early engagement with regulators and payers to maximize the value of limited patient data.
What the PW Consulting Report Delivers — Practical, Executable Assets
This study was developed for executives who need to convert market intelligence into program-level decisions in 2026. Deliverables include:
-
Robust market sizing and a transparent methodology tied to a 2020–2025 historical base and a 2026–2032 forecast, enabling scenario analysis under multiple adoption paths and reimbursement outcomes.
-
Vendor capability maps and a decision matrix that rank potential CRO partners against protocol archetypes (e.g., gene therapy, pediatric metabolic, neuromuscular trials) — presented as playbooks rather than raw market slices.
-
Operational playbooks for patient recruitment, decentralized assessments, endpoint device integration and risk‑based monitoring that can be implemented within 90–180 days.
-
M&A and partnership assessment frameworks including integration checklists, value‑capture levers and a regulatory due diligence template focused on data governance and cross‑border compliance.
-
Payer and evidence-generation pathways aligning rare disease approval strategies with post‑launch access planning — essential for aligning clinical design to commercial outcomes.
How Executives Should Use This Intelligence in 2026
-
Prioritize capability investments. Use the report’s capability heatmaps to decide whether to buy, build or co‑develop rare‑disease competencies — including biomarker labs, patient recruitment hubs and decentralized trial platforms.
-
Calibrate partnership horizons. Longer program timelines and high per‑patient costs favor multi‑year strategic alliances over transactional engagements for sponsors running multiple rare indications.
-
Screen targets with a technical lens. The report’s M&A scoring tool helps acquirers evaluate targets based on operational fit, evidence-generation speed and regulatory readiness rather than headline revenue multiples alone.
-
Stress test data governance. 2026 is the year to codify genomic and patient-level data flows into contracts and systems that are resilient to GDPR/HIPAA constraints while preserving analytic value.
-
Integrate regulatory and commercial planning. Use the report’s evidence-principles playbook to align adaptive trial features with likely payer evidence requirements, reducing post‑launch reimbursement risk.
Why This Report Is a Strategic Asset — Not Just a Dataset
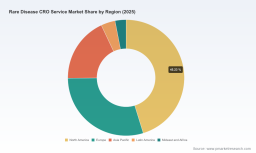
We designed the study to be executional. Beyond headline market growth figures and vendor lists, the report translates macro growth into the micro decisions teams face when standing up rare‑disease programs: how to price FSP engagements for ultra‑rare cohorts, how to staff advanced‑therapy trial teams, how to structure global data governance, and how to operationalize adaptive designs in ways that satisfy regulators and payers. The public summary you are reading deliberately omits granular regional and service‑type splits to preserve the proprietary segmentation and scenario outputs that are available in the full deliverable. That “teaser” approach reflects our view: strategic advantage accrues to leaders who pair public signals with privileged, actionable frameworks.
Next Steps for 2026 Decision Makers
If your 2026 agenda includes reprioritizing development portfolios, sizing M&A pipelines, or rethinking outsourcing models for orphan and ultra‑rare programs, PW Consulting’s Rare Disease CRO Service Market report is built to accelerate those decisions. The full report contains the detailed segmentation, vendor scorecards and executable playbooks you will need to operationalize the strategic directions outlined here.
To obtain the full analysis, detailed splits and downloadable tools referenced in this release, access the PW Consulting report page or contact our advisory team for a briefing tailored to your program portfolio.
For detailed analysis of this topic, please visit the official page: Rare Disease CRO Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com