

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Automotive Power Distribution Modules Market Poised to Expand at a 7.6% CAGR
By pmarketresearch, 2026-07-17
Worldwide Automotive Power Distribution Modules Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest market study on Worldwide Automotive Power Distribution Modules (PDMs) equips senior executives, purchasing directors, and investment committees with a practical, decision‑ready perspective for 2026. Built on a five‑year historical base (2020–2025) and a seven‑year forecast window (2026–2032), the report combines rigorous market-sizing, scenario modelling, supply‑chain stress tests and competitive intelligence to translate market dynamics into concrete strategic options.
Worldwide Automotive Power Distribution Modules Market
Market trajectory: what the headline numbers mean for strategy
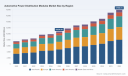
The global PDM market has transitioned from volume recovery to structural growth. Our model shows the market advancing from a 2020 baseline through a 2025 anchor point of approximately USD 10.8 billion (revenue unit: Million, USD base) and entering the forecast phase at roughly USD 11.8 billion in 2026. Across the 2026–2032 horizon the market is projected to grow at a compound annual growth rate of 7.6%, reflecting accelerating electrification, tighter safety and cybersecurity standards, and OEM architecture re‑platforming.
Worldwide Automotive Power Distribution Modules Market
For executives, the implication is clear: 2026 is not merely a continuation year — it is a pivotal planning year to lock in supplier relationships, allocate R&D budgets for next‑generation high‑voltage topologies, and implement procurement strategies resilient to raw‑material and regulatory shocks. The growth profile supports selective capacity expansion and targeted technology investments, but success hinges on anticipating non‑linear risks (regulatory, material and technological) rather than assuming steady demand alone.
Worldwide Automotive Power Distribution Modules Market
Key market forces shaping 2026 decisions
- Electrification architecture upgrades — Vehicle electrical architectures are evolving rapidly toward higher voltages and integrated power management. OEMs are converging on modular high‑voltage PDMs for modular platforms, driving demand for suppliers capable of scaling both hardware and embedded software.
- Regulatory and safety imperatives — New safety requirements for high‑voltage corridors and ingress protection, combined with vehicle network cybersecurity mandates, are raising qualification thresholds for PDMs. Compliance timelines in 2026 will define supplier shortlists and accelerate consolidation among firms with mature validation programs.
- Material and manufacturing pressures — Commodity cycles and component supply constraints remain salient. Copper cost inflation and a shift toward aluminum conductors (which reduce system weight but introduce joining and thermal challenges) force buyers to reconfigure cost models and supplier capabilities.
- Software and systems integration — The PDM is increasingly a cyber‑physical component. Suppliers that offer both robust hardware and secure, updateable software stacks will command premium positions in OEM selection processes.
Practical intelligence contained in the report
The report is designed for operational use in 2026 planning cycles. Key deliverables include:
- Robust market sizing and topline forecasts with sensitivity bands to capture downside commodity and regulatory outcomes.
- Scenario planning tools — including a “fast‑EV” and a “regulated safety” scenario — that translate regulatory and material shocks into revenue and margin outcomes at the supplier and OEM level.
- Supplier scorecards and technology readiness matrices that evaluate electrical performance, thermal management, IP maturity and cybersecurity posture.
- Supply‑chain heat maps and logistics risk indices enabling procurement teams to prioritize dual sourcing, localization or strategic inventory policies where warranted.
- Detailed playbooks for OEMs and Tier‑1s on qualification timelines, testing corridors for high‑voltage compliance and cybersecurity checklists aligned with recent UN/ECE and EU requirements.
- Capital allocation frameworks and a shortlist of acquisition/partnership targets consistent with a mid‑consolidation market (CR3 ~38.4%; CR5 ~52.2%).
Competitive landscape: what to watch in 2026
The market exhibits moderate concentration, leaving meaningful openings for technologically differentiated challengers. Our competitive review profiles leading Tier‑1s and system suppliers — analyzing strengths, go‑to‑market models, and recent strategic moves that will influence sourcing and partnership decisions in 2026.
- Aptiv (Ireland) — Strong in smart junction boxes and high‑voltage systems; recent product launches for 800V architectures position Aptiv to capture EV platform upgrades where high‑voltage scaling is a priority.
- Yazaki Corporation (Japan) — Deep wiring harness and PDM experience across vehicle segments; supplier nominations for high‑profile OEM programmes signal continued traction in core vehicle platforms.
- Sumitomo Electric Industries (Japan) — Integrated wiring and PDM supplier to global OEMs; offers advantages where harness‑module integration reduces assembly complexity.
- Motherson Group (India) — Rapidly expanding electrical power management capabilities through dedicated divisions; competitive on local content strategies for regional OEMs.
- Leoni AG (Germany) — European wiring and module specialist with engineering strength in integrated systems for premium segments.
- Furukawa Electric (Japan) — Focused on compact PDMs for hybrid and electric powertrains; competitive in space‑constrained vehicle architectures.
- Lear Corporation (USA) — E‑Systems supplier moving into integrated power distribution through strategic development agreements with major OEMs.
- Denso Corporation (Japan) — Supplier depth in ECU‑integrated power management with strong global OEM relationships.
- BorgWarner (USA) — Specialised in high‑voltage modules for electrified powertrains; recent vehicle integrations showcase production experience for EV platforms.
- Valeo (France) — Offers holistic thermal and electrical systems for both ICE and EV platforms, enabling cross‑architecture leverage.
Notably, recent industry moves — from Aptiv’s next‑generation 800V module to supplier nominations and joint developments — highlight a market where product innovation and close OEM collaboration determine selection. The report dissects these moves to show where capability overlaps create choke points for OEMs and where targeted partnerships can shorten time‑to‑production.
Actionable recommendations for executives planning 2026
- For OEM procurement leads — Reframe RFPs to include software lifecycle terms and cybersecurity KPIs. Prioritize suppliers with proven high‑voltage validation programs and documented production readiness; use staged sourcing to align volume ramps with regulatory certification milestones.
- For Tier‑1 suppliers — Invest selectively in advanced joining technology and thermal‑management IP to support aluminum conductor designs. Build modular product lines that can be firmware‑upgraded to meet evolving safety and cybersecurity standards.
- For investors and M&A teams — Target assets that fill capability gaps — particularly in embedded software, high‑voltage safety testing and lightweight conducting technologies. The current concentration metrics suggest attractive bolt‑on opportunities to scale revenues without immediately triggering antitrust scrutiny in all jurisdictions.
- For manufacturing and operations — Implement commodity hedging strategies and supplier diversification for critical conductors. Localize production in high‑priority regions where lead times and regulatory compliance create competitive advantage.
- For R&D and product strategy — Prioritize certification roadmaps against UN/ECE high‑voltage and EU cybersecurity standards. Parallelize hardware and software development to reduce time‑to‑market and maintain upgradeability.
Risk scenarios and mitigation
The report models three downside shocks: a prolonged commodity price surge, a regulatory acceleration that shortens certification windows, and an integration failure scenario where early adopters face thermal or EMC setbacks. For each, we provide contingency playbooks — covering accelerated qualification, temporary design freezes, and emergency supplier swaps — to preserve production timelines and limit margin erosion.
Practical mitigation measures include: pre‑qualifying dual suppliers for critical conductors, setting aside strategic inventory for platform launches, and embedding accelerated test gates in development sprints so that software patches and hardware rework can be sequenced without full vehicle re‑engineering.
Why this report matters for 2026
2026 will be the year when architectural choices harden for the next generation of electrified platforms. Decisions made in 2026 will influence vehicle BOMs, supplier ecosystems and capital allocations for years to come. PW Consulting’s report is constructed to support those decisions: it converts macro growth (7.6% CAGR through 2032), regulatory inflection points and competitive dynamics into prioritized, executable moves — while preserving the confidential, granular segmentation that OEMs and suppliers use internally.
If you need a framework to decide where to invest, whom to partner with, or how to structure procurement and supply‑chain resilience programs for PDMs in 2026, this study delivers both the analytical backbone and the operational playbooks. For full segment breakdowns, supplier scorecards, interactive dashboards and the complete dataset used to build the scenarios, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Power Distribution Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Rigid Thermoform Plastic Packaging Market to Expand at 5.01% CAGR, Reaching ~USD 76.85 Billion by 2032
By pmarketresearch, 2026-07-17
Worldwide Rigid Thermoform Plastic Packaging Market — Strategic Outlook for 2026 Decision-Makers
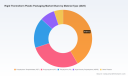
PW Consulting’s latest market study on the Worldwide Rigid Thermoform Plastic Packaging Market provides a practical, boardroom-ready intelligence package designed to influence capital allocation, commercial strategy, and regulatory response throughout 2026. Anchored on a 2025 base year and a robust forecasting framework through 2032, the analysis identifies where value will concentrate, how cost and regulatory dynamics will shift economics, and which competitive plays will unlock disproportionate returns. The headline: the global market, having expanded steadily in recent years, is forecast to continue growing at a compound annual growth rate (CAGR) of 5.01% across the 2026–2032 horizon—presenting both predictable runway and pockets of strategic disruption for investors and operators alike.
Worldwide Rigid Thermoform Plastic Packaging Market
Why this report matters in 2026
-
Decisive year for regulation and EPR implementation — With new rules coming into effect across major jurisdictions in 2026, packaging producers and brand owners must translate compliance obligations into operational targets and product roadmaps.
Worldwide Rigid Thermoform Plastic Packaging Market -
Input-cost volatility compresses margins — Feedstock and resin price fluctuations have reintroduced short-to-medium-term margin risk; commercial teams need granular cost models and indexed pricing strategies to protect profitability.
Worldwide Rigid Thermoform Plastic Packaging Market -
Fragmented supplier landscape — Market concentration metrics demonstrate a fragmented competitive set, which creates opportunities for roll-ups, strategic partnerships, and localized differentiation.
-
Acceleration of sustainable thermoforms — Innovations in recyclable APET, PET sheets for pharmaceutical use, and mono-material designs are reshaping product development and procurement criteria for major buyers.
Macro trajectory and practical implications
PW Consulting’s time-series model shows a clear upward trajectory from historical years into our forecast window. The market’s steady expansion, underpinned by foodservice demand, healthcare and medical packaging needs, and growing consumer convenience trends, creates a predictable top-line environment for 2026 planning. However, the headline growth masks actionable variability: regional regulatory timing, local recycling infrastructure, and raw material price swings will materially alter unit economics and sourcing choices.
For 2026, the practical implications are threefold: (1) procurement teams must build short-cycle hedging and supplier scorecards tied to resin indices; (2) R&D and product teams should prioritize designs that marry recyclability with cost parity; (3) corporate development should actively evaluate M&A targets to gain scale in high-growth subsegments or to access niche pharma/medical certifications.
Market dynamics shaping 2026 strategies
-
Regulatory inflection points — European packaging regulation changes, implemented in 2025 and phasing in through 2026, increase obligations for recyclability, minimum recycled content and extended producer responsibility (EPR). Parallel developments in North America see an expanding patchwork of state-level EPR schemes. These impose upstream financial responsibility on producers and will drive demand for validated recycled-content solutions and traceable material streams.
-
Raw material pressure — Resin market behavior in early 2026 is a critical near-term determinant of margin. Polypropylene and polystyrene pricing show regional dispersion and volatility, influencing material selection strategies and prompting investment in cost-to-serve analytics and alternative material trials.
-
Recycling and standards debates — Thermoformed PET items are under active policy review in several jurisdictions, including discussions on how they should be categorized within recycling lists. This regulatory uncertainty creates both risk and strategic opportunity for companies able to secure early recyclability certifications and chain-of-custody claims.
-
Customer and brand pressure — Major consumer brands continue to demand higher recycled content and improved end-of-life outcomes. Thermoform suppliers that can demonstrate validated circularity pathways will capture preferential sourcing relationships.
Competitive landscape: players, positioning, and strategic moves
The sector remains competitively diverse, with global leaders co-existing alongside specialized regional and niche players. Market concentration levels underscore a fragmented market: the top three and top five firms hold meaningful but limited shares, leaving ample room for differentiation and consolidation.
-
Global integrators — Firms with global footprint and broad product platforms are leveraging scale to invest in recycling technology, medical-grade qualification, and rollstock solutions. Recent product launches focused on APET and medical-grade rollstock signal a push toward higher-value, regulated segments.
-
Foodservice specialists — Established producers in foodservice packaging continue to optimize cost and manufacturing footprint, while selectively piloting sustainable alternatives and mono-material conversions to meet brand commitments.
-
Custom and niche thermoformers — Smaller manufacturers maintain competitive advantage through speed-to-market, customization, and specialized certifications for pharma and medical device packaging. These businesses are attractive targets for larger buyers seeking capability uplift.
Notable recent industry developments illustrate these themes. For example, a global packaging leader launched APET-based thermoformed trays and rollstock tailored for healthcare and pharmaceutical customers, emphasizing enhanced recyclability and cost efficiency. Separately, product expansions in PET sheet grades for pharmaceutical blister and unit-dose formats demonstrate how material innovation is responding to regulatory and clinical needs. These moves foreshadow where winning product strategies will sit in 2026: technically validated, regulation-aligned, and commercially scalable.
What PW Consulting’s report delivers — practical components for 2026 execution
This study was constructed for decision-makers who need executable insights, not academic theory. The report includes:
-
Executive strategic playbooks — Action checklists for procurement, product development, regulatory compliance, and commercial teams calibrated for 12–36 month horizons.
-
Scenario-driven financial models — Base, upside, and downside cases that translate resin cost swings, recycled-content mandates, and EPR fees into P&L and free-cash-flow outcomes.
-
CapEx and footprint optimization tools — Manufacturing line economics, return-on-investment calculators for conversion to recyclable substrates, and a heat-map to prioritize retrofit vs. new-build decisions.
-
Segment and application playbooks — Go-to-market templates for foodservice, healthcare, electronics, and personal care (note: detailed segment-level forecasts and regional splits are included in the full report; this release highlights strategic directions while preserving proprietary values to encourage direct access to the source).
-
Supply-chain stress tests — Supplier scorecards, dual-sourcing frameworks, and short-term hedging strategies that reduce exposure to resin price volatility.
-
M&A and partnership roadmaps — Target archetypes, valuation benchmarks, and integration playbooks for buyers seeking scale or specialization.
-
Regulatory compliance checklists — Jurisdiction-by-jurisdiction impact assessments and stepwise compliance timelines for EPR and packaging waste rules relevant to 2026.
How leaders should translate insight into decisions in 2026
-
Procurement: adopt index-linked contracts where available, implement short-cycle buy/sell analytics, and expand qualified supplier lists for recycled-content feedstocks.
-
R&D and product development: prioritize mono-material designs and validated recycled-content solutions that meet emerging certification requirements; accelerate qualification for pharma-grade PET sheets where demand is rising.
-
Commercial teams: reprice channels where cost-to-serve has changed materially; work with brand-customers to co-invest in validated recycling streams that reduce EPR exposure.
-
Corporate development: pursue tuck-ins that add certification capability or regional scale; use market fragmentation to secure attractive valuations for roll-up strategies.
Final perspective — a “trailer” that points to decisive detail
For 2026, the market offers a balance of steady growth and targeted disruption. The top-line trajectory is attractive and predictable, but the real value will accrue to companies that can operationalize recyclability, manage feedstock volatility, and navigate accelerating regulatory frameworks. PW Consulting’s report equips executives with the tactical playbooks, quantitative scenarios, and supplier-to-shelf tools needed to convert market dynamics into measurable advantage.
If your 2026 capital plans, product roadmaps or M&A pipeline are on the table this quarter, this study provides the evidence-based guidance you need to move from intent to action. The full report contains the complete set of segment-level forecasts, regional splits, proprietary pricing models, and downloadable implementation templates referenced above. Access to these proprietary exhibits is available on the report’s source webpage—our recommended next step for teams building a defensible 2026 plan.
For detailed analysis of this topic, please visit the official page: Worldwide Rigid Thermoform Plastic Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Over‑the‑Horizon Radar Market to Reach USD 1,753.6 Million by 2032, Expanding at a 6.5% CAGR
By pmarketresearch, 2026-07-17
Worldwide Over-the-horizon Radar Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
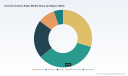
PW Consulting’s new market study on the Worldwide Over‑the‑horizon (OTH) Radar Market delivers an evidence‑based, operationally oriented playbook for defense planners, prime contractors, and national procurement teams planning decisions in 2026. The global OTH radar market has expanded materially over the past half‑decade — growing from roughly USD 825 million in 2020 to an estimated USD 1,128 million (USD Million, base year 2025). Under the scenarios modeled in this report, the market resumes growth across the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.5%, reaching roughly USD 1,754 million by 2032. That trajectory reflects a combination of defense modernization spending, new Arctic and Indo‑Pacific sensor deployments, and a wave of technology refresh and sustainment programs.
Worldwide Over-the-horizon Radar Market
Why this report matters for 2026
-
Timing: The coming 12–24 months are decisive. Several national programs are transitioning from concept and environmental review into procurement and construction phases; decisions taken in 2026 will lock in supplier ecosystems and platform architectures for a decade.
Worldwide Over-the-horizon Radar Market -
Investment focus: Governments are prioritizing long‑range, passive and active HF solutions to close gaps in northern approaches, maritime domain awareness, and strategic ballistic‑missile early warning. These programs translate into capital procurement, long‑term operations & maintenance (O&M) contracts and recurring upgrade budgets.
Worldwide Over-the-horizon Radar Market -
Technology inflection: Advances in digital beamforming, software‑defined radar, AI‑assisted signal processing, and modular open systems are changing the cost profile and upgrade cadence of OTH capabilities. Firms that align product roadmaps with these trends will capture higher lifecycle value.
Market dynamics driving demand
-
Geopolitical drivers: Renewed emphasis on continental and maritime approaches—particularly in Arctic and Indo‑Pacific theaters—has accelerated program planning by key NATO members and Pacific partners. Multinational technology transfer and partnership models (including cross‑government licensing of proven OTH architectures) are becoming the norm for rapid capability delivery.
-
Modernization and sustainment: Legacy networks are receiving a dual mandate—extend life through hardware upgrades while introducing software‑defined features that enable multi‑mission sensing, data fusion, and cyber‑resilience. This creates balanced demand across new system procurements and high‑value O&M workstreams.
-
Infrastructure and regulatory constraints: Site selection, environmental reviews, and spectrum coordination are material gating items. Several programs anticipated to move from planning to construction will require integrated project management capabilities that combine civil works, RF engineering, and stakeholder engagement.
-
Operational doctrine: Doctrine shifts toward integrated sensor networks and all‑domain awareness increase the premium on interoperability, common data models, and secure high‑bandwidth links between OTH assets and national command networks.
Competitive landscape — what procurement teams should read into it
The competitive structure of the OTH radar market is moderately concentrated: the top three incumbents control a substantial share of the market, while the top five capture a solid majority. That concentration favors established primes with systems integration track records, long histories of lifecycle support, and full‑stack capabilities (antennas, transmit subsystems, signal processing, and long‑duration O&M). Key industry actors include RTX Corporation (Raytheon), Lockheed Martin, Northrop Grumman, BAE Systems, Thales, Leonardo, Saab, Israel Aerospace Industries, and Aselsan.
-
Prime integrators: Firms with decades of OTH experience continue to win sustainment and upgrade work because they combine fielded test data, integrated logistics, and field operations teams. Their offers increasingly emphasize software upgradability and modular transmit/receive blocks to speed deployed improvements.
-
Regional system suppliers: European and regional suppliers are positioning specialized software, control systems, and HF surface‑wave elements as complementary offerings—particularly where sovereign supply chains or local content requirements drive procurement choices.
-
New suppliers and subsystems: Specialist suppliers are capitalizing on transmit‑subsystem and high‑power amplifier contracts associated with homeland defense programs. Contracting activity in early 2026 demonstrates a healthy market for subsystem builders as much as for full systems integrators.
Notable program and policy developments (contextual highlights)
-
High‑profile national programs are advancing from planning to execution, including Arctic and homeland defense OTH initiatives that explicitly reference technology partnerships and previously proven architectures. These programs are shaping demand signals for construction, transmit hardware, and long‑term sustainment.
-
Recent award activity in early 2026 shows both large O&M contracts and significant transmit‑subsystem procurements moving through defense acquisition pipelines—an indicator that both new builds and refresh cycles will contribute to market growth.
-
Regulatory timelines—environmental reviews, spectrum allocation, and construction approvals—are critical program dependencies. Procurement schedules that underestimate these steps risk schedule slippage and cost escalation.
Strategic imperatives for 2026 decision‑makers
Our research translates into eight practical priorities that should guide boardrooms and procurement offices this year:
-
Adopt lifecycle cost thinking: Evaluate proposals not only on acquisition price, but on 20‑ to 30‑year sustainment cost, software upgrade paths, and obsolescence risk. OTH systems deliver value through decades of operation—O&M terms are often where contracts create or destroy value.
-
Prioritize modular, software‑defined architectures: Insist on open‑architecture baselines and clear upgrade interfaces. This reduces vendor lock‑in and accelerates insertion of AI‑assisted signal processing and spectral management capabilities.
-
Lock in interoperability early: Define data and interface standards during RFP development. Programs that delay data standardization pay integration penalties during fielding and cross‑domain operations.
-
Factor environmental and permitting risk into schedule and cost: Build contingency for multiyear environmental reviews and community engagement in remote locations, particularly in Arctic and coastal sites.
-
Design for sovereign industrial participation: If domestic industrial benefits are required, structure contracts to phase capability handover and partner training, reducing risk while growing local sustainment capacity.
-
Stress‑test supply chains: High‑power RF components and civil works are potential chokepoints. Early vendor qualification and multi‑source strategies reduce schedule risk.
-
Plan for integrated resilience: Include cyber, EMI/EMCON, and anti‑spoofing requirements as part of the procurement baseline; secure command and control links are as critical as the radar apertures.
-
Use scenario‑based procurement: Procure with scenarios in mind (e.g., Arctic persistent surveillance, ballistic missile early warning, dark‑water maritime detection). Tailor acceptance tests to operationally relevant cases rather than lab metrics alone.
What PW Consulting’s report delivers (practical contents)
This study is designed to be prescriptive, enabling buyers and suppliers to act in 2026 with greater confidence. Core deliverables include:
-
A calibrated market model covering historical (2020–2025) performance and scenario‑based forecasts for 2026–2032 with sensitivity testing under alternative geopolitical and budgetary assumptions.
-
Vendor ecosystem maps and capability heatmaps that profile system integrators, specialty subsystem suppliers, and regional partners—scored against lifecycle support, modularity, and interoperability metrics.
-
A procurement playbook and RFP checklist that embeds requirements for open architecture, sustainment metrics, spectrum coordination, environmental compliance, and local‑industry participation.
-
Operational acceptance templates and test‑case libraries keyed to coastal surveillance, long‑range air surveillance, and early missile‑warning missions.
-
A contract‑readiness toolkit for governments and primes (including O&M contracting approaches, warranty structures, and handover schedules) to reduce delivery risk and cost overruns.
-
Scenario briefs and decision trees for planners evaluating when to procure, upgrade, or retain legacy OTH assets versus investing in alternative long‑range sensing architectures.
Concluding perspective
For organizations making allocation decisions in 2026, the OTH radar market presents both continuity and change. Continuity comes from sustained defense demand for long‑range awareness and the enduring value of fielded systems. Change comes from a confluence of geopolitics, modular software platforms, and a stronger emphasis on lifecycle sustainment and interoperability. PW Consulting’s study converts these dynamics into operational guidance: a quantified market view, procurement tools, vendor diagnostics, and practical decision frameworks to support executable plans.
Next steps
PW Consulting is publishing an executive briefing and an extended dataset that include full segmentation, detailed company profiles, and the interactive forecast model. The public summary above is intended to equip 2026 decision‑makers with the strategic context they need; the full report contains the granular inputs, supplier scorecards, and scenario models necessary to finalize procurements and supplier strategies. Visit our report page to access the complete deliverables and to request tailored advisory support for your program timeline.
For detailed analysis of this topic, please visit the official page: Worldwide Over-the-horizon Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aerospace Galley Trolley Market to Reach USD 462.79 Million by 2032, Growing at a 5.12% CAGR (2026–2032)
By pmarketresearch, 2026-07-17
Worldwide Aerospace Galley Trolley Market — Strategic Preview for 2026 Decisions
PW Consulting today releases a strategic preview tied to our full market research report on the Worldwide Aerospace Galley Trolley Market (base year 2025; forecast period 2026–2032). Designed as a decision-useful briefing for C-suite leaders, procurement heads, OEM program managers and private equity teams, this release synthesizes the report’s principal implications for corporate strategy in 2026 without disclosing the detailed segment-level tables that we reserve for licensed subscribers.
Worldwide Aerospace Galley Trolley Market
Snapshot: The market at a glance
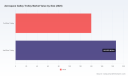
- Structural growth: The global market for aerospace galley trolleys is on a steady growth path. Our modeled series shows the market expanding from approximately USD 295.4 million in 2023 to an expected USD 326.25 million in 2025, progressing to roughly USD 462.79 million by 2032.
- Underlying momentum: We project a compound annual growth rate (CAGR) of 5.12% over the forecast window (2026–2032), driven by fleet renewal, aftermarket service expansion and material-driven weight-reduction programs.
- Concentration: The competitive landscape is moderately consolidated — the three largest suppliers represent a plurality of market share, and the top five capture a clear majority. This profile creates room for both scale players and specialized niche entrants.
Why this matters for 2026 strategy
- Fleet economics are reshaping demand. Airlines’ twin priorities — lower fuel burn and lower life-cycle costs — push procurement teams to reassess trolley specifications, replacement cadences and retrofit programs. Even modest per-unit weight savings compound materially across fleets and flight cycles.
- Sustainability is now procurement policy. Lightweight materials and recyclable designs translate into both operational emissions benefits for airlines and reputational capital for suppliers capable of providing verified life-cycle claims.
- Aftermarket services are a durable margin pool. Repair, overhaul and logistics for galley equipment increasingly represent a recurring-revenue channel for suppliers and third-party MROs — an attractive alternative to low-margin OEM part sales.
- Compliance and certification matter. Design choices are filtered through a compliance matrix of EASA, FAA and platform-specific OEM standards; certification timelines and costs materially affect time-to-revenue for new products.
What the full report delivers (practical detail, not platitudes)
- Proprietary forecast model — scenario-enabled: granular top-line projections with sensitivity levers for fuel price, passenger traffic recovery and retrofit rates.
- Commercial playbook: go-to-market strategies for OEM suppliers, aftermarket specialists and private equity, including pricing benchmarks and contract design templates.
- Supply chain heat-map: sourced components, single-point-of-failure suppliers, and near-term sourcing stress tests.
- Cost and TCO model: material and certification cost drivers mapped to lifecycle impact and ROI thresholds for airlines and lessors.
- Regulatory & testing matrix: certification pathways, test-lab requirements, and an implementation timeline template to de-risk product launches.
- Innovation scorecards: evaluated supplier competencies across lightweighting, modularity, digitalization (connected galley capabilities) and reparability.
- M&A playbooks and due-diligence checklists tailored to both strategic acquirers and financial sponsors.
Market dynamics shaping supplier and buyer behavior
Our research identifies four convergent dynamics that will determine winners in 2026:
Worldwide Aerospace Galley Trolley Market
- Material transition: Aluminum remains the established baseline given its repair ecosystem and proven track record, while advanced composites and honeycomb structures are the fastest-growing technology vector because they can deliver significant weight reductions versus metal equivalents.
- Regulatory compliance costs: Meeting EASA and FAA fire and burn-test regimes, together with platform-specific certifications, introduces a measurable cost uplift for suppliers. Buyers should expect certification effort and expense to be a gating factor for new entrants and innovative materials until test-data and repair practices are standardized.
- Aftermarket monetization: Suppliers that pair hardware with MRO, logistics and serialized tracking of assets capture higher lifetime value. There is a material arbitrage between one-off sales and bundled service offerings that forward-thinking suppliers are exploiting.
- Supply-chain resilience: Volatility in raw-material markets and concentrated sub-suppliers increases incentive for dual-sourcing, inventory policy redesign, and in some cases onshoring of critical fabrication steps.
Competitive landscape — how to read the field
The market features a mix of legacy system integrators, specialized manufacturers and service-oriented players. Our qualitative assessment highlights distinct strategic postures:
Worldwide Aerospace Galley Trolley Market
- Driessen Catering Equipment (Netherlands): A legacy player with deep domain expertise and a strong installed base. Their scale and long history in aircraft galley equipment make them a reference supplier for premium OEM and retrofit programs.
- Korita Aviation (China): A competitively priced manufacturer with OEM approvals and a product range that scales from full-size to folding trolleys. Strong for customers prioritizing cost and manufacturing flexibility.
- Egret Aviation (China): Focused on lightweight aluminum alloys and foldable designs; positioned where price-performance meets light-weighting requirements for cost-sensitive retrofits.
- DKA Aerospace (Singapore): Certifications across EASA/FAA and direct OEM relationships position DKA as a partner of choice for certified new-production content and regulated aftermarket programs.
- Bucher Leichtbau AG (Switzerland) and JAMCO (Japan): Known for high-quality galley systems and integration capability — attractive for platforms that demand system-level integration and OEM alignment.
- Unilode Aviation Solutions (Switzerland): Distinguishes itself through repair, logistics, and serialized asset management — a benchmark for service-led business models.
- Large systems players (Safran Cabin, Diehl Aviation, Collins Aerospace): Offer integrated cabin-and-galley solutions and are pushing connected-galley concepts that blend hardware with software value propositions.
Recent industry activity underscores these strategic tensions. For example, material experimentation continues to surface in public forums — a European supplier demonstrated honeycomb-cardboard compartment concepts at a major interiors expo in mid-2024 — signaling both the appetite for radical weight reduction and the practical challenge of proving durability and compliance.
Implications for product and corporate strategy in 2026
- Prioritize TCO, not unit cost. Airlines and lessors increasingly evaluate galley equipment on life-cycle metrics. Suppliers should develop transparent TCO models to differentiate bids.
- Lock-in certification pathways early. For materials innovations, design teams must budget time and capital for testing. Early engagement with certification bodies shortens commercialization cycles.
- Build aftermarket offerings. Suppliers that can bundle repair, refurbishment and logistics will extract higher margins and deepen customer relationships.
- Invest selectively in materials R&D. Composites offer clear fuel-burn advantages, but the commercial case depends on certification risk, repairability, and total cost over asset life.
- Consider scale through partnerships. Given moderate market concentration, smaller suppliers should pursue strategic alliances or carve-outs to access OEM platforms or expanded distribution networks.
- Digitalize assets. Connected galley capabilities can create new service-led revenue streams (predictive maintenance, usage-based billing) and are a differentiator for OEM and airline customers.
Recommended near-term actions for 2026
- Run a focused pilot to validate composite or hybrid trolley designs under your certification scope; use the pilot to collect data for repair-process definition and TCO inputs.
- Establish a repair-and-refurbishment playbook to monetize end-of-life assets and shorten replacement cycles.
- Map supplier single points of failure for critical alloy and subcomponent supplies; implement dual-sourcing where feasible.
- Quantify the value of connected-galley features for your customers and model subscription vs. capex commercial structures.
- Prioritize targets for bolt-on M&A or commercial partnerships that strengthen certification capabilities, test-lab access, or aftermarket capacity.
How PW Consulting can help
Clients who license the full report gain access to: the complete segmented forecast and underlying model (editable), supplier scorecards with performance and certification audits, a procurement negotiation toolkit, and bespoke scenario workshops tailored to your corporate planning cycle. The public preview above highlights the report’s strategic value while withholding the granular segment and regional breakdowns that form the actionable intelligence required for competitive bidding and private-equity diligence.
Base year: 2025. Forecast period: 2026–2032. Currency: USD (Million).
To obtain the full report, the editable forecast model, and advisory engagement options for 2026 planning, please visit the PW Consulting publications page or contact your PW Consulting account executive for an executive brief and licensing details.
For detailed analysis of this topic, please visit the official page: Worldwide Aerospace Galley Trolley Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Inorganic Pigments for Cosmetics Market Set to Grow at a 5.15% CAGR, Unlocking New Opportunities Through 2032
By pmarketresearch, 2026-07-17
Worldwide Inorganic Pigments for Cosmetics Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest market study — the Worldwide Inorganic Pigments for Cosmetics Market — synthesizes five years of historical performance (2020–2025) and an actionable forecast horizon (2026–2032) to equip executive teams, procurement leads, and R&D managers with the intelligence required to make high‑stakes choices in 2026. The market reached approximately USD 950 million in our base year (2025) and, under the central scenario, is projected to grow at a compound annual growth rate (CAGR) of roughly 5.15% to exceed USD 1.35 billion by 2032. These headline metrics set the context for tactical priorities: securing feedstock, accelerating compliant product development, and calibrating commercial strategies for a slowly consolidating industry (CR3 ~38.5%; CR5 ~52.1%).
Worldwide Inorganic Pigments for Cosmetics Market
Why this report matters for 2026
- Timing: 2026 is a pivot year — macro pricing dislocations, raw‑material volatility and evolving "clean beauty" expectations converge to create windows of opportunity and risk for incumbents and new entrants alike.
- Decision focus: Profitability levers in 2026 will be tied to cost‑to‑serve optimization, formulation differentiation, regulatory positioning, and selective vertical integration of feedstock or specialty treatment capacities.
- Actionability: The study is designed as a decision‑support tool rather than an academic exercise — it delivers scenario-calibrated forecasts, supplier scorecards, and implementation playbooks tailored to the unique margin structures of cosmetic‑grade inorganic pigments.
Key data signals and market trajectory
After five straight years of expansion, the industry shows steady, mid‑single‑digit growth into the forecast period. Our base‑case projection, reflecting product substitution dynamics and premiumization in color cosmetics, suggests the market moves from a near‑billion‑dollar base in 2025 to a significantly larger addressable pool through 2032. Competitive concentration has increased moderately, indicating room for both scale players and high‑specialty suppliers to capture differentiated value.
Worldwide Inorganic Pigments for Cosmetics Market
Two data points that materially influence 2026 planning are raw‑material and price signals. Titanium dioxide (TiO2) feedstock markets have experienced recent oversupply pressure, with Q4 2025 North American TiO2 prices softening — a dynamic that ripples into margins for TiO2‑based cosmetic grades and creates tactical buying opportunities for agile procurement teams. Separately, global export price benchmarks for pigment materials signal ongoing competitive pressure at the commodity end of the value chain, reinforcing the need for product and service differentiation.
Worldwide Inorganic Pigments for Cosmetics Market
Market dynamics that will drive boardroom debates
- Raw‑material volatility and vertical exposure: Ilmenite/rutile price swings continue to affect TiO2 economics. Manufacturers with integrated feedstock access or flexible tolling arrangements will be better positioned to defend margins.
- Regulatory intensity and quality thresholds: Cosmetic formulations are increasingly scrutinized for heavy‑metal impurities and trace contaminants. Compliance with FDA/EU cosmetics standards is table stakes; transparency on impurity profiles and certification (e.g., ISO 16128/COSMOS for certain claims) will be differentiators.
- Premiumization and effect pigments: Demand for pearlescent, high‑brilliance, and hybrid inorganic–organic effect pigments in premium color cosmetics will support higher ASPs for qualified suppliers, provided they can validate stability and sensory performance in finished formulations.
- Sustainability and circularity: Upcycled feedstocks and bio‑derived treatments are moving from PR headlines to procurement RFIs. Suppliers that can demonstrate credible life‑cycle benefits while maintaining regulatory compliance will gain traction with brand teams.
Supply chain and sourcing implications
Procurement leaders must re‑optimize sourcing strategies in 2026 around three axes: price volatility hedging, technical qualification velocity, and supplier risk diversification. The report includes elasticity analyses and a raw‑material sensitivity matrix that quantify margin exposure to TiO2 and iron oxide price moves under multiple purchase‑term scenarios. Our client work shows that a blended strategy — combining short‑term opportunistic buys with strategic long‑term agreements and conditional capacity reservations — materially outperforms single‑track approaches when feedstock swings are frequent.
Product, formulation and technology trends
- Hybrid effects and nanotechnology: Several leading suppliers have launched next‑generation pearlescent and effect pigments that leverage nanoscale engineering to enhance brilliance and coverage while meeting safety thresholds. These innovations are becoming a route to premiumization for color cosmetics.
- Surface treatments and dispersibility: Surface‑treated inorganic pigments that improve sensory feel and pigment dispersion remain a central R&D investment area. Faster qualification cycles for treated pigments can shorten time‑to‑market for brand customers.
- Clean‑beauty compatible chemistries: Bio‑derived pigment coatings and lower‑impurity production routes are moving into commercial release, creating choices for formulators who demand both performance and sustainability credentials.
Competitive landscape — what executives need to know
The report profiles the market’s strategic players, focusing on capabilities that matter to cosmetics customers: purity and impurity control, regulatory track record, surface treatment technology, sustainability credentials, and global supply reliability. Representative vendor snapshots include major diversified chemical manufacturers, specialty pigment houses, and regional pure‑play suppliers. Recent strategic moves underline the competitive priorities:
- Product innovation at scale — BASF and Merck have unveiled advanced effect pigments and UV‑optimized offerings aimed at the premium cosmetics segment, signaling continued investment in high‑value differentiated chemistries.
- Clean and upcycled supply propositions — Sun Chemical (DIC) and Clariant are moving aggressively on upcycled and bio‑derived pigment options to capture the sustainability‑minded brand segment.
- Regional capability plays — Several players from Asia and India are expanding certified cosmetic‑grade portfolios to capture fast‑growing formulation demand and reduce customer qualification cycles for regional brand partners.
For C‑suite readers, two implications follow: (1) scale alone will not guarantee share gains in premium color cosmetics unless paired with validated regulatory and sensory performance; (2) smaller, agile suppliers can command premium pricing if they can shorten qualification time and document sustainability benefits.
Practical contents of the PW Consulting report
The study is deliberately operational. It contains the following deliverables designed to translate insight into action for 2026:
- Market sizing and high‑resolution forecast (2026–2032) with scenario variants (base, downside, upside) and sensitivity testing around feedstock price and regulatory shocks.
- Supplier scorecards that benchmark purity, regulatory certifications, surface‑treatment capabilities, geographic production exposure, and customer service metrics.
- Raw‑material risk matrix and procurement playbook, including recommended contracting structures, hedging approaches, and a decision tree for tolling versus in‑house production.
- Formulation compatibility matrix and technical risks checklist to accelerate laboratory qualification cycles for new pigment grades.
- M&A and partnership shortlists: screened targets and alliance archetypes with indicative integration roadmaps and synergy buckets (cost, revenue, R&D acceleration).
- Regulatory compliance playbook: actionable checklists for global rollout (EU, US, APAC) including testing regimes and impurity disclosure templates for customer onboarding.
- Go‑to‑market 100‑day plan for entrants and expansion plans for incumbents seeking to monetize premium effect pigments or sustainability claims.
Recommended strategic moves for 2026
- Prioritize dual‑track sourcing: negotiate flexible volume collars with incumbents while qualifying one or two regional specialists to reduce single‑sourcing risk.
- Invest in accelerated qualification: allocate targeted capex to co‑development labs that accelerate validation timelines for surface‑treated and hybrid pigments.
- Layer sustainability into pricing: quantify life‑cycle benefits and seek price premiums where evidence supports claim substantiation, particularly for upcycled or bio‑derived pigment grades.
- Design product portfolios around risk: separate commodity TiO2 and core iron oxide offerings from high‑margin effect and treated pigments, with differentiated go‑to‑market motions and margin targets.
- Monitor regulatory trajectories closely: maintain a rapid response protocol for heavy‑metal thresholds and labeling changes to avoid costly reformulations or market access delays.
Recent market developments that sharpen 2026 choices
Industry headlines through late 2025 and early 2026 highlight the themes above: multiple product launches of advanced effect pigments, new bio‑derived pigment introductions, and supplier announcements that prioritize purity and compliance for cosmetics. These moves illustrate supplier strategies that pair technical differentiation with sustainability narratives — a combination that materially affects brand sourcing preferences and premium capture.
How PW Consulting supports your 2026 playbook
Clients engage with PW Consulting for pragmatic intelligence that translates directly into boardroom decisions. Our proprietary models and supplier diligence protocols reduce execution risk and shorten the time from insight to contract. For 2026, we are offering tailored advisory packages that include live sourcing workshops, formulation qualification sprints, and M&A diligence support calibrated to inorganic pigments for cosmetics.
Note: This article intentionally provides high‑level strategic insights and suppresses granular segment allocations and proprietary sub‑segment figures that are included in the full report. For the full dataset, interactive dashboards, and downloadable supplier scorecards, please consult the official report page and contact our industry team to arrange a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Inorganic Pigments for Cosmetics Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Microencapsulated Paraffin Phase Change Materials Market to Grow at 13.52% CAGR, Hit USD 486 Million in 2025 and Top USD 1.18 Billion by 2032
By pmarketresearch, 2026-07-17
Worldwide Microencapsulated Paraffin PCM Market: Strategic Imperatives for 2026
As organizations race to embed energy efficiency and thermal intelligence across buildings, textiles, electronics and thermal storage systems, microencapsulated paraffin phase change materials (microPCM) have moved from niche lab curiosity to commercial lever. PW Consulting’s new market study — built on a 2020–2025 historical base and projecting through 2032 — quantifies that transition and translates it into actionable strategy for 2026 decision-makers.
Worldwide Microencapsulated Paraffin Phase Change Materials Market
Snapshot: What the numbers tell us (without giving everything away)
- The global microencapsulated paraffin PCM market has more than doubled in five years: from a modest industry tally in 2020 to nearly half-a-billion USD (base year 2025) in revenue. Our model anticipates continued momentum into the forecast window, with the market roughly doubling again by 2032.
- Growth is robust: the market is projected to expand at a compound annual growth rate (CAGR) of approximately 13.5% over the 2026–2032 forecast period — a rate that signals sustained commercial interest and multiple inflection opportunities for suppliers, integrators and end-users.
- Competitive structure is moderately concentrated: the top-tier players capture a meaningful share of sales while a mid-tier of specialized manufacturers and technology providers remain influential. This dynamic creates both scale advantages and openings for focused innovators.
Why this matters for 2026 strategy
For industrial strategists, procurement leads, product development executives and investors, the market metrics above are not mere vanity statistics — they are a directional guide to resource allocation in 2026. Key strategic implications include:
Worldwide Microencapsulated Paraffin Phase Change Materials Market
- Demand predictability: the size and growth trajectory validate investments in application-specific formulations and encapsulation capacity. Organizations that can match tailored PCM properties to end-use performance requirements will win the highest-margin contracts.
- Supply-chain sensitivity: paraffin feedstock pricing and regional availability remain key operational levers. Recent cycle volatility tied to crude-derived feedstocks has introduced margin variability, making sourcing strategies and hedging important near-term priorities.
- Sustainability and differentiation: bio-based polymer shells and lower-carbon paraffin routes are not just regulatory plays — they are commercial differentiators in tendering processes for green buildings, sustainable textiles and environmentally conscious OEMs.
- Integration over commodity-selling: the most durable opportunities lie where microPCM are integrated into finished systems (e.g., façade boards, smart textiles, battery modules) rather than sold as standalone powders. Partnerships with OEMs and systems integrators will accelerate uptake.
Report coverage — what you’ll find inside (practical deliverables)
PW Consulting’s study was designed as a practitioner's guide. The report synthesizes primary interviews, proprietary supply-chain mapping, material-cost modelling and techno-commercial case work to deliver useable outputs, including:
Worldwide Microencapsulated Paraffin Phase Change Materials Market
- Market sizing and conservative/optimistic scenario forecasts by product form, shell chemistry and application group (2020–2032).
- Supply-side playbook: manufacturer profiles, capacity maps, technology readiness assessments and white-space opportunity matrices.
- Raw material sensitivity analysis and a rolling-cost model that links paraffin and polymer feedstock swings to product margin bands.
- Commercial playbooks for embedding microPCM into building envelopes, HVAC components, technical textiles and battery thermal management systems — including sample ROI and payback templates.
- Regulatory and standards landscape: implications for certifications, fire performance and sustainability claims in major markets.
- M&A and partnership scouting framework with scorecards for target screening (technology fit, route-to-market, manufacturing footprint).
- Actionable risk register and mitigation strategies covering feedstock price shocks, scaling challenges, and IP/encapsulation quality risks.
Competitive landscape: what incumbents and challengers are doing
The market is populated by a mix of chemical majors, specialty PCM houses and regional manufacturers. Our company-level intelligence highlights how different players are positioning themselves for 2026 opportunities:
- Microtek Laboratories (Dayton, Ohio, United States; https://www.microteklabs.com): Established specialist with a diverse microPCM portfolio targeted at building materials, textiles and electronics. Their depth in paraffin-based microPCM and established customer relationships make them an important bellwether for demand trends.
- Rubitherm Technologies GmbH (Berlin, Germany; https://www.rubitherm.eu): European organic PCM manufacturer focused on construction and cold-chain applications. Rubitherm’s product development emphasizes integration with thermal energy storage systems and industrial applications.
- Croda International Plc (Snaith, United Kingdom; https://www.crodaindustrialspecialties.com): Broad-based specialty chemicals player pushing bio-based microPCM solutions. Their CrodaTherm line highlights the strategic pivot toward sustainable formulations valued by premium customers.
- PCM Products Ltd (United Kingdom; https://www.pcmproducts.net): Niche PCM producer with solutions across HVAC and thermal storage segments. Strong in applications requiring certification and proven fire/safety performance.
- Andores New Energy CO., Ltd (China; https://www.andores.com): Regional manufacturer with competitive cost structures, supplying microencapsulated paraffin for cold chain and building applications — a key participant in Asia’s scaling story.
- Honeywell International Inc. (Charlotte, NC, United States; https://www.honeywell.com): Leveraging systems expertise, Honeywell is integrating microPCM into intelligent HVAC and building control ecosystems — an example of the shift to system-level offerings.
- Encapsys, PureTemp, Climator, Phase Change Energy Solutions and other specialists: These players provide targeted encapsulation technologies, bio-based PCM alternatives and sector-specific solutions (textiles, battery thermal management, façade products).
Recent sector moves underscore the momentum: major chemical and technology firms have launched new microencapsulated paraffin product lines, expanded partnerships with HVAC and building systems OEMs, and announced bio-based initiatives. These developments accelerate commercialization and raise the bar on product validation for scale.
Segment dynamics and raw-material context (strategic takeaways only)
Rather than enumerating granular regional or application share data, our analysis maps qualitative drivers across the segments that matter:
- Building and construction: Regulatory pressure for energy efficiency and occupant comfort actively pushes façade, wallboard and insulation manufacturers to pilot microPCM-enhanced products. Procurement timelines are medium-term and dependent on certification pathways.
- Textiles and apparel: Demand is driven by premium performance wear and temperature-regulating consumer goods; product differentiation is achieved through encapsulation stability and wash durability.
- Electronics and battery thermal management: This is a high-growth technical application where reliability and thermal cycling performance are critical. Qualification cycles are longer, but payoffs for successful integrations are significant.
- Thermal energy storage systems: Macro and microPCM combinations are used to improve charge/discharge control and reduce system footprint; opportunities are project- and policy-driven.
On the raw-material front, paraffin feedstock pricing and regional availability continue to be principal sources of margin volatility. European feedstock pricing has tended to be at the upper end of the range, with North American and Asia variations influenced by local refining dynamics and crude feedstock movements. For procurement managers, this demands a dual approach: (1) diversified sourcing with contractual protections and (2) exploration of bio-based or alternative shell chemistries to reduce exposure.
What PW Consulting recommends companies do in 2026
We translate market intelligence into a prioritized action agenda for leadership teams:
- Fast-track application pilots that couple microPCM performance metrics with clear ROI frameworks — prioritize applications where simplicity of integration and short payback can be demonstrated.
- Lock in strategic supply agreements for paraffin and shell polymers with price-adjustment mechanisms; evaluate co-located manufacturing near major customers to reduce logistics and ensure rapid qualification cycles.
- Invest in encapsulation quality and cyclability testing as a means to differentiate — superior encapsulation reduces replacement costs and warranty exposure.
- Partner with systems integrators (HVAC, textile brands, battery OEMs) rather than selling commodity powders; embed PCM into solution bundles to capture lifecycle value.
- Assess acquisition or JV targets using our scoring framework to accelerate capability acquisition in bio-based shells, encapsulation IP or regional manufacturing footprints.
- Implement a scenario-based pricing and inventory strategy to manage raw-material volatility, and model the P&L impact of feedstock swings under multiple demand scenarios.
How the report helps with executive decision-making in 2026
PW Consulting’s market study is structured to inform board-level and commercial decisions with consequence: it reduces uncertainty around demand sizing, provides procurement-tested costing tools, and gives operators a step-by-step roadmap to scale production and commercialization. The report’s scenario modelling allows executives to stress-test capital allocation choices — from greenfield encapsulation lines to partnership-driven go-to-market pilots — under a range of realistic macro and commodity trajectories.
Next steps and how to obtain the detailed intelligence
This release is a strategic preview designed to surface the essential implications of the microencapsulated paraffin PCM market for 2026. To access the full dataset, granular segmentation tables, company revenue benchmarks, exhaustive competitive profiles and the actionable spreadsheets used in our sensitivity modelling, please consult PW Consulting’s report page or contact our sales team. The complete report contains the comprehensive figures and appendices necessary for transactional diligence, procurement negotiations and R&D prioritization.
In a market expanding at double-digit CAGR and shifting from material-level innovation to system-level impact, 2026 will separate speculative suppliers from those who can operationalize performance at scale. PW Consulting’s study equips you to be in the latter group.
For detailed analysis of this topic, please visit the official page: Worldwide Microencapsulated Paraffin Phase Change Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Automotive Inertial Systems Market to Rise from USD 4,250.0 Million in 2025 to USD 8,484.42 Million by 2032 at a 10.38% CAGR
By pmarketresearch, 2026-07-17
PW Consulting Releases Worldwide Automotive Inertial Systems Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on Worldwide Automotive Inertial Systems provides an evidence-based strategic roadmap for companies planning capital allocation, product roadmaps, supply‑chain decisions, and M&A activity in 2026 and beyond. The global market for automotive inertial systems — encompassing accelerometers, gyroscopes, and integrated inertial measurement units (IMUs) used across ADAS, stability control, navigation and safety systems — reached approximately USD 4.25 billion in 2025. Under our baseline scenario the market expands to roughly USD 8.48 billion by 2032, representing a compound annual growth rate (CAGR) of 10.38% over the forecast window. The sector is already moderately concentrated (CR3 ≈ 54.2%; CR5 ≈ 76.5%), but competitive dynamics are accelerating as incumbents and challengers reposition for higher-value autonomous and navigation-grade opportunities.
Worldwide Automotive Inertial Systems Market
Why this matters in 2026
-
Electrification and ADAS proliferation: The increase in vehicle electrification and ADAS penetration is raising average inertial sensor content per vehicle. Inertial sensors are no longer purely “background” components — they are integral to sensor fusion stacks, vehicle dynamics control, and autonomy verification.
Worldwide Automotive Inertial Systems Market -
Regulatory and qualification pressure: Functional safety (ISO 26262) and automotive qualification (AEC‑Q) requirements are imposing longer validation timelines and higher engineering costs on sensor suppliers and OEM integration programs. Safety-critical ASIL-B through ASIL-D qualifications are table stakes for IMUs used in vehicle control and autonomous functions.
Worldwide Automotive Inertial Systems Market -
Supply‑chain and materials constraints: MEMS inertial sensors depend on semiconductor-grade substrates; the global silicon wafer market (a key upstream input) was valued at approximately USD 15 billion in 2024–2025, and capacity competition is emerging as automotive demand competes with broader semiconductor demand.
-
Rising value of navigation-grade solutions: As autonomy ambitions grow, demand shifts from commodity MEMS to higher-performance inertial systems and sensor fusion packages, creating tiering within supplier value chains and margin dispersion.
What the report delivers (practical, action-ready content)
-
Proprietary market sizing and 2026–2032 forecasts with scenario sensitivity testing (conservative / baseline / accelerated adoption scenarios).
-
Supplier landscape and capability matrix: technology readiness, ASIL and AEC‑Q qualifications, production footprint, and typical OEM engagement models.
-
Commercial & procurement playbook: cost modeling for IMU and gyroscope assemblies, total cost of ownership comparisons across sourcing options, contractual levers to mitigate lead‑time and price volatility.
-
Technology roadmaps and product road‑testing checklist: MEMS performance ceilings, GNSS/INS fusion architectures, FOG/RLG positioning use cases, and verification regimes for safety-critical deployments.
-
M&A and partnering heatmap: target profiles, integration risks, and value-creation levers for strategic buyers, financial sponsors, and corporate development teams.
-
Supply‑chain risk register: wafer supply scenarios, single-source exposures, qualification timelines, and recommended dual-sourcing strategies.
-
Regulatory compliance guide: mapping of ISO 26262 and AEC‑Q requirements to product development milestones and procurement gating criteria.
Competitive landscape: what we found
The market is anchored by established Tier‑1 and semiconductor players that combine deep automotive qualifications with scale manufacturing. At the same time, focused MEMS specialists and defense/aerospace suppliers are pushing into automotive via crossover opportunities and targeted funding. Our analysis profiles primary players across technology, production footprint, safety credentials and commercial positioning — and identifies where winners will extract premium value.
-
Robert Bosch GmbH (Germany) — Bosch remains a leader in automotive MEMS IMUs and high-reliability sensors, with strong integration into ADAS and vehicle dynamics stacks. Their ASIL-D capable offerings and broad OEM relationships make Bosch a default primary supplier for safety‑critical programs, but high-tier pricing and long qualification lead times present opportunities for agile competitors on lower-cost, high-volume platforms.
-
Continental AG (Germany) — Continental’s focus on 6DoF inertial sensors and sensor-fusion ECUs positions them as an integrator for chassis control and diagnostics. Their recent partnerships underline a strategy to move up the value chain through software-enabled analytics and AI-driven diagnostics — a competitive vector for suppliers willing to co-develop platforms.
-
STMicroelectronics N.V. (Switzerland) — Following the strategic acquisition of an NXP MEMS unit in 2025, ST is consolidating volume MEMS capability with enhanced production scale. Their combination of automotive-grade MEMS, AI-enabled processing, and wafer supply control strengthens their position in both commodity and differentiated IMU segments.
-
Honeywell, Analog Devices, Safran, Northrop Grumman — These players bring high-performance and navigation-grade solutions, often crossing from aerospace and defense. Their strength is in precision and reliability rather than low-cost volume; they are preferred partners for premium and development programs requiring navigation-grade performance.
-
TDK (InvenSense), Murata, ACEINNA, Sensata — These suppliers occupy the broad middle: from high-volume automotive MEMS to feature-rich 6-axis IMUs. Recent product launches and partnerships suggest a push for broader distribution and system-level integration with GNSS and odometry partners.
-
Startups and niche players — Funding activity in 2025 (e.g., iNGage) highlights continued VC interest in high‑performance multi-axis MEMS for autonomous systems. These entrants can be acquisition targets or technology partners for OEMs seeking to accelerate roadmap gaps.
Recent market movements to watch
-
Strategic M&A and consolidation of MEMS lines — exemplified by STMicroelectronics’ acquisition activity — is reshaping manufacturing capacity and product portfolios.
-
Product launches and partnerships from established MEMS vendors (e.g., TDK’s automotive 6-axis IMU and Trimble collaboration) are accelerating system-level integration and shortening time-to-deployment for fused navigation solutions.
-
Tier‑1s are moving from component procurement to platform co‑development; Continental’s recent co‑development announcements reflect this trend.
Supply-chain and regulation: practical impacts for 2026 budgeting
Qualification timelines for AEC‑Q and ISO 26262 compliance add measurable calendar and cost premiums to new sensor introductions. OEMs and suppliers must model multi‑year lead times for validation and factor in wafer‑capacity risk tied to the broader USD 15 billion silicon wafer market. Our report provides a probabilistic model for supply constraints (and mitigation options such as multi-sourcing, captive fabs, or inventory buffering) and quantifies the margin and cash-flow implications for different sourcing strategies.
Technology trajectories and use-case segmentation
MEMS-based inertial solutions remain the dominant technology vector for mainstream ADAS and vehicle stability functions because of their favorable cost, size and scalability. Navigation-grade applications — including high-precision dead-reckoning for autonomous stacks and premium navigation — continue to pull demand toward higher-performance FOG/RLG or fused MEMS with advanced calibration and AI-based error compensation. Our report maps realistic performance-improvement curves for each technology path, and shows when hybrid approaches (e.g., MEMS + occasional high-grade aiding) become more economical than direct replacement of navigation-grade sensors.
Strategic recommendations for 2026
-
OEMs: Move from transactional procurement to strategic supplier partnerships for IMUs. Lock down ASIL-compliant suppliers early in program timelines; make investment decisions that prioritize supplier capacity verification and co‑development clauses to secure differentiated capabilities.
-
Tier‑1s and system integrators: Invest now in software and AI layers that extract value from inertial data (diagnostics, drift compensation, cybersecurity-aware fusion). Packages that combine sensor hardware with analytics will command margin premiums.
-
Semiconductor & MEMS suppliers: Consider selective vertical integration or long-term wafer agreements to de‑risk upstream constraints. Prioritize AEC‑Q and ISO 26262 certifications to shorten OEM qualification cycles and reduce go-to-market friction.
-
Investors and M&A teams: Target bolt-on assets that fill roadmap gaps (e.g., advanced calibration algorithms, navigation-grade MEMS die, or AI fusion middleware). Expect consolidation around players that can deliver both qualification credentials and volume scale.
-
Procurement leaders: Revisit total cost models to include qualification amortization, warranty exposure for safety-critical functions, and supply‑chain resilience costs. Contract structures should balance capacity guarantees, price transparency, and technical support obligations.
How PW Consulting’s report supports 2026 decision-making
Our study is designed as a decision-support tool — not just a market scoreboard. Clients receive the forecast models, supplier scorecards, procurement playbooks, and scenario toolkits necessary to: quantify the financial impact of supplier choices; prioritize R&D and capex decisions; stress-test M&A cases against supply-chain disruption scenarios; and align safety‑qualification timelines with product launch schedules. The study intentionally leaves detailed sub-segment tables and proprietary supplier revenue splits out of the public briefing to preserve the competitive value of the primary dataset; full access to the data tables and vendor-level revenue models is available through the report portal.
Next steps and call to action
For executives planning budgets, strategic partnerships, or M&A activity in 2026, the time to model inertial‑system risk and opportunity is now. PW Consulting’s Worldwide Automotive Inertial Systems Market report equips leaders with the evidence, scenario tools, and supplier intelligence required to make confident, time‑sensitive decisions. To review the full dataset, vendor revenue models, and the procurement playbook that underpins our recommendations, please consult the report gateway where the comprehensive segment breakdowns and interactive forecast tools are available.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Inertial Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Arthroscopy Simulator Market Poised to Expand at a 9.15% CAGR, Unlocking New Training Opportunities
By pmarketresearch, 2026-07-17
Worldwide Arthroscopy Simulator Market — Strategic Imperatives for 2026
PW Consulting’s newest market study on the Worldwide Arthroscopy Simulator Market distills five years of observed adoption dynamics (2020–2025) and delivers an actionable 2026–2032 forecast with frameworks designed for immediate operational use. The report quantifies a clear upward trajectory: the market has grown steadily through 2025 and, under our base-case assumptions, is set to expand at a compounded annual growth rate of 9.15% across the 2026–2032 forecast window. For executive teams planning capital allocation, product roadmaps, training partnerships or M&A activity in 2026, the implications are material — and time-sensitive.
Worldwide Arthroscopy Simulator Market
Market trajectory at a glance
-
Observed momentum (2020–2025): Consistent year-on-year expansion driven by curriculum integration, increasing institutional procurement and early deployment of portable VR solutions.
Worldwide Arthroscopy Simulator Market -
Near- and medium-term outlook (2026–2032): Under our central forecast the market continues to scale, reflecting broader acceptance of simulation-based credentialing, continued regulatory clarity for medical-training devices, and technology convergence between tactile models, augmented reality and portable virtual reality.
Worldwide Arthroscopy Simulator Market -
Concentration profile: The market exhibits moderate concentration; top-tier vendors account for a meaningful share of revenue and influence through partnerships with professional societies and hospital systems. Market consolidation, vertical partnerships and licensing deals are expected to increase strategic differentiation.
Why 2026 is a strategic inflection point
Several converging forces make 2026 a decision year for both incumbent vendors and new entrants:
-
Curriculum and credential alignment: Leading professional bodies have begun embedding simulation into proficiency-based curricula and exams, shifting procurement from discretionary training tools to mission-critical certification infrastructure.
-
Regulatory and validation tailwinds: Increasing regulatory clarity for training devices (e.g., pathway requirements in major markets) and a growing evidence base of construct validity for established platforms reduce purchaser risk and accelerate institutional adoption.
-
Technology displacement dynamics: Portable wireless VR solutions and hybrid AR/tactile platforms are lowering access barriers, enabling decentralized training models (on-site, mobile units, and remote programs) that change total cost of ownership calculus for buyers.
-
Service and outcome expectations: Buyers are prioritizing validated measurement, learning analytics and integration into clinical curricula — not just hardware — creating recurring revenue opportunities for vendors that can deliver software-as-a-service and managed training programs.
What PW Consulting’s report delivers (practical content summary)
The report is structured to be operationally useful on day one. Key deliverables include:
-
Proprietary market sizing and a 2026–2032 forecast model with scenario levers for regulatory shifts, adoption rates and unit economics.
-
Segmentation frameworks across geography, product type and end-user, with purchase-cycle mapping and demand drivers. (Note: detailed segment-level data and revenue splits are reserved for the full report.)
-
A validated vendor matrix profiling product capabilities, customer references, unit economics and go-to-market footprints.
-
Regulatory and reimbursement landscape mapping, including key clearance/certification pathways and regional compliance checklists.
-
Operational playbooks for training adoption: procurement checklists, pilot KPIs, validation protocols and integration timelines.
-
M&A and partnership heatmap with valuation considerations and diligence templates for strategic buyers and financial investors.
Competitive landscape — strategic read-throughs
Our competitive analysis highlights several distinct strategic archetypes among active suppliers and the implications for 2026 planning:
-
Platform integrators with society-level footprint: Vendors that combine validated curricula, measurable performance metrics, and formal partnerships with professional societies occupy a privileged position for large institutional contracts. Such firms derive competitive advantage from clinical validation and endorsement networks that reduce buyer friction.
-
Portable VR innovators: Solutions that decouple simulation from fixed hardware — particularly wireless/mobile VR offerings — are reshaping addressable markets by enabling low-cost, high-frequency training at the point of need. Partnerships between simulator developers and device OEMs/distributors accelerate deployment in decentralized training models.
-
High-fidelity / tactile specialists: Providers that deliver realistic haptic feedback and anatomical fidelity appeal to high-acuity training programs; however, their value proposition increasingly depends on measurable training outcomes and integration with digital assessment tools.
-
Regional and niche suppliers: Local manufacturers and training-model suppliers retain importance for institutions seeking cost-effective or deeply localized solutions, particularly where service, maintenance and language/localization are critical.
Recent market actions underline these dynamics: society-led mobile simulation programs and manufacturer partnerships to deliver portable VR training are accelerating institutional trials and procurement cycles. Longitudinal validation studies for some established platforms continue to be cited as decisive evidence in procurement decisions.
Implications for incumbents and new entrants
-
Incumbents: Protect validated advantages by packaging competence-based curricula, performance analytics and managed educational services. Invest selectively in portability and cloud-enabled analytics to capture recurring revenue streams and to defend against lower-cost mobile entrants.
-
New entrants: Focus on narrow, defensible use-cases where portability or price-performance materially expands addressable demand. Establish early partnerships with training programs and societies to accelerate validation and create reference customers.
-
Service companies and integrators: There is a rising opportunity to offer ‘simulation-as-a-service’ programs (including mobile simulators, on-site training, and assessment services) to bridge the gap between vendors and large institutional buyers.
Actionable recommendations for 2026 decision-makers
For executive teams preparing 2026 plans, we recommend the following prioritized actions:
-
Manufacturers — product and commercial strategy:
-
Prioritize modular, upgradeable architectures that support both tactile and VR modes to maximize addressable use-cases.
-
Design subscription pricing and managed-service bundles that align vendor success with institutional training outcomes (e.g., per-credential, per-learner models).
-
Secure validation partnerships with leading academic centers and specialty societies early to accelerate procurement cycles.
-
-
Hospitals & training centers — procurement and integration:
-
Run staged pilots that measure learning transfer and time-to-competency using standardized KPIs before committing to fleet purchases.
-
Embed simulators into mandatory credentialing and CME pathways to ensure utilization rates and to justify capex/opex.
-
Negotiate total-cost-of-ownership contracts including training, support and software updates rather than device-only purchases.
-
-
Investors & corporate development:
-
Prioritize targets with demonstrated institutional partnerships, recurring revenue models and validated clinical outcomes.
-
Perform diligence on data‑governance, integration APIs and regulatory pathway readiness — these are common deal-breakers post-acquisition.
-
Go-to-market playbook highlights
-
Leverage society endorsements and certification pilots to build referenceability; use co-branded pilot outcomes to shorten sales cycles.
-
Bundle hardware with outcome‑linked analytics and service-level agreements to transition buyers from capex-led to opex-led purchasing.
-
Localize service and maintenance footprints in target markets to minimize downtime and maximize program utilization.
-
Invest in comparative validation studies and publish measurable improvements in learner performance to reduce buyer uncertainty.
How PW Consulting accelerates your 2026 decisions
Our report pairs empirical demand modelling with operational playbooks so leaders can convert market forecasts into executable plans. If your 2026 priorities include launching a portable training product, negotiating institutional contracts, or evaluating acquisition targets, PW Consulting’s study provides the scenario-tested frameworks, procurement templates and valuation heuristics required to act with confidence.
For a detailed view of market splits, proprietary modeling assumptions and vendor scorecards (including performance, pricing and contract archetypes), access the full Worldwide Arthroscopy Simulator Market report and our interactive forecast model on PW Consulting’s publications page.
For detailed analysis of this topic, please visit the official page: Worldwide Arthroscopy Simulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com