

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Power Distribution Modules Market Poised to Expand at a 7.6% CAGR

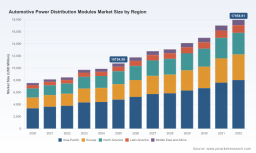
Worldwide Automotive Power Distribution Modules Market — Strategic Outlook for 2026 Decision‑Making
PW Consulting’s latest market study on Worldwide Automotive Power Distribution Modules (PDMs) equips senior executives, purchasing directors, and investment committees with a practical, decision‑ready perspective for 2026. Built on a five‑year historical base (2020–2025) and a seven‑year forecast window (2026–2032), the report combines rigorous market-sizing, scenario modelling, supply‑chain stress tests and competitive intelligence to translate market dynamics into concrete strategic options.
Worldwide Automotive Power Distribution Modules Market
Market trajectory: what the headline numbers mean for strategy
The global PDM market has transitioned from volume recovery to structural growth. Our model shows the market advancing from a 2020 baseline through a 2025 anchor point of approximately USD 10.8 billion (revenue unit: Million, USD base) and entering the forecast phase at roughly USD 11.8 billion in 2026. Across the 2026–2032 horizon the market is projected to grow at a compound annual growth rate of 7.6%, reflecting accelerating electrification, tighter safety and cybersecurity standards, and OEM architecture re‑platforming.
Worldwide Automotive Power Distribution Modules Market
For executives, the implication is clear: 2026 is not merely a continuation year — it is a pivotal planning year to lock in supplier relationships, allocate R&D budgets for next‑generation high‑voltage topologies, and implement procurement strategies resilient to raw‑material and regulatory shocks. The growth profile supports selective capacity expansion and targeted technology investments, but success hinges on anticipating non‑linear risks (regulatory, material and technological) rather than assuming steady demand alone.
Worldwide Automotive Power Distribution Modules Market
Key market forces shaping 2026 decisions
- Electrification architecture upgrades — Vehicle electrical architectures are evolving rapidly toward higher voltages and integrated power management. OEMs are converging on modular high‑voltage PDMs for modular platforms, driving demand for suppliers capable of scaling both hardware and embedded software.
- Regulatory and safety imperatives — New safety requirements for high‑voltage corridors and ingress protection, combined with vehicle network cybersecurity mandates, are raising qualification thresholds for PDMs. Compliance timelines in 2026 will define supplier shortlists and accelerate consolidation among firms with mature validation programs.
- Material and manufacturing pressures — Commodity cycles and component supply constraints remain salient. Copper cost inflation and a shift toward aluminum conductors (which reduce system weight but introduce joining and thermal challenges) force buyers to reconfigure cost models and supplier capabilities.
- Software and systems integration — The PDM is increasingly a cyber‑physical component. Suppliers that offer both robust hardware and secure, updateable software stacks will command premium positions in OEM selection processes.
Practical intelligence contained in the report
The report is designed for operational use in 2026 planning cycles. Key deliverables include:
- Robust market sizing and topline forecasts with sensitivity bands to capture downside commodity and regulatory outcomes.
- Scenario planning tools — including a “fast‑EV” and a “regulated safety” scenario — that translate regulatory and material shocks into revenue and margin outcomes at the supplier and OEM level.
- Supplier scorecards and technology readiness matrices that evaluate electrical performance, thermal management, IP maturity and cybersecurity posture.
- Supply‑chain heat maps and logistics risk indices enabling procurement teams to prioritize dual sourcing, localization or strategic inventory policies where warranted.
- Detailed playbooks for OEMs and Tier‑1s on qualification timelines, testing corridors for high‑voltage compliance and cybersecurity checklists aligned with recent UN/ECE and EU requirements.
- Capital allocation frameworks and a shortlist of acquisition/partnership targets consistent with a mid‑consolidation market (CR3 ~38.4%; CR5 ~52.2%).
Competitive landscape: what to watch in 2026
The market exhibits moderate concentration, leaving meaningful openings for technologically differentiated challengers. Our competitive review profiles leading Tier‑1s and system suppliers — analyzing strengths, go‑to‑market models, and recent strategic moves that will influence sourcing and partnership decisions in 2026.
- Aptiv (Ireland) — Strong in smart junction boxes and high‑voltage systems; recent product launches for 800V architectures position Aptiv to capture EV platform upgrades where high‑voltage scaling is a priority.
- Yazaki Corporation (Japan) — Deep wiring harness and PDM experience across vehicle segments; supplier nominations for high‑profile OEM programmes signal continued traction in core vehicle platforms.
- Sumitomo Electric Industries (Japan) — Integrated wiring and PDM supplier to global OEMs; offers advantages where harness‑module integration reduces assembly complexity.
- Motherson Group (India) — Rapidly expanding electrical power management capabilities through dedicated divisions; competitive on local content strategies for regional OEMs.
- Leoni AG (Germany) — European wiring and module specialist with engineering strength in integrated systems for premium segments.
- Furukawa Electric (Japan) — Focused on compact PDMs for hybrid and electric powertrains; competitive in space‑constrained vehicle architectures.
- Lear Corporation (USA) — E‑Systems supplier moving into integrated power distribution through strategic development agreements with major OEMs.
- Denso Corporation (Japan) — Supplier depth in ECU‑integrated power management with strong global OEM relationships.
- BorgWarner (USA) — Specialised in high‑voltage modules for electrified powertrains; recent vehicle integrations showcase production experience for EV platforms.
- Valeo (France) — Offers holistic thermal and electrical systems for both ICE and EV platforms, enabling cross‑architecture leverage.
Notably, recent industry moves — from Aptiv’s next‑generation 800V module to supplier nominations and joint developments — highlight a market where product innovation and close OEM collaboration determine selection. The report dissects these moves to show where capability overlaps create choke points for OEMs and where targeted partnerships can shorten time‑to‑production.
Actionable recommendations for executives planning 2026
- For OEM procurement leads — Reframe RFPs to include software lifecycle terms and cybersecurity KPIs. Prioritize suppliers with proven high‑voltage validation programs and documented production readiness; use staged sourcing to align volume ramps with regulatory certification milestones.
- For Tier‑1 suppliers — Invest selectively in advanced joining technology and thermal‑management IP to support aluminum conductor designs. Build modular product lines that can be firmware‑upgraded to meet evolving safety and cybersecurity standards.
- For investors and M&A teams — Target assets that fill capability gaps — particularly in embedded software, high‑voltage safety testing and lightweight conducting technologies. The current concentration metrics suggest attractive bolt‑on opportunities to scale revenues without immediately triggering antitrust scrutiny in all jurisdictions.
- For manufacturing and operations — Implement commodity hedging strategies and supplier diversification for critical conductors. Localize production in high‑priority regions where lead times and regulatory compliance create competitive advantage.
- For R&D and product strategy — Prioritize certification roadmaps against UN/ECE high‑voltage and EU cybersecurity standards. Parallelize hardware and software development to reduce time‑to‑market and maintain upgradeability.
Risk scenarios and mitigation
The report models three downside shocks: a prolonged commodity price surge, a regulatory acceleration that shortens certification windows, and an integration failure scenario where early adopters face thermal or EMC setbacks. For each, we provide contingency playbooks — covering accelerated qualification, temporary design freezes, and emergency supplier swaps — to preserve production timelines and limit margin erosion.
Practical mitigation measures include: pre‑qualifying dual suppliers for critical conductors, setting aside strategic inventory for platform launches, and embedding accelerated test gates in development sprints so that software patches and hardware rework can be sequenced without full vehicle re‑engineering.
Why this report matters for 2026
2026 will be the year when architectural choices harden for the next generation of electrified platforms. Decisions made in 2026 will influence vehicle BOMs, supplier ecosystems and capital allocations for years to come. PW Consulting’s report is constructed to support those decisions: it converts macro growth (7.6% CAGR through 2032), regulatory inflection points and competitive dynamics into prioritized, executable moves — while preserving the confidential, granular segmentation that OEMs and suppliers use internally.
If you need a framework to decide where to invest, whom to partner with, or how to structure procurement and supply‑chain resilience programs for PDMs in 2026, this study delivers both the analytical backbone and the operational playbooks. For full segment breakdowns, supplier scorecards, interactive dashboards and the complete dataset used to build the scenarios, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Power Distribution Modules Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com