

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide Anorectal Manometry Devices Market to Grow from USD 248.5 Million in 2025 to USD 372.43 Million by 2032 at a 5.95% CAGR
By pmarketresearch, 2026-07-17
Worldwide Anorectal Manometry Devices Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s newest market study on Worldwide Anorectal Manometry Devices synthesizes a multi-year evidence base and primary intelligence to deliver actionable guidance for commercial leaders, clinical program directors, investors, and health-system procurement teams planning for 2026 and beyond. The market is small but dynamic: after a baseline of USD 248.5 Million in 2025, our base-case projection anticipates continued expansion to roughly USD 372.4 Million by 2032, implying a compounded annual growth rate of approximately 5.95% over the forecast window. Those headline trajectories reflect a confluence of technology migration (toward high-resolution and disposable solutions), reimbursement and coding shifts, and an evolving competitive landscape where a handful of specialist suppliers exert meaningful influence.
Worldwide Anorectal Manometry Devices Market
Market at a Glance: What the Numbers Mean for Strategy
-
Growth trajectory: The market’s mid-single-digit CAGR signals steady demand driven by increasing clinical recognition of anorectal physiology testing, broader adoption of high-resolution platforms, and incremental penetration of office-based portable systems. The near-term step-up in market size ending 2025 forms the base from which 2026 strategies should be calibrated.
Worldwide Anorectal Manometry Devices Market -
Concentration: Market concentration metrics indicate that a limited set of companies capture a meaningful share of industry revenue — enough to shape standards, channel behavior, and pricing dynamics, yet leaving room for targeted innovators to displace legacy incumbents in defined niches.
Worldwide Anorectal Manometry Devices Market -
Adoption inflection points: The combined impact of device-level innovation (disposable catheters, compact HRAM platforms, and portable manometry) and clarified regulatory pathways is shifting where and how testing is delivered — from tertiary centers toward ambulatory and office-based workflows — creating new go-to-market and clinical integration imperatives.
What the PW Consulting Report Contains — Practical, Implementable Intelligence
-
Market sizing and forecasts (2020–2032) with scenario modeling. We provide base, conservative, and accelerated cases to stress-test investment and commercial plans against reimbursement and adoption variability.
-
Channel and customer strategy playbooks for hospitals, diagnostic centers, specialty clinics, and distributor partners — including service, training, and consumables models that materially affect lifetime revenue.
-
Regulatory and reimbursement tracker: a timeline of 510(k) clearances and evolving CPT code policy, plus an impact assessment that links coding change to revenue cycle and capital procurement behavior.
-
Competitive landscaping and capability maps. We profile device architectures (high-resolution vs conventional vs portable), productized software/analytics, disposables strategy, and clinical evidence footprints for the leading suppliers.
-
Technology and clinical adoption playbooks: criteria for prioritizing R&D bets (e.g., disposable HRAM catheters, integrated balloon expulsion protocols, combined EMG sensing), and a recommended evidence-generation roadmap to accelerate payer acceptance and guideline inclusion.
-
M&A and partnership advisory: target screens and integration checklists for acquirers seeking either scale in consumables and service or capability enhancement in analytics and point-of-care instrumentation.
Key Competitive Themes and Strategic Implications
The market is characterized by a mix of legacy device makers and agile entrants focused on portability and disposables. Notable participants include manufacturers with established high-resolution platforms, vendors specializing in portable manometry optimized for office workflows, and regional producers that compete on cost and channel relationships. Recent product and regulatory developments underscore the pace of change:
-
Disposable HRAM systems and compact high-resolution platforms have moved from concept to commercialization — exemplified by recent product launches that make single-use catheters available in clinical practice. This materially changes procurement economics (less reprocessing capital, different consumable models) and infectious disease mitigation policies in institutional settings.
-
Portable devices that reduce procedure time and support office-based testing have received regulatory clearances, opening new uptake corridors among smaller practices and enhancing access for patients with mobility or access barriers.
For established vendors, the strategic choice is how aggressively to transition to consumables-driven revenue models and software-enabled services. For challengers, the playbook is carve-out clinical niches (e.g., pediatric programs, rapid bedside screening, or bundled pelvic floor therapy) and partner with clinical champions to accelerate guideline adoption.
Regulatory and Reimbursement Shifts — A 2026-Ready Checklist
-
Regulatory clarity: Anorectal manometry devices continue to be regulated as Class II gastrointestinal motility monitoring systems under existing product codes, with 510(k) marketing pathways being the primary route to U.S. entry. Recent clearances for portable systems reinforce that the pathway is viable for novel form factors.
-
Coding and reimbursement: A significant coding update effective January 1, 2026 replaces legacy procedure codes with new Category I codes that redefine how anorectal manometry procedures are described and reimbursed. This change requires immediate action from billing, contracting, and clinical documentation teams to avoid revenue leakage and to capture procedure complexity appropriately.
-
Standards and clinical protocols: High-resolution systems are increasingly aligning with community-driven protocols and classifications — alignment that accelerates adoption but also raises the bar for vendors on interoperability and analytics accuracy.
Actionable Strategic Imperatives for 2026
-
For product leaders: prioritize modular architectures that support both high-resolution core systems and disposable catheter lines. The capacity to offer bundled service plans and predictable consumable economics will be a differentiator in buyer procurement cycles.
-
For commercial teams: redesign go-to-market motions to address office-based clinicians and ambulatory surgery centers. Shorter procedure times, simplified workflows, and training bundles lower friction for adoption — metrics buyers can measure immediately.
-
For clinical affairs and R&D: invest in comparative clinical evidence that maps device features to guideline-relevant endpoints (e.g., defecatory disorder diagnostics, balloon expulsion concordance, pelvic floor biofeedback outcomes). Payer coverage decisions are increasingly evidence-driven.
-
For health systems and procurement: run scenario-based TCO analyses that incorporate consumable utilization, reprocessing costs, and staff time. The apparent unit price of a device can be misleading without modeling the service and consumables run-rate over a 3–5 year horizon.
-
For investors and M&A teams: target capabilities that accelerate recurring revenue — disposables manufacturing, cloud-enabled analytics, or clinic network access — rather than one-time capital sales alone. Integration risk is highest for acquisitions that lack a clear consumables or service upsell path.
Competitive Snapshot — Who’s Shaping the Market
Core incumbents and nimble challengers are blending device innovation with clinical workflow solutions. Examples of technology and strategic positioning observed in our analysis include:
-
Manufacturers of high-resolution platforms that emphasize diagnostic precision, integration with IAWG protocols, and classification frameworks — positioning that supports referral-center adoption and specialist workflows.
-
Global medical device majors offering high-density probes and 3-D mapping features for advanced physiological assessment, generally aligned with tertiary diagnostic centers and research programs.
-
Portable system vendors targeting office-based and ambulatory care with compact hardware and simplified test protocols — accelerating access and procedural throughput.
-
Regional suppliers and specialty firms that compete on tailored service models, local clinical relationships, and price-performance options.
Profiles and capability matrices for named competitors — from established HRAM platform vendors to portable-system innovators and specialized catheter manufacturers — are included in the full report, together with a detailed assessment of each player’s R&D pipeline, regulatory filings, and channel reach.
How PW Consulting’s Report Helps You Move from Insight to Decision
-
Immediate deliverables: executive decision memos, prioritized capability roadmaps, and a procurement checklist tailored to device life-cycle and consumables economics — all structured to be actionable within a 90‑day planning cycle.
-
Scenario toolkits: models that let you stress-test pricing, reimbursement, and adoption assumptions to quantify upside and downside across 2026–2032 horizons.
-
Implementation briefings: operational playbooks for clinical training, coding transitions, and supplier contract renegotiations tied to the January 2026 coding update and related payer policies.
Closing — Why This Report Is a 2026 Essential
Decisions taken in 2026 — about product roadmaps, evidence programs, channel investments, and capital procurement — will determine who captures the next wave of growth in anorectal manometry. PW Consulting’s study synthesizes the quantitative market trajectory, regulatory inflection points, and competitive moves to create a pragmatic blueprint for leaders who need to convert insight into market advantage without getting lost in raw data. We intentionally preserve granular segment tables for the full report to ensure commercial confidentiality and to provide subscribers with the precise, auditable figures they need for contracting and valuation.
To access the detailed segment breakdowns, company profiles, methodology appendix, and scenario models that underpin this strategic preview, please visit the PW Consulting report page or contact our advisory team for a briefing and tailored executive summary.
For detailed analysis of this topic, please visit the official page: Worldwide Anorectal Manometry Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Bipolar Plate Fuel Cell Market to Surge from USD 1,933.55 Million in 2025 to USD 9,219.88 Million by 2032 at a 25.04% CAGR
By pmarketresearch, 2026-07-17
Worldwide Bipolar Plate Fuel Cell Market — Strategic Outlook for 2026
PW Consulting’s new market study, “Worldwide Bipolar Plate Fuel Cell Market,” provides a focused, decision-ready perspective for executives and investors planning capital allocation, product strategies, and partnerships in 2026. Built on a 2025 base year and grounded in a 2020–2025 historical dataset, the study projects the market through 2032 and models the structural forces shaping material choices, manufacturing scale-up, and customer adoption curves. This release highlights the macro trajectory and strategic imperatives revealed in our analysis while withholding detailed regional and application splits to encourage access to the full report.
Worldwide Bipolar Plate Fuel Cell Market
Market Snapshot: Rapid Expansion, Structural Inflection
The bipolar plate market is experiencing an accelerated adoption phase. After steady growth through the early 2020s, the market surged in the 2023–2025 period and reached USD 1,933.55 Million (revenue unit: Million USD) in 2025. Our forecast indicates sustained momentum: the market is expected to expand at a compound annual growth rate (CAGR) of 25.04% across the 2026–2032 forecast window, reaching USD 9,219.88 Million by 2032. These headline figures reflect not only rising demand for fuel cell systems across mobility and stationary power, but also intensified investment in high-volume manufacturing, material innovations, and stack-level integration.
Worldwide Bipolar Plate Fuel Cell Market
Concentration metrics underscore opportunities and competitive pressure. The market exhibits moderate concentration—top-three suppliers account for roughly 38.5% of value, and the top five capture approximately 52.15%—leaving room for new entrants that can deliver demonstrable cost, durability, or integration advantages.
Worldwide Bipolar Plate Fuel Cell Market
Why the 2026 Inflection Matters for Corporate Strategy
-
Capital allocation: With stacked annual growth and clear cost-down pathways, 2026 is a critical year for firms to decide between scaling internal manufacturing vs. partnering for outsourced, ready-to-install plates. Our analysis quantifies breakeven volumes and capex payback windows under multiple automation and coating scenarios.
-
Material strategy: Material choices—metallic, graphite, composite—carry distinct trade-offs across weight, manufacturability, cost, and corrosion management. The market is not “one-size-fits-all”: heavier-duty and stationary systems prioritize durability and recyclability, while light-duty mobility emphasizes weight and cost per kW. Our scenario models show how small shifts in adoption mix materially change supplier economics and raw-material procurement needs.
-
Manufacturing scale and automation: Regulatory and programmatic targets (for example, DOE guidance on manufacturing throughput) are pushing suppliers toward high-throughput systems. The U.S. DOE’s manufacturing benchmarks suggest single production systems capable of thousands of plates per hour at full maturity—targets that meaningfully affect footprint, tooling, and labor strategies.
-
Regulatory alignment and standards: International standards (notably the IEC 62282 series and national adaptations) and DOE technical targets for plate cost, weight, permeability, and corrosion behavior are shaping product specifications upstream. Firms that align development roadmaps to these specifications de-risk customer qualification and accelerate adoption.
What the Report Delivers — Practical, Actionable Content
-
Market modeling and forecasting engine: Transparent assumptions and sensitivity testing across scenario sets (base, accelerated adoption, and downside demand shock) enabling rapid recalculation of revenue and margin outcomes under alternative policy and technology shifts.
-
Cost and technology ladders: Detailed cost-driver breakdowns (materials, coatings, forming, secondary operations, and assembly) and roadmap pathways to meet DOE and industry cost targets—allowing procurement and R&D teams to prioritize interventions with the highest ROI.
-
Manufacturing playbooks: Benchmarked production concepts from pilot lines to automated high-throughput systems, including equipment capex ranges, floor-space envelopes, throughput gating points, and time-to-volume estimates.
-
Competitive supplier matrix: Vendor profiling across capabilities—material expertise, coating technologies, forming methods, geographic footprint, and commercialization status—paired with an executable partner-screening framework for OEMs and integrators.
-
Regulatory and standards mapping: A pragmatic guide that aligns product specs with relevant international and national standards, plus a compliance checklist to accelerate product certification and market entry.
-
Investment and M&A dashboard: Valuation comparables, M&A themes (vertical integration, IP consolidation, and localization), and trigger scenarios that make bolt-on acquisitions or greenfield investments compelling.
Competitive Landscape: Who’s Driving Innovation and How
Our industry mapping identifies a diverse set of incumbents and scale-up specialists, each positioning along different points of the value chain. The following executive snapshots summarize strategic plays observed in 2024–2026 that matter for 2026 decision-making:
-
Ballard Power Systems Inc. (Burnaby, Canada) — Focus: Graphite bipolar plates. Ballard is advancing scaled production strategies and cost reductions for next-generation graphite designs aimed at heavy-duty and stationary markets. Their emphasis on high-volume graphite production remains a benchmark for durability-focused applications.
-
Dana Incorporated (Maumee, United States; Neu-Ulm operations, Germany) — Focus: Metallic bipolar plates and electrolyzer components. Dana’s recent product launches combine precision forming with advanced coatings and integrated sealing; the company is positioning metallic plates as enablers for higher power density and lower system cost in green hydrogen applications.
-
SGL Carbon (Wiesbaden, Germany) and Schunk Carbon Technology (Heuchelheim, Germany) — Focus: Graphite and composite plates with high-volume capabilities. Both firms are scaling manufacturing to meet automotive and energy segment demand while protecting performance characteristics.
-
ElringKlinger / EKPO Fuel Cell Technologies (Dettingen/Erms, Germany) — Focus: Metallic plates and high-power stacks. EKPO’s product announcements of higher-power stacks with improved bipolar plates underline a push into heavy-duty transport and stationary solutions requiring recyclability and enhanced power density.
-
Feintool (Lyss, Switzerland; Taicang, China operations) — Focus: High-volume ready-to-install metallic plates. Feintool’s production ramp and high-volume orders for commercial vehicle programs demonstrate the readiness of stamped-metal approaches for mobility scale-up.
-
Cell Impact AB and Impact Coatings AB (Karlskoga & Linköping, Sweden) — Focus: Flow plate manufacturing technology and advanced coatings. Their capabilities are central to enabling cost-effective, corrosion-resistant metallic plates at scale.
-
Borit NV, GrafTech, POCO Graphite (Entegris), Nisshinbo Chemical, Shanghai Hongfeng — Focus: Material supply and specialty graphite/composite expertise. These players remain critical upstream suppliers as OEMs balance cost and performance trade-offs.
-
Schaeffler (Herzogenaurach, Germany) and Hutchinson (Paris, France) — Focus: Integrated solutions and sealing innovations. Strategic projects such as Hutchinson’s OBI-1 and Schaeffler’s Enertect-coated components highlight the move toward integrated, lower-cost fuel cell subsystems.
Recent Developments That Move the Needle
-
Product launches and orders: 2025–2026 saw multiple announcements of high-volume orders and product launches for metallic plates and stacks, signaling commercial momentum in mobility and stationary segments. Notable activity includes new electrolyzer plate offerings, high-volume manufacturing orders, and stack power-density improvements that alter system economics.
-
Pilot and scale-up demonstrations: Research institutes and industrial partners have showcased pilot plants and production demonstrations focused on rapid, cost-effective plate manufacture—reducing time-to-volume and enabling earlier qualification cycles for OEMs.
-
Standards and targets alignment: DOE technical targets and international standards are increasingly referenced by buyers as part of procurement criteria; suppliers aligning to these metrics are shortening the path to commercialization.
Strategic Recommendations for 2026 Decision-Makers
-
Prioritize modular production investments that can pivot between metal and composite flowplate lines. Flexibility will preserve optionality as customer specifications and material economics continue to evolve.
-
Invest in coatings and integrated sealing capabilities or secure tier-one partnerships to mitigate corrosion and contact-resistance risks—two failure modes that materially affect warranty costs and lifecycle performance.
-
Build supplier linkages for raw-material access (graphite powders, stainless and coated steels) and qualify multiple sources early to avoid single-point supply disruptions as volumes ramp.
-
Embed regulatory and standards compliance into product roadmaps. Aligning early to DOE and IEC targets will reduce qualification cycles with OEMs and expedite procurement wins.
-
Adopt staged expansion playbooks: pilot → contract-manufacture → brownfield expansion → greenfield automation. This minimizes cash exposure while enabling rapid capacity scaling when offtake is confirmed.
Closing: Why the Full Report Is a Necessity for 2026 Planning
This market snapshot conveys the macro trajectory and the practical levers that will determine winners over the next investment cycle. PW Consulting’s full report contains the underlying datasets, regional and application splits, supplier scorecards, detailed cost curves, and executable roadmaps that will enable procurement, R&D, and corporate development teams to make defensible 2026 spending and partnership decisions. To access the complete market tables, sensitivity models, and supplier benchmarking that we intentionally withhold here as part of this preview, please consult the full “Worldwide Bipolar Plate Fuel Cell Market” report.
For detailed analysis of this topic, please visit the official page: Worldwide Bipolar Plate Fuel Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Alginate Dressing Market Poised for 5.24% CAGR to 2032 as Chronic Wound Demand Surges
By pmarketresearch, 2026-07-17
Worldwide Alginate Dressing Market: Strategic Outlook to 2032 — A PW Consulting Preview
As healthcare providers and medtech suppliers confront accelerating demand for advanced wound care solutions, alginate dressings have moved from specialty use toward a core position in exudate management protocols. PW Consulting’s latest market study — covering historical performance from 2020–2025 and a detailed forecast for 2026–2032 — frames the alginate dressing market as a resilient, mid-single-digit growth opportunity. Our proprietary modelling shows the market value expanding at a 5.24% CAGR through the forecast window, with the industry base validated against 2025 market metrics and multiple macroeconomic and clinical scenarios.
Worldwide Alginate Dressing Market
Market snapshot: resilience underpinned by clinical fundamentals
Alginate dressings remain differentiated by their unique gelling behavior: extracted polysaccharide fibers derived from brown seaweed form a gel on contact with wound exudate, enabling absorption multiples relative to their dry weight and supporting moist wound-healing environments. Clinical practice patterns — including the need for secondary dressings and standard indications for partial- and full-thickness wounds with moderate-to-heavy exudate — continue to anchor alginates in both acute and chronic care pathways.
Worldwide Alginate Dressing Market
After navigating volatility in the early 2020s, the market’s aggregate value strengthened into 2025. PW Consulting’s baseline indicates a robust rebound and steady growth through 2032 under our core case. The market structure exhibits moderate concentration: the top three players account for roughly 41.5% of industry sales, while the top five approach 57.8%, underscoring meaningful advantages for scale players alongside differentiated opportunities for niche innovators and regional specialists.
Worldwide Alginate Dressing Market
Why this matters for 2026 corporate decision-making
-
Investment timing: With a projected mid-single-digit CAGR, 2026 represents a pivotal year for deciding between capacity expansion, targeted M&A, or focused R&D bets. The pace of growth supports conservative capacity additions for incumbents, while premium niche opportunities reward focused product development (e.g., antimicrobial or high-gel-strength variants).
-
Regulatory and supply-chain risk calibration: Recent regulatory events and the concentrated supply base for alginate feedstock mean procurement strategies and lot-level quality controls must be elevated. Our report provides a risk matrix that quantifies financial exposure across recall scenarios, enabling CFOs and procurement leads to stress-test supplier portfolios.
-
Go-to-market sequencing: The clinical use-cases for alginates — spanning chronic wound clinics, acute-care settings, and home healthcare — require distinct distribution and reimbursement playbooks. PW Consulting’s scenario maps help commercial teams prioritize channel investments that maximize near-term revenue while protecting long-term margins.
What the PW Consulting report delivers (practical, actionable content)
-
Executive frameworks: Clear, decision-focused frameworks for executives to evaluate build vs. buy vs. partner paths, including NPV sensitivities keyed to pricing, adoption, and reimbursement shifts.
-
Competitive playbooks: Tactical recommendations for market incumbents, challenger brands, and new entrants — from SKU rationalization and clinical evidence generation to tender strategies and clinician engagement models.
-
Commercial readiness tools: Channel prioritization matrices, sample sales scripts tailored to wound-care procurement committees, and value-based contracting templates designed for private payers and hospital systems.
-
Regulatory and quality checklists: Practical compliance roadmaps covering HCPCS coding nuances and lot-management best practices for manufacturers and distributors.
-
Supply-chain and raw-material intelligence: A sourced supplier map for alginate feedstock, cost-driver breakdowns, and mitigation pathways for seaweed-derived input volatility and quality variability.
-
Forecast scenarios and sensitivity analyses: Best-, base- and downside cases for 2026–2032 that model pricing pressure, accelerated adoption of silver-impregnated variants, and the clinical impact of competing advanced dressings — available with drill-down capability in the full dataset.
Competitive landscape: how incumbents and challengers are positioning
The sector is characterized by a mix of global medtech majors, specialist wound-care firms, and regional manufacturers. Several well-known players have product portfolios spanning calcium, calcium-sodium and silver-impregnated alginate variants; they deploy differing strategies across product innovation, clinician education, and channel reach.
-
Global distributors and diversified medtech companies continue to leverage scale advantages in procurement, clinical trial funding, and multi-channel distribution. Their playbooks emphasize broad product suites and clinical evidence that support hospital formularies.
-
Specialist wound-care firms focus on differentiated formulations (e.g., reinforced gelling fibers, antimicrobial-embedded dressings) and clinical programs that target niche segments such as diabetic foot ulcers and pressure injuries.
-
Regional manufacturers, including several high-quality suppliers out of Asia and Europe, compete on cost and fast time-to-market for new SKUs. Their market impact is amplified by regulatory clearances in key jurisdictions and participation in major trade shows.
PW Consulting’s competitive profiles synthesize public product claims and recent corporate activity to distill where each firm’s true advantage lies — whether material science, distribution scale, or clinical engagement. Notable developments that influence strategic positioning include a voluntary product removal announced in early 2026 for a calcium alginate product line — a reminder of the reputational and financial consequences of contamination events — and increased visibility for several Chinese manufacturers following major trade show participation in 2025.
Regulatory, coding and raw-material dynamics
On the reimbursement front, alginate and other fiber-gelling dressings are typically represented by HCPCS codes used for wound covers and fillers in settings that treat moderate- to high-exudate wounds. This coding landscape matters for product labeling, billing strategies, and hospital formulary negotiations. Additionally, quality events can have outsized impact: our regulatory-impact scenarios quantify revenue at risk from lot-level recalls and outline rapid-response playbooks to minimize downstream disruption.
Raw-material constraints warrant strategic attention. Alginate feedstock, sourced from brown seaweed or kelp, is subject to seasonal harvest variability and geographic concentration. The material’s attractive clinical performance — absorbing many times its own weight in exudate — coexists with supply-side fragilities that can compress margins in periods of constrained harvests or elevated shipping costs. PW Consulting’s supplier-risk heat maps and contractual templates help procurement teams lock in supply while retaining flexibility.
Strategic moves for different stakeholders
-
For incumbents: Prioritize lifecycle management of existing alginate SKUs, invest in clinical evidence for higher-margin formulations, and develop bundled-service offerings (training, wound-assessment tools) to defend formulary positions.
-
For challengers and innovators: Focus on differentiated material science (e.g., higher gel strength, antimicrobial integrations) and narrowly-targeted clinical claims that can justify premium pricing and rapid adoption among specialist clinics.
-
For private equity and strategic investors: Use the market’s moderate concentration as a lens for bolt-on consolidation plays that combine product portfolios with established distribution in underpenetrated regions.
-
For hospitals and group purchasing organizations: Leverage coding precision and performance benchmarks to negotiate bundled contracts that align unit pricing to observed clinical outcomes.
How to use this preview — and why the full report matters
This article provides a high-level view of the forces shaping the alginate dressing market through 2032. For leaders making 2026 decisions, the value lies in translating these strategic signposts into executable initiatives: capex allocation, R&D prioritization, supplier contracting, and commercial rollouts. PW Consulting’s full report converts the directional insights summarized here into operational tools — detailed regional demand models, SKU-level pricing benchmarks, risk-adjusted NPV calculations, tender-play templates, and clinician preference matrices — all designed to shorten time-to-decision and reduce implementation risk.
If your team is planning product launches, procurement restructures, M&A diligence, or pricing realignments in 2026, the detailed datasets and playbooks in the full study will materially change the speed and confidence of those outcomes. To preserve the integrity of strategic decision-making, the full report presents the granular segmentation and confidential company-level estimates not published in this preview.
Closing perspective
Alginate dressings occupy a pragmatic sweet spot in wound care: clinically established, technically differentiable, and strategically significant for organizations that manage exudate-heavy wounds at scale. The market’s steady growth trajectory — underpinned by fundamental clinical demand, product innovation, and a concentrated competitive structure — creates both defensive priorities for incumbents and targeted openings for innovators. PW Consulting’s Worldwide Alginate Dressing Market report equips decision-makers with the analytics, templates, and scenario playbooks required to act decisively in 2026 and beyond.
About PW Consulting
PW Consulting is a strategy advisory and market intelligence firm specializing in healthcare and medical technology. Our analysts combine primary research, proprietary forecasting models, and commercial playbooks to support executive decision-making. For access to the full Worldwide Alginate Dressing Market report, including the granular segmentation, company profiles and downloadable datasets, contact PW Consulting or visit our website.
For detailed analysis of this topic, please visit the official page: Worldwide Alginate Dressing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Pediatric Respiratory Syncytial Virus Infection Market Surges to USD 4,500 Million by 2025
By pmarketresearch, 2026-07-17
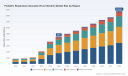
Worldwide Pediatric Respiratory Syncytial Virus (RSV) Infection Market — 2026 Strategic Preview
Executive summary
PW Consulting’s latest market research, “Worldwide Pediatric RSV Infection Market,” delivers a data-driven strategic foundation for corporate decision-making in 2026. Using 2025 as the base year, the study traces an accelerated adoption curve over 2020–2025 and provides a robust forecast across 2026–2032. The pediatric RSV prophylaxis and treatment market expanded from under USD 1 billion in 2020 to roughly USD 4.5 billion by 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of approximately 10.01% through the 2026–2032 forecast window. By 2032 the market is forecast to exceed USD 8.7 billion under our central-case assumptions.
Worldwide Pediatric Respiratory Syncytial Virus Infection Market
These topline dynamics are accompanied by a high degree of market concentration: as of the latest assessment the leading three companies command a dominant share of the market, with the top five firms controlling north of 90% of commercial activity — a structure that both accelerates commercialization momentum and raises strategic barriers for new entrants.
Worldwide Pediatric Respiratory Syncytial Virus Infection Market
Why this report matters for 2026 strategic decisions
-
Timing and prioritization: With multiple late-stage clinical programs and newly expanded regulatory labels, 2026 will be a critical year for sequencing clinical investments, launches and capacity commitments. The report pinpoints where momentum is concentrated, and where incremental investments produce the highest marginal returns.
Worldwide Pediatric Respiratory Syncytial Virus Infection Market -
Go-to-market trade-offs: Manufacturers must choose between maternal immunization campaigns, infant monoclonal prophylaxis, or supportive-care strategies. Each route has distinct commercial, regulatory and payer implications — our analysis clarifies where to allocate limited commercial resources for fastest adoption.
-
Pricing and reimbursement strategy: Rapid uptake in some markets is already being shaped by payer coverage decisions and list pricing dynamics. The report synthesizes pricing references, reimbursement precedents and value dossiers to inform negotiations and forecasting.
-
Supply chain and manufacturing planning: The industry has expanded RSV biologics production capacity materially, but capacity will be uneven geographically and by platform. Our modelling helps companies balance inventory, contract manufacturing arrangements and long-term capital projects to support 2026 launches and beyond.
Contents and practical deliverables in the report
This research is designed as a practical playbook, not just an academic exercise. Key modules include:
-
A transparent market-sizing model (base year 2025) with scenario engines to evaluate upside/downside cases driven by regulatory outcomes, adoption curves and pricing sensitivity.
-
Commercial launch blueprints tailored to each prophylactic approach: maternal vaccination, long-acting monoclonal antibodies, and supportive-care therapies. Each blueprint includes channel mix considerations, provider engagement tactics and lifecycle revenue levers.
-
Payer-access and HTA pathway maps for priority markets, with templated evidence packages and economic case structures to accelerate formulary inclusion.
-
Supply chain and manufacturing gap analysis, highlighting geographic chokepoints and mitigation options (contract manufacturing partners, fill-and-finish investments, inventory hedging).
-
Competitor playbooks and scenario-based win/lose matrices for M&A, licensing and co-commercialization strategies.
-
Real-world evidence (RWE) roadmaps and post-market surveillance frameworks to protect and extend market access.
Competitive landscape — what incumbents and challengers are doing
The pediatric RSV market is currently led by a small group of established biopharma companies and rapid innovators. Key strategic positions to note:
-
AstraZeneca (co-commercialized with Sanofi): Markets a long-acting monoclonal antibody for infant RSV prevention and has recently secured expanded authorization that broadens the eligible infant population entering their first RSV season. This regulatory expansion materially changes addressable demand profiles and strengthens tender and hospital-channel leverage.
-
Sanofi: As co-developer and commercial partner, Sanofi’s role remains central to lifecycle management, global rollout and manufacturing scale-up activities tied to the monoclonal product.
-
Pfizer: Leads the maternal vaccination strategy with a bivalent preF vaccine and has secured strong public-health endorsements that accelerate maternal immunization programs in several countries — a strategic channel that reshapes early-life protection approaches.
-
GSK: While primarily focused on an adult RSV vaccine, GSK’s platform and regulatory expertise mean sustained evaluation for pediatric indications and potential line-extension strategies.
-
Merck and Moderna: Advanced candidates — including monoclonal antibodies and mRNA-based vaccines — are moving through late-stage clinical development. Positive Phase 3 results and priority-review designations in 2025 have compressed timelines and made 2026 a make-or-break year for market-entry planning.
Recent industry events that materially affect commercial strategy include regulatory label expansions, major public-health recommendations for maternal immunization, positive late-stage trial readouts, and prioritized regulatory reviews. On the payer front, significant coverage decisions in the U.S. have already demonstrated rapid willingness to reimburse eligible newborn populations, altering commercial forecasting and uptake assumptions.
Market dynamics to factor into 2026 planning
-
Regulatory volatility and acceleration: Priority reviews and label changes can rapidly expand addressable populations; teams must be ready to scale medical affairs and supply contracts on short notice.
-
Reimbursement precedents: Early high-coverage decisions for specific products create reference cases that will be used in negotiations elsewhere. Manufacturers should plan differentiated evidence packages to replicate success in markets with less mature payer systems.
-
Manufacturing and supply capacity: Industry investments have increased monoclonal antibody capacity, but new capacity is concentrated. Firms that fail to secure capacity in advance risk losing share despite clinical success.
-
IP and generic pressure: The expiration of legacy patents has opened avenues for biosimilars/generics that will change price ceilings and competitive dynamics; lifecycle strategies must incorporate defense and hedging mechanisms.
Strategic recommendations for 2026
-
For incumbents: Solidify contracting models with volume-based discounts and real-world outcomes clauses; accelerate RWE collection to defend premium pricing; prioritize capacity agreements to avoid release bottlenecks at launch.
-
For challengers: Use differentiated platforms (e.g., mRNA) to pursue first-mover or niche-indication strategies; consider regional launches where regulatory and payer pathways are fastest and scale later; pursue strategic alliances for distribution and fill-and-finish arrangements.
-
For investors and corporate development teams: Target opportunities where regulatory catalysts in 2025–2026 can produce outsized top-line inflection; prioritize targets with secure manufacturing pathways and clear reimbursement precedents.
-
For hospitals and healthcare systems: Integrate RSV prevention into maternal and neonatal care pathways and prepare logistics for seasonal campaigns; early alignment with payers and public-health bodies will reduce friction at the point of care.
Risks and scenario planning
Our scenarios highlight several downside and upside drivers that companies must monitor closely in 2026:
-
Downside: Regulatory delays, payer pushback on pricing, manufacturing shortfalls, or an unexpected reduction in vaccine/antibody effectiveness due to viral evolution could materially slow adoption.
-
Upside: Rapid policy endorsements (for example, sweeping maternal immunization recommendations) and additional label expansions can accelerate uptake beyond central-case projections and justify earlier capacity investments.
How PW Consulting supports your 2026 playbook
Our engagement suite is built to move teams from strategy to execution quickly. Services include bespoke market modelling, launch-readiness assessments, payer negotiation simulations, partner/asset diligence, and supply-chain optimization programs. For firms preparing for a 2026 entry or defensibility program, we offer a rapid “90-day readiness” engagement that produces an executable commercialization plan and a quantified risk register.
Next steps — where to obtain the full intelligence
This article is a condensed strategic preview designed to demonstrate the report’s practical value while preserving the granular, modeled intelligence available in the full study. The full report contains detailed country- and channel-level forecasts, downloadable financial models, competitor product timelines, and proprietary scenario tools that underpin the conclusions above. To access the complete dataset and proprietary models that inform 2026 decision-making, please visit the PW Consulting report page or contact our team for a briefing and sample model.
For detailed analysis of this topic, please visit the official page: Worldwide Pediatric Respiratory Syncytial Virus Infection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Lysosomal Acid Lipase Deficiency Treatment Market Forecast to Expand at a 6.25% CAGR (2026–2032)
By pmarketresearch, 2026-07-17
Worldwide Lysosomal Acid Lipase Deficiency (LAL-D) Treatment Market: Strategic Imperatives for 2026
Executive summary
PW Consulting's newest market study on the Worldwide Lysosomal Acid Lipase Deficiency (LAL-D) Treatment Market delivers a focused, decision-ready view for executives planning 2026 strategies. The market is small by absolute value but exhibits steady, durable expansion driven by improved diagnosis, continued orphan-policy support, and constrained but predictable treatment pathways. From a market size of approximately USD 145.2 Million in 2020, PW Consulting estimates growth to roughly USD 196.7 Million by the 2025 base year and projects continued expansion to an estimated USD 300.7 Million by 2032, corresponding to a compound annual growth rate (CAGR) of about 6.25% over the forecast horizon. This trajectory underscores a clear commercial story: predictable growth in a highly specialized ultra-rare disease segment, with strategic implications for portfolio prioritization, manufacturing investment, and market-access planning.
Worldwide Lysosomal Acid Lipase Deficiency Treatment Market
Why 2026 is a pivotal planning year
-
Regulatory and exclusivity timelines converge in ways that affect near-term competition and pricing dynamics. Established orphan approvals confer sustained protection and influence payer negotiation windows.
Worldwide Lysosomal Acid Lipase Deficiency Treatment Market -
Clinical and diagnostic awareness initiatives, coupled with more sensitive newborn and specialty screening programs, are changing the addressable patient population — not by orders of magnitude, but sufficiently to affect commercial forecasts and treatment capacity planning.
Worldwide Lysosomal Acid Lipase Deficiency Treatment Market -
Supply-chain and manufacturing considerations — particularly when biologics are produced on non-standard platforms — are creating long lead times and material cost asymmetries that favor incumbents and raise barriers to rapid market entry.
Market trajectory: what the headline numbers mean for strategy
The market’s growth from the early-2020s base to mid-decade, and onward to 2032, reflects a combination of modest patient-base expansion, incremental pricing dynamics under orphan frameworks, and broader adoption of established enzyme replacement therapy (ERT) protocols. For decision-makers, the important takeaway is not the absolute dollar figure alone but its signaling: predictable, mid-single-digit CAGR in a concentrated specialist market. This profile supports investment cases that emphasize long-term value capture (e.g., manufacturing capacity, patient identification programs, and premium pricing with tailored access programs) rather than high-volume blockbuster models.
Competitive landscape: incumbent advantage and strategic counterplays
The competitive picture in LAL-D treatment remains dominated by a single incumbent product that has secured global regulatory clearances and benefits from orphan-drug policy protections. That standalone position shapes market dynamics across three dimensions:
-
Clinical foothold: the approved enzyme replacement therapy defines the standard-of-care benchmark, which creates a high evidentiary bar for entrants seeking to displace or complement it.
-
Access and reimbursement: orphan status and historical pricing practices have enabled premium pricing; payers, however, are increasingly demanding real-world outcomes and durable cost-effectiveness narratives.
-
Manufacturing moat: the incumbent’s production route uses a proprietary avian-based platform, introducing complex supply-chain and scale-up constraints that reduce the attractiveness of conventional biosimilar strategies.
For new entrants and portfolio managers, these realities imply that straight biosimilar plays are unlikely to be rapid win strategies. Instead, differentiated modalities (e.g., gene therapy, next-generation biologics with improved dosing intervals or administration settings) and programs that demonstrably reduce total cost of care offer more durable pathways to access and value capture.
Regulatory and reimbursement dynamics — the levers that will define market access
Orphan regulatory mechanisms have been pivotal to the development and commercial launch of LAL-D therapies. Early orphan designation and priority-review decisions historically accelerated approval and established protected commercial windows for the first entrant. Across jurisdictions, similar mechanisms continue to influence launch sequencing and investment timelines.
On reimbursement, the combination of ultra-rare prevalence and high per-patient treatment cost means that negotiations are intensely focused on clinical value, budget impact mitigation, and outcomes-based arrangements. Payers typically expect robust evidence packages and may require risk-sharing constructs for high-cost, low-volume therapies. For manufacturers and investors evaluating entry, carefully designed real-world evidence (RWE) strategies and payer engagement playbooks are non-negotiable.
Clinical and diagnostic context
LAL-D is an ultra-rare lysosomal storage disorder, with prevalence estimates placing it well within the rare/ultra-rare disease spectrum. The rarity drives a dual set of challenges: patient identification remains the number-one operational barrier to market expansion, yet screening improvements and practitioner education can have outsized effects on addressable population size. Strategic programs that support earlier diagnosis — including targeted awareness campaigns in specialist centers and integration with genetic and metabolic screening workflows — materially increase therapy uptake without requiring breakthroughs in prevalence.
Manufacturing and supply-chain considerations
Production technology is a determinative factor in the LAL-D market. The incumbent therapy’s production using an avian-derived platform (egg-laying systems) is a recognized cost and complexity driver. This creates a manufacturing moat that influences unit costs, capacity scaling, and timelines for potential challengers using conventional mammalian cell-culture platforms. For commercial planners, that reality means early investment signals for manufacturing capacity and supply redundancy are critical — and can form the basis for negotiation leverage with payers who are sensitive to continuity-of-care risks.
Strategic playbook for 2026: five imperatives
-
Prioritize patient identification and diagnostic partnerships. Screening initiatives deliver the highest short-term ROI on market expansion in ultra-rare spaces.
-
Design payer-centric evidence generation from Day 1. Prospective real-world outcomes and health-economic models should be embedded into launch plans prior to submission in key markets.
-
Assess manufacturing strategy against technology risk. Where incumbent platforms are unique, consider long-lead investments in alternative scalable platforms or secure supply partnerships to hedge risk.
-
Explore differentiated modality investments. Gene therapies and durable biologics that materially change the treatment burden are the most likely to overcome incumbent advantages.
-
Use scenario-based financial planning. Given the concentrated competitive landscape and small patient base, robust scenario modeling that tests diagnosis rates, pricing, and reimbursement outcomes is essential to de-risk commercial decisions.
What PW Consulting’s report contains — actionable intelligence, not an academic exercise
The report blends quantitative forecasting with qualitative, transaction-focused guidance tailored to sponsors, investors, and payers. Key practical deliverables include:
-
Validated market sizing and a 2026–2032 forecast built from a bottom-up patient-flow model aligned to screening, diagnosis, and treatment adoption assumptions.
-
Commercial opportunity maps and go-to-market playbooks for incumbent defense, challenger entry, and late-stage portfolio repositioning.
-
Regulatory and HTA impact assessments that translate orphan-exclusivity timelines and jurisdictional policy differences into clear strategic milestones.
-
Supply-chain and manufacturing risk matrices that identify critical nodes and suggested mitigation pathways, including contract manufacturing considerations and capacity planning triggers.
-
Stakeholder engagement blueprints, including payer negotiation scripts, outcomes-measure selection, and patient-association partnership frameworks.
Importantly, the report provides multiple scenario sets — conservative, base, and upside — allowing teams to stress-test business cases under varied diagnosis and access scenarios.
Competitive intelligence depth
Our competitive analysis features a detailed profile of the market’s leading commercial player, including regulatory history, positioning strategy, and commercial contours. The incumbent benefits from authorized approvals across major jurisdictions and historical orphan-policy advantages that have created durable exclusivity and established the enzyme replacement therapy as the clinical anchor for LAL-D management. PW Consulting’s intelligence interrogates how those strengths translate into negotiating power with payers, how manufacturing choices affect cost structure, and what tactical openings exist for challengers — without publishing commercially sensitive segment-level allocations in this executive summary.
Who should read the report
-
Pharmaceutical and biotech strategy teams evaluating rare-disease portfolios or platform investments.
-
Investors conducting due diligence on companies with exposure to LAL-D therapies, manufacturing platforms, or adjacent genetic-therapy approaches.
-
Commercial leaders responsible for pricing, market access, and launch sequencing in rare-disease franchises.
-
Payers and HTA bodies seeking to understand market dynamics, cost drivers, and evidence-generation options in a concentrated ultra-rare segment.
Final word — a practical invitation
For 2026 planning, the LAL-D treatment market represents a classic rare-disease investment environment: modest absolute revenues but high strategic leverage for the right capabilities (diagnostics, manufacturing, payer engagement, and differentiated clinical value). PW Consulting’s report translates macro growth signals — including the 2020–2025 historical trajectory and the 2026–2032 forecast — into operational next steps and commercial safeguards. This article highlights the strategic contours; the report contains the granular modeling, scenario outputs, and commercial templates you need to convert insight into market action.
To review the full dataset, segmented analysis, and executable commercial playbooks — including the proprietary bottom-up model and interview-backed assumptions that underpin our forecasts — visit the report page on PW Consulting’s website.
For detailed analysis of this topic, please visit the official page: Worldwide Lysosomal Acid Lipase Deficiency Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Wedge Pressure Catheter Market Poised for 5.72% CAGR Through 2032, Says 2025 Report
By pmarketresearch, 2026-07-17
Worldwide Wedge Pressure Catheter Market: Strategic Imperatives for 2026 — Executive Preview
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused executive preview of our latest Worldwide Wedge Pressure Catheter Market report (base year: 2025). This briefing distills the strategic value of the research for corporate leaders planning actions in 2026 — from R&D prioritization and commercial playbooks to regulatory timing and M&A scouting. The analysis is grounded in longitudinal market modeling (historical period 2020–2025) and a rigorous forecast through 2032, denominated in USD Million. To preserve the report’s commercial integrity, core segmentation tables and granular regional/application breakdowns are intentionally omitted here; the full dataset and interactive models are available via the report landing page.
Worldwide Wedge Pressure Catheter Market
Market snapshot you can act on
Our modeling shows a market that has materially recovered and expanded since 2020, demonstrating resilient demand in critical care and interventional settings. The market reached an estimated USD 190.12 Million in 2025 (base year) and, under a central scenario, is forecast to grow to roughly USD 280.62 Million by 2032 — a compound annual growth rate (CAGR) of approximately 5.72% across the 2026–2032 horizon. This trajectory reflects both steady procedural volumes and incremental product upgrades (materials, sensor technology, and single-use disposables) that underpin value-capture opportunities for manufacturers and service providers.
Worldwide Wedge Pressure Catheter Market
Why this matters for 2026 decision-makers
- Timing for product investments: With mid-single-digit CAGR ahead, 2026 is the strategic inflection point to accelerate portfolio refreshes for catheter materials and sensing capabilities before market growth plateaus in later forecast years. Early movers who can demonstrate improved clinical outcomes or reduced procedural complexity will widen adoption curves.
- Regulatory sequencing: Many wedge pressure catheters fall under established regulatory pathways that require premarket notification. Aligning design verification and 510(k) submissions to anticipated regulatory cycles in 2026 shortens time-to-revenue and reduces post-market uncertainty.
- Reimbursement leverage: Procedural billing codes and reimbursement constructs directly influence procurement demand at hospital-system level. Optimizing health-economic dossiers to align device claims with relevant CPT codes in targeted payor markets will materially affect tender outcomes.
- Supply-chain resilience: Critical-component sourcing — from medical-grade polymers to balloon systems — must be rationalized across multi-year contracts. Firms that secure validated suppliers and sterilization capacity (including outsourced ethylene oxide lines) will avoid production bottlenecks and protect margins.
- M&A and partnership rationale: Given a moderately concentrated vendor landscape, opportunistic acquisitions and OEM partnerships can rapidly expand clinical reach or fill technology gaps without waiting for organic development cycles.
What the PW Consulting report delivers (practical, transaction-ready content)
This report was written with implementers in mind. It goes beyond conventional market sizing and includes:
Worldwide Wedge Pressure Catheter Market
- Dynamic financial models (2020–2032) with scenario toggles for conservative, base, and accelerated clinical-adoption assumptions.
- Customer and channel maps that identify high-value hospital systems by procedure intensity and procurement cadence — actionable for sales targeting and distributor alignment.
- Regulatory playbooks detailing the 510(k) pathway, essential documentation, and recommended clinical-validation endpoints to support submissions in major markets.
- Reimbursement impact assessments and payer messaging templates keyed to common procedural codes and hospital billing flows.
- Product roadmaps and materials guidance (including device construction and sterilization best practices) to reduce time-to-market and minimize post-market corrective actions.
- Supplier and contract manufacturing intelligence, including capacity risk scoring and sterilization lead-time estimates.
- Competitive benchmarking, vendor scorecards, and M&A target shortlists, along with integration playbooks and valuation sensitivities.
- Commercial scenarios and tactical 12–24 month launch plans for novel technologies (e.g., fiber optic sensing upgrades, integrated hemodynamic monitoring platforms).
Competitive landscape — who to watch and why
The wedge pressure catheter market demonstrates meaningful concentration, with the top three players commanding a substantial share of industry revenue and the top five commanding an even larger portion. This concentration structure creates strategic realities: scale advantages in manufacturing and distribution, bargaining power with hospital systems, and high barriers for standalone new entrants.
- Edwards Lifesciences (Irvine, CA) — A market incumbent known for pulmonary artery catheter products used in precise pulmonary capillary wedge pressure measurement and comprehensive hemodynamic monitoring. Edwards’ established clinical relationships and product breadth make it a natural leader in bundled monitoring solutions that pair catheter hardware with analytics and disposables. For competitors, Edwards represents both a benchmark for quality and a potential partner for channel access or co-development where strategic fit exists.
- ICU Medical (San Clemente, CA) — Following its strategic acquisition of Smiths Medical, ICU Medical’s portfolio now includes pulmonary artery catheters capable of wedge pressure assessment. This acquisition materially enhanced the company’s addressable market and distribution reach. The integration underscores a broader industry pattern: acquisitions remain a rapid route to capability scale and clinical footprint expansion.
For 2026, expect continued competitive activity focused on vertical integration (monitor-plus-disposable bundles), clinical outcome differentiation, and selective consolidation. Companies with differentiated sensing technology, lower total cost of ownership, or superior supply-chain predictability will secure advantageous contracting positions with large hospital systems.
Regulatory, reimbursement and technical dynamics you must model
- Regulatory classification: Pulmonary artery catheters are commonly managed under established device classifications that mandate premarket notification pathways. Firms should calibrate R&D and clinical programs to meet documentation and bench/bench-to-clinic validation requirements to avoid unexpected regulatory delays.
- Reimbursement environment: Procedural reimbursement remains a critical demand driver. Codes that cover right heart/pulmonary artery catheterization materially influence procedural economics at the hospital level and consequently affect purchase decisions for disposable catheters and monitoring systems.
- Sterilization and materials: Industry-standard sterilization processes (including ethylene oxide methods validated to robust sterility assurance levels) and construction using medical-grade polyurethane shafts with silicone balloons are foundational to product acceptance and supplier qualification. Investing in validated sterilization partnerships or in-house capacity should be a priority for any manufacturer scaling commercial distribution.
- EU market considerations: Continued compliance with European medical device requirements is non-negotiable; firms must maintain regulatory vigilance to avoid market access disruptions.
Scenario planning: four strategic options for 2026
- Scale and defend: For market leaders — reinforce supply-chain control, prioritize bundled solutions, and invest in outcome evidence to harden hospital contracts.
- Innovate and niche-up: For mid-size players — invest selectively in sensing technologies (e.g., fiber optic enhancements) and target clinical niches where differentiation can command premium pricing.
- Partner to accelerate: For firms lacking commercial reach — pursue OEM distribution or bolt-on acquisitions to rapidly access high-volume hospital systems and expand geographic coverage.
- Operationally optimize: For suppliers — secure sterilization capacity, rationalize component sourcing, and de-risk manufacturing through dual-sourcing strategies to ensure stable delivery into 2026 tenders.
How to use this preview: immediate next steps
- Run a 90-day gap analysis against your product validation and regulatory timelines to ensure any device updates meet 510(k)/MDR requirements well ahead of 2026 procurement cycles.
- Map your top 20 target hospital systems by procedural intensity and align commercial resources for direct negotiations or distributor tender participation.
- Audit sterilization and supplier agreements for lead-time exposure and contingency capacity; prioritize contracts that provide production continuity.
- For business development teams — prioritize outreach to potential partners or acquisition targets that fill clinical or geographic coverage gaps identified in your go-to-market plan.
Accessing full intelligence
This article intentionally previews high-value strategic takeaways while withholding the detailed segmentation tables, granular regional and application revenue splits, and interactive financial models that underpin our recommendations. Those elements are available in the full Worldwide Wedge Pressure Catheter Market report (base year 2025, historical 2020–2025, forecast 2026–2032; currency: USD Million), which includes downloadable datasets, supplier scorecards, and acquisition target dossiers to support investment and commercial decisions in 2026.
To obtain the complete report, interactive models, and an executive briefing with our team, please visit the PW Consulting report page or contact our enterprise research desk. For organizations planning material investments, we also offer a tailored strategy workshop to convert the report’s insights into a 12–24 month operational plan.
PW Consulting remains committed to translating market intelligence into executable strategies. The wedge pressure catheter market is mature yet dynamic — 2026 offers a narrow window to consolidate commercial advantages and secure long-term growth. Our analysis lights the path; the full report supplies the tactical maps.
For detailed analysis of this topic, please visit the official page: Worldwide Wedge Pressure Catheter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Radial Artery Compression Device Market to Grow from USD 330.1 Million in 2025 to USD 562.08 Million by 2032 at a 7.9% CAGR
By pmarketresearch, 2026-07-17
Worldwide Radial Artery Compression Device Market: Strategic Insights for 2026 Decision‑Making
PW Consulting’s new market brief—supported by a full market research dossier covering 2020–2025 (base year 2025) and a forecast out to 2032—provides executive teams with the focused, decision‑grade intelligence required to shape growth, M&A and commercialization strategies in 2026. The worldwide radial artery compression device market is on a sustained growth trajectory: our model shows expansion from an estimated USD 228.45 million in 2020 to USD 330.10 million in 2025, with a forecast compound annual growth rate (CAGR) of 7.9% through 2032, when the market is expected to approach USD 562.08 million. These headline figures frame an attractive market environment—but the strategic value of our work is in the granular, operable insight beneath those totals.
Worldwide Radial Artery Compression Device Market
Why This Report Matters for 2026 Strategy
-
Time-sensitive go-to-market decisions. 2026 is the inflection year for many radial access pathways and device-adjacent innovations. Organizations that align product launches, regulatory filings and commercial investments to the demand curves we model will capture disproportionate share during the next two funding and procurement cycles.
Worldwide Radial Artery Compression Device Market -
Regulatory and reimbursement clarity. The devices are regulated primarily through 510(k) pathways in the U.S. and commonly carry CE marks for Europe; procurement economics are influenced by procedural bundling under Medicare and similar payors. Understanding where regulatory friction and billing constraints create pockets of competitive advantage is essential for prioritizing resources.
Worldwide Radial Artery Compression Device Market -
Concentration and competitive dynamics. The market exhibits meaningful concentration: the top three vendors account for a majority share and the top five consolidate an even larger portion of market value. That structure creates both barriers and opportunities—incumbents can leverage scale and installed OEM relationships, while specialized entrants can displace legacy players by winning distinct clinical or cost advantages.
What’s Inside the PW Consulting Dossier (Operational Summary)
-
Full market sizing and multi-scenario forecasts (2026–2032) with sensitivity analyses calibrated against adoption curves for transradial and distal radial access.
-
Clinical pathway mapping that translates procedure mix and hospital/ASC workflows into device demand, dwell time and consumable-replacement economics.
-
Regulatory and reimbursement playbook that flags filing strategies, incremental data requirements, and the commercial implications of procedural bundling in major payor geographies.
-
Supply‑chain risk heatmap focused on medical‑grade polymers, skin‑contact materials and transparency housings; alternative sourcing pathways and cost levers for 2026 procurement decisions.
-
Competitive benchmarking: qualitative and quantitative vendor scorecards covering product features (e.g., dual‑balloon patent hemostasis, transparent housings, size range), clinical evidence, geographic reach, and pricing posture—designed for rapid vendor selection or M&A diligence.
-
Commercial playbooks: targeted segmentation strategies, channel design for hospitals vs ambulatory surgical centers vs specialty clinics, and pricing tactics supported by elasticity testing and contract negotiation frameworks.
-
Investment thesis and deal pipeline: prioritized M&A targets, plausible consolidation scenarios, and valuation sensitivities for financial sponsors and strategic acquirers.
Market Dynamics: Drivers, Constraints and Supply Considerations
Demand drivers remain clinical and operational: broader adoption of radial access for catheterization, the rise of distal radial approaches, and heightened clinician preference for devices that support patent hemostasis while minimizing nerve compression. Procedure volume recovery post‑pandemic and the shift toward outpatient settings (ASCs) continue to reweight where devices are procured and used.
Regulatory dynamics are stable but nontrivial. Many radial compression devices are cleared through FDA 510(k) pathways (class I/II designations), and the ability to leverage existing clearances or CE marking materially shortens time to market in key geographies. On the reimbursement side, procedural bundling under Medicare and other third‑party payors limits additive device margin capture by providers, placing a premium on institutional value propositions—reduced staff time, lower complication rates, faster turnover—rather than standalone billing.
On the supply side, manufacturers depend on medical‑grade polymers, latex‑free patient contact materials, and transparent housings to meet clinician requirements for visibility and skin safety. These inputs are subject to sourcing concentration and cost variability; our supply‑chain scenarios quantify unit‑cost sensitivity to key polymer price shocks and lead‑time disruptions.
Competitive Landscape: Who’s Playing and Where They Compete
The competitive field blends global incumbents and nimble specialists. A non‑exhaustive set of market participants included in our analysis are:
-
Terumo Corporation (Tokyo): Known for the TR Band product family—dual‑balloon technology that emphasizes precise hemostasis, patent hemostasis protocols, and design features to reduce nerve compression risk.
-
Merit Medical Systems, Inc. (South Jordan, Utah): Broad radial portfolio including PreludeSYNC and related devices; recent 2025 releases (e.g., Prelude Wave Hydrophilic Sheath Introducer with SnapFix Securement) expand Merit’s sheath-to‑hemostasis offering and provide cross‑sell opportunities.
-
Teleflex Incorporated (Wayne, Pennsylvania): Combines positioning splints and topical hemostatic adjuncts to offer a systems approach to radial access care.
-
Abbott Laboratories (Abbott Park, Illinois): Offers integrated hemostasis solutions and capital equipment relationships that can accelerate adoption among institutional customers.
-
Advanced Vascular Dynamics / Semler Technologies (Portland): A portfolio of radial and femoral hemostasis devices often cleared for major markets, positioning the company as a clinical practice innovator.
-
Regional and specialty players (e.g., TZ Medical, Lepu Medical, Beijing Demax, Forge Medical, Galt Medical, Ates/Benrikal, St. Stone, Rising Medical): These firms are important sources of product innovation, price competition and differentiated form‑factors, especially in local markets and niche channels.
Our competitive analysis identifies where feature differentiation (e.g., ease of achieving patent hemostasis, device ergonomics, disposability and packaging), channel strength (hospital group agreements, ASC distributors), and regulatory footprints (510(k), CE marking) most directly translate into commercial advantage.
Strategic Implications and Recommendations for 2026
-
Incumbent manufacturers should prioritize bundled, clinically validated solutions that reduce total procedure cost and staff time. Investment in complementary products (sheaths, securement, topical hemostats) and clinical evidence generation will erect higher switching costs.
-
New entrants and challengers need to pick high-leverage niches: differentiated features for distal radial approaches, compelling cost‑per‑procedure economics for ASCs, or superior ergonomics that reduce nursing time. Focused pilots with high‑volume network partners accelerate diffusion.
-
Private equity and M&A buyers should use the market concentration metrics and our vendor scorecards to identify bolt‑on targets that deliver feature complementarity or geographic expansion—especially where incumbents’ margins can be improved via supply chain rationalization.
-
Hospital and ASC procurement teams should use scenario models to evaluate total cost of ownership across device families, and to structure contracts that reward clinical outcomes and throughput improvements rather than unit price alone.
60‑ and 180‑Day Tactical Playbook for Executives
-
Days 0–60: Run a rapid internal audit—procurement footprints, usage per procedure, price per device, and supply‑chain single points of failure. Validate assumptions against our short report snapshot and request targeted vendor scorecards.
-
Days 60–180: Initiate two parallel projects—a clinical outcomes pilot with a high‑volume center and a sourcing optimization program targeting polymer and housing suppliers. Use pilot results to renegotiate contracts and justify new product introductions in 2027 planning cycles.
What We Intentionally Withhold Here (And Where to Get It)
Consistent with the “trailer” principle of this release, we present the high‑confidence, strategic conclusions and headline market metrics above while withholding the granular segment tables, region‑by‑region sizing, end‑user splits, and vendor share matrices that are essential to transactional diligence. The full PW Consulting report contains those datasets—together with downloadable scenario models, vendor scorecards, and negotiation playbooks—designed to be used directly in boardrooms and M&A committees.
Access to the complete dataset and proprietary models is available through the PW Consulting report portal. For strategy teams preparing 2026 budgets and for investors sizing opportunities, the full report is the practical next step to convert the market’s growth potential into a defensible plan.
Contact PW Consulting to request a guided briefing, obtain customized slices of the model for your geography or channel of interest, or to commission a bespoke vendor due diligence package targeted to an imminent transaction.
For detailed analysis of this topic, please visit the official page: Worldwide Radial Artery Compression Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Mineral Sand Deposits Market at USD 9,345.2 Million in 2025 — Forecast to Reach USD 13,044.8 Million by 2032 at a 4.88% CAGR
By pmarketresearch, 2026-07-17
Worldwide Mineral Sand Deposits Market — Strategic Outlook for 2026 Decision-Making
As demand patterns, geopolitics and technology converge to reshape critical raw material supply chains, our new PW Consulting report on the Worldwide Mineral Sand Deposits Market provides a practical, forward-looking playbook for executives planning in 2026. Drawing on a detailed historical series (2020–2025) and a seven‑year forecast (2026–2032), the study combines market sizing, scenario modelling, project-level intelligence and commercial strategy tools designed to convert geological opportunity into resilient, investable business plans.
Worldwide Mineral Sand Deposits Market
Executive snapshot
The mineral sands market is entering a consolidation and re‑scoping phase. After recovering from mid‑cycle headwinds, total industry revenues reached approximately USD 9,345.2 Million in the base year 2025. Under conservative-to‑base scenarios, PW Consulting’s forecast shows a steady expansion through 2032, with the market approaching roughly USD 13,044.8 Million by 2032 — a compound annual growth rate (CAGR) of 4.88% across the 2026–2032 forecast window. Historical patterns between 2020 and 2025 exhibit both supply interruptions and periods of demand compression tied to pigment and industrial end‑market cycles; the next strategic inflection point is scheduled around the late 2020s as several capacity projects transition from permitting to production.
Worldwide Mineral Sand Deposits Market
Why this matters for 2026 decisions
- Capital allocation: The market’s mid‑single‑digit CAGR and predictable phase‑shifts in project commissioning mean that timing of greenfield investment and brownfield expansions will materially affect returns. Early movers that align capex with the 2028–2030 supply uptick stand to capture premium offtake arrangements.
- Procurement & contracts: Volatility in feedstock pricing and periodic regional shortages will reward counterparties that implement flexible offtake and indexation clauses. The report provides playbooks for structuring multi‑year contracts to balance price exposure and secure feedstock continuity.
- Risk & resilience: Geopolitical interventions and regulatory reclassification of minerals demand proactive mitigation — from diversified sourcing to inventory strategies and alloyed supply partnerships. The report maps five actionable risk mitigation archetypes for buyers and producers.
Market dynamics — drivers, risks and near‑term signals
Three structural forces will define enterprise choices in 2026:
Worldwide Mineral Sand Deposits Market
- End‑market demand rhythms. Titanium pigment demand remains the primary long‑run demand engine, with ceramics, refractories and foundry applications providing countercyclical support. Short‑term pigment softness in certain quarters compressed prices and inventories in 2023–2025, but secular drivers (lighter, stronger materials, expanding aerospace and additive manufacturing applications) point to resilient medium‑term growth.
- Policy and geopolitics. Heavy mineral sands that yield titanium and zirconium have increasingly migrated into government strategic thinking. Notably, elements of the supply chain were added to the U.S. critical minerals list in 2025 — a development that elevates permitting priority, defence sourcing preferences and subsidy potential for qualifying projects. At the same time, trade restrictions by major processors in 2025 have catalysed re‑shoring and supplier diversification efforts among downstream manufacturers.
- Price signal complexity. Spot and contract references for ilmenite and associated concentrates showed regional spread in late‑2025, reflecting differing demand elasticities and logistical costs. These price gradients are a direct signal for investment in beneficiation and integrated processing where margin capture is feasible.
Supply‑side outlook and project intelligence
Our project database and capex overlays show a mix of restarts, capacity extensions and greenfield developments reaching decision points between 2026 and 2029. Three developments illustrate the strategic terrain:
- Large‑scale restarts and life‑extension investments by incumbent miners are being prioritised where asset quality and existing infrastructure reduce execution risk. One major approval in early 2026 for a long‑life sands project demonstrates how incumbents can unlock multi‑decade value through targeted investment.
- Feasibility advancements in 2026 for rare earth and heavy mineral sands projects signal a renewed investor appetite for vertically integrated resource projects that combine ilmenite, zircon and REE streams — particularly where rare earth recoveries materially improve project returns.
- Regional permitting wins for modest‑scale projects in late 2025 highlight the tactical advantage for developers that have early, credible social licence and robust environmental plans. The ability to secure annual throughputs and keep supply chains short will be an operational differentiator.
Competitive landscape — who matters and why
The mineral sands industry shows measured concentration, with the three largest producers accounting for a significant minority of global capacity and the top five controlling a clear majority of the market’s commercial access. PW Consulting’s competitive assessment focuses on capability differentials, strategic positioning and execution risk rather than raw reserve counts.
- Iluka Resources — A global production and processing operator with a proven ability to manage price cyclicality through integration and geographic diversification. Operational excellence and incremental rare earth processing investments are strengthening Iluka’s strategic optionality.
- Rio Tinto — As a major diversified miner with heavy mineral sands assets, Rio Tinto leverages scale, downstream integration and large‑project execution capability. Large restart and expansion approvals in 2026 underscore the company’s role as a market stabiliser when it elects to deploy capital.
- Tronox & Kenmare — These players exemplify integrated value chain models and focused regional strategies. Their balance sheets and offtake relationships make them natural partners for downstream pigment producers seeking supply security.
- Base Resources, Chemours, TiZir and national champions — Each holds niche advantages: lower unit costs from favourable geology, embedded regional logistics, or state‑backed market access. Emerging consolidators and project developers are worth watching for M&A as majors rationalise portfolios.
- New entrants and near‑term developers — Companies advancing feasibility and permitting in 2025–2026 may not immediately shift market shares, but they change bargaining power in tight supply windows and can be acquisition targets for vertically integrated players.
Importantly, market concentration metrics (CR3 ≈ 42.15%, CR5 ≈ 58.3%) indicate a market that is neither atomised nor fully consolidated — a structural profile that supports selective capacity additions and targeted M&A rather than wholesale disruption.
What’s inside the PW Consulting report — practical, executable modules
This study is intentionally operational. The report is designed for commercial teams, corporate strategy groups, project investors and government stakeholders who need to convert market insight into decisions in 2026. Core deliverables include:
- Validated market size and forecast model (2020–2032) with scenario toggles for demand shocks, price trajectories and capex timing.
- Project‑level pipeline database (development stage, nameplate potential, likely commissioning windows) and a red/amber/green execution risk scoring framework.
- Price sensitivity and margin modelling for ilmenite, rutile and zircon under alternative contract structures and beneficiation pathways.
- Regulatory and geopolitical risk matrices tied to permitting timelines, critical minerals policy and export controls.
- Company intelligence dossiers with comparative KPIs, production footprints and M&A probability assessments for the sector’s key actors.
- Practical commercial playbooks: offtake negotiation templates, JV structuring options, hedging and inventory strategies, and reclamation/ESG benchmarking with permitting pathway guides.
How management teams should act in 2026 — recommended moves
- Prioritise optionality. Value projects that provide flexible product streams (e.g., combined ilmenite/zircon/REE recovery) and preserve downside protection through phased capex commitments.
- Lock in strategic offtakes with downstream partners on sliding price indices while retaining spot exposure for upside capture during tight cycles.
- Invest in processing capability where price spreads justify beneficiation — near‑term gains can offset initial capital when logistics and energy inputs are optimised.
- Use M&A defensively. Search for bolt‑on assets that close logistical gaps or add guaranteed throughput to existing plants rather than large, standalone greenfield commitments.
- Engage regulators early and transparently. Permitting wins in 2025–2026 demonstrate that social licence and robust environmental planning materially reduce time‑to‑market risk.
Data transparency and how to get the full intelligence
To preserve the commercial integrity of project‑level and segmental economics, this article intentionally omits detailed subsegment figures and region/application breakdowns. PW Consulting’s full report contains granular splits by region, product type and application, downloadable datasets, interactive forecasting tools and the complete project pipeline — all presented with our proprietary assumptions and sensitivity engines. If your 2026 strategy hinges on precise volumes, country exposure, or offtake timing, access to the full dataset and model is indispensable.
For decision‑grade intelligence, the full Worldwide Mineral Sand Deposits Market report from PW Consulting includes the raw data tables, scenario toggles and implementation templates needed to translate insight into action. Visit our website to review the summary contents and arrange a briefing with one of our senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Mineral Sand Deposits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com