

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Mineral Sand Deposits Market at USD 9,345.2 Million in 2025 — Forecast to Reach USD 13,044.8 Million by 2032 at a 4.88% CAGR

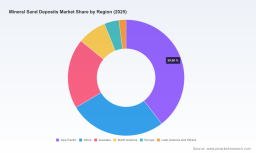
Worldwide Mineral Sand Deposits Market — Strategic Outlook for 2026 Decision-Making
As demand patterns, geopolitics and technology converge to reshape critical raw material supply chains, our new PW Consulting report on the Worldwide Mineral Sand Deposits Market provides a practical, forward-looking playbook for executives planning in 2026. Drawing on a detailed historical series (2020–2025) and a seven‑year forecast (2026–2032), the study combines market sizing, scenario modelling, project-level intelligence and commercial strategy tools designed to convert geological opportunity into resilient, investable business plans.
Worldwide Mineral Sand Deposits Market
Executive snapshot
The mineral sands market is entering a consolidation and re‑scoping phase. After recovering from mid‑cycle headwinds, total industry revenues reached approximately USD 9,345.2 Million in the base year 2025. Under conservative-to‑base scenarios, PW Consulting’s forecast shows a steady expansion through 2032, with the market approaching roughly USD 13,044.8 Million by 2032 — a compound annual growth rate (CAGR) of 4.88% across the 2026–2032 forecast window. Historical patterns between 2020 and 2025 exhibit both supply interruptions and periods of demand compression tied to pigment and industrial end‑market cycles; the next strategic inflection point is scheduled around the late 2020s as several capacity projects transition from permitting to production.
Worldwide Mineral Sand Deposits Market
Why this matters for 2026 decisions
- Capital allocation: The market’s mid‑single‑digit CAGR and predictable phase‑shifts in project commissioning mean that timing of greenfield investment and brownfield expansions will materially affect returns. Early movers that align capex with the 2028–2030 supply uptick stand to capture premium offtake arrangements.
- Procurement & contracts: Volatility in feedstock pricing and periodic regional shortages will reward counterparties that implement flexible offtake and indexation clauses. The report provides playbooks for structuring multi‑year contracts to balance price exposure and secure feedstock continuity.
- Risk & resilience: Geopolitical interventions and regulatory reclassification of minerals demand proactive mitigation — from diversified sourcing to inventory strategies and alloyed supply partnerships. The report maps five actionable risk mitigation archetypes for buyers and producers.
Market dynamics — drivers, risks and near‑term signals
Three structural forces will define enterprise choices in 2026:
Worldwide Mineral Sand Deposits Market
- End‑market demand rhythms. Titanium pigment demand remains the primary long‑run demand engine, with ceramics, refractories and foundry applications providing countercyclical support. Short‑term pigment softness in certain quarters compressed prices and inventories in 2023–2025, but secular drivers (lighter, stronger materials, expanding aerospace and additive manufacturing applications) point to resilient medium‑term growth.
- Policy and geopolitics. Heavy mineral sands that yield titanium and zirconium have increasingly migrated into government strategic thinking. Notably, elements of the supply chain were added to the U.S. critical minerals list in 2025 — a development that elevates permitting priority, defence sourcing preferences and subsidy potential for qualifying projects. At the same time, trade restrictions by major processors in 2025 have catalysed re‑shoring and supplier diversification efforts among downstream manufacturers.
- Price signal complexity. Spot and contract references for ilmenite and associated concentrates showed regional spread in late‑2025, reflecting differing demand elasticities and logistical costs. These price gradients are a direct signal for investment in beneficiation and integrated processing where margin capture is feasible.
Supply‑side outlook and project intelligence
Our project database and capex overlays show a mix of restarts, capacity extensions and greenfield developments reaching decision points between 2026 and 2029. Three developments illustrate the strategic terrain:
- Large‑scale restarts and life‑extension investments by incumbent miners are being prioritised where asset quality and existing infrastructure reduce execution risk. One major approval in early 2026 for a long‑life sands project demonstrates how incumbents can unlock multi‑decade value through targeted investment.
- Feasibility advancements in 2026 for rare earth and heavy mineral sands projects signal a renewed investor appetite for vertically integrated resource projects that combine ilmenite, zircon and REE streams — particularly where rare earth recoveries materially improve project returns.
- Regional permitting wins for modest‑scale projects in late 2025 highlight the tactical advantage for developers that have early, credible social licence and robust environmental plans. The ability to secure annual throughputs and keep supply chains short will be an operational differentiator.
Competitive landscape — who matters and why
The mineral sands industry shows measured concentration, with the three largest producers accounting for a significant minority of global capacity and the top five controlling a clear majority of the market’s commercial access. PW Consulting’s competitive assessment focuses on capability differentials, strategic positioning and execution risk rather than raw reserve counts.
- Iluka Resources — A global production and processing operator with a proven ability to manage price cyclicality through integration and geographic diversification. Operational excellence and incremental rare earth processing investments are strengthening Iluka’s strategic optionality.
- Rio Tinto — As a major diversified miner with heavy mineral sands assets, Rio Tinto leverages scale, downstream integration and large‑project execution capability. Large restart and expansion approvals in 2026 underscore the company’s role as a market stabiliser when it elects to deploy capital.
- Tronox & Kenmare — These players exemplify integrated value chain models and focused regional strategies. Their balance sheets and offtake relationships make them natural partners for downstream pigment producers seeking supply security.
- Base Resources, Chemours, TiZir and national champions — Each holds niche advantages: lower unit costs from favourable geology, embedded regional logistics, or state‑backed market access. Emerging consolidators and project developers are worth watching for M&A as majors rationalise portfolios.
- New entrants and near‑term developers — Companies advancing feasibility and permitting in 2025–2026 may not immediately shift market shares, but they change bargaining power in tight supply windows and can be acquisition targets for vertically integrated players.
Importantly, market concentration metrics (CR3 ≈ 42.15%, CR5 ≈ 58.3%) indicate a market that is neither atomised nor fully consolidated — a structural profile that supports selective capacity additions and targeted M&A rather than wholesale disruption.
What’s inside the PW Consulting report — practical, executable modules
This study is intentionally operational. The report is designed for commercial teams, corporate strategy groups, project investors and government stakeholders who need to convert market insight into decisions in 2026. Core deliverables include:
- Validated market size and forecast model (2020–2032) with scenario toggles for demand shocks, price trajectories and capex timing.
- Project‑level pipeline database (development stage, nameplate potential, likely commissioning windows) and a red/amber/green execution risk scoring framework.
- Price sensitivity and margin modelling for ilmenite, rutile and zircon under alternative contract structures and beneficiation pathways.
- Regulatory and geopolitical risk matrices tied to permitting timelines, critical minerals policy and export controls.
- Company intelligence dossiers with comparative KPIs, production footprints and M&A probability assessments for the sector’s key actors.
- Practical commercial playbooks: offtake negotiation templates, JV structuring options, hedging and inventory strategies, and reclamation/ESG benchmarking with permitting pathway guides.
How management teams should act in 2026 — recommended moves
- Prioritise optionality. Value projects that provide flexible product streams (e.g., combined ilmenite/zircon/REE recovery) and preserve downside protection through phased capex commitments.
- Lock in strategic offtakes with downstream partners on sliding price indices while retaining spot exposure for upside capture during tight cycles.
- Invest in processing capability where price spreads justify beneficiation — near‑term gains can offset initial capital when logistics and energy inputs are optimised.
- Use M&A defensively. Search for bolt‑on assets that close logistical gaps or add guaranteed throughput to existing plants rather than large, standalone greenfield commitments.
- Engage regulators early and transparently. Permitting wins in 2025–2026 demonstrate that social licence and robust environmental planning materially reduce time‑to‑market risk.
Data transparency and how to get the full intelligence
To preserve the commercial integrity of project‑level and segmental economics, this article intentionally omits detailed subsegment figures and region/application breakdowns. PW Consulting’s full report contains granular splits by region, product type and application, downloadable datasets, interactive forecasting tools and the complete project pipeline — all presented with our proprietary assumptions and sensitivity engines. If your 2026 strategy hinges on precise volumes, country exposure, or offtake timing, access to the full dataset and model is indispensable.
For decision‑grade intelligence, the full Worldwide Mineral Sand Deposits Market report from PW Consulting includes the raw data tables, scenario toggles and implementation templates needed to translate insight into action. Visit our website to review the summary contents and arrange a briefing with one of our senior analysts.
For detailed analysis of this topic, please visit the official page: Worldwide Mineral Sand Deposits Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com