

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Anorectal Manometry Devices Market to Grow from USD 248.5 Million in 2025 to USD 372.43 Million by 2032 at a 5.95% CAGR

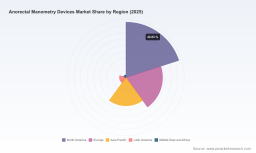
Worldwide Anorectal Manometry Devices Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s newest market study on Worldwide Anorectal Manometry Devices synthesizes a multi-year evidence base and primary intelligence to deliver actionable guidance for commercial leaders, clinical program directors, investors, and health-system procurement teams planning for 2026 and beyond. The market is small but dynamic: after a baseline of USD 248.5 Million in 2025, our base-case projection anticipates continued expansion to roughly USD 372.4 Million by 2032, implying a compounded annual growth rate of approximately 5.95% over the forecast window. Those headline trajectories reflect a confluence of technology migration (toward high-resolution and disposable solutions), reimbursement and coding shifts, and an evolving competitive landscape where a handful of specialist suppliers exert meaningful influence.
Worldwide Anorectal Manometry Devices Market
Market at a Glance: What the Numbers Mean for Strategy
-
Growth trajectory: The market’s mid-single-digit CAGR signals steady demand driven by increasing clinical recognition of anorectal physiology testing, broader adoption of high-resolution platforms, and incremental penetration of office-based portable systems. The near-term step-up in market size ending 2025 forms the base from which 2026 strategies should be calibrated.
Worldwide Anorectal Manometry Devices Market -
Concentration: Market concentration metrics indicate that a limited set of companies capture a meaningful share of industry revenue — enough to shape standards, channel behavior, and pricing dynamics, yet leaving room for targeted innovators to displace legacy incumbents in defined niches.
Worldwide Anorectal Manometry Devices Market -
Adoption inflection points: The combined impact of device-level innovation (disposable catheters, compact HRAM platforms, and portable manometry) and clarified regulatory pathways is shifting where and how testing is delivered — from tertiary centers toward ambulatory and office-based workflows — creating new go-to-market and clinical integration imperatives.
What the PW Consulting Report Contains — Practical, Implementable Intelligence
-
Market sizing and forecasts (2020–2032) with scenario modeling. We provide base, conservative, and accelerated cases to stress-test investment and commercial plans against reimbursement and adoption variability.
-
Channel and customer strategy playbooks for hospitals, diagnostic centers, specialty clinics, and distributor partners — including service, training, and consumables models that materially affect lifetime revenue.
-
Regulatory and reimbursement tracker: a timeline of 510(k) clearances and evolving CPT code policy, plus an impact assessment that links coding change to revenue cycle and capital procurement behavior.
-
Competitive landscaping and capability maps. We profile device architectures (high-resolution vs conventional vs portable), productized software/analytics, disposables strategy, and clinical evidence footprints for the leading suppliers.
-
Technology and clinical adoption playbooks: criteria for prioritizing R&D bets (e.g., disposable HRAM catheters, integrated balloon expulsion protocols, combined EMG sensing), and a recommended evidence-generation roadmap to accelerate payer acceptance and guideline inclusion.
-
M&A and partnership advisory: target screens and integration checklists for acquirers seeking either scale in consumables and service or capability enhancement in analytics and point-of-care instrumentation.
Key Competitive Themes and Strategic Implications
The market is characterized by a mix of legacy device makers and agile entrants focused on portability and disposables. Notable participants include manufacturers with established high-resolution platforms, vendors specializing in portable manometry optimized for office workflows, and regional producers that compete on cost and channel relationships. Recent product and regulatory developments underscore the pace of change:
-
Disposable HRAM systems and compact high-resolution platforms have moved from concept to commercialization — exemplified by recent product launches that make single-use catheters available in clinical practice. This materially changes procurement economics (less reprocessing capital, different consumable models) and infectious disease mitigation policies in institutional settings.
-
Portable devices that reduce procedure time and support office-based testing have received regulatory clearances, opening new uptake corridors among smaller practices and enhancing access for patients with mobility or access barriers.
For established vendors, the strategic choice is how aggressively to transition to consumables-driven revenue models and software-enabled services. For challengers, the playbook is carve-out clinical niches (e.g., pediatric programs, rapid bedside screening, or bundled pelvic floor therapy) and partner with clinical champions to accelerate guideline adoption.
Regulatory and Reimbursement Shifts — A 2026-Ready Checklist
-
Regulatory clarity: Anorectal manometry devices continue to be regulated as Class II gastrointestinal motility monitoring systems under existing product codes, with 510(k) marketing pathways being the primary route to U.S. entry. Recent clearances for portable systems reinforce that the pathway is viable for novel form factors.
-
Coding and reimbursement: A significant coding update effective January 1, 2026 replaces legacy procedure codes with new Category I codes that redefine how anorectal manometry procedures are described and reimbursed. This change requires immediate action from billing, contracting, and clinical documentation teams to avoid revenue leakage and to capture procedure complexity appropriately.
-
Standards and clinical protocols: High-resolution systems are increasingly aligning with community-driven protocols and classifications — alignment that accelerates adoption but also raises the bar for vendors on interoperability and analytics accuracy.
Actionable Strategic Imperatives for 2026
-
For product leaders: prioritize modular architectures that support both high-resolution core systems and disposable catheter lines. The capacity to offer bundled service plans and predictable consumable economics will be a differentiator in buyer procurement cycles.
-
For commercial teams: redesign go-to-market motions to address office-based clinicians and ambulatory surgery centers. Shorter procedure times, simplified workflows, and training bundles lower friction for adoption — metrics buyers can measure immediately.
-
For clinical affairs and R&D: invest in comparative clinical evidence that maps device features to guideline-relevant endpoints (e.g., defecatory disorder diagnostics, balloon expulsion concordance, pelvic floor biofeedback outcomes). Payer coverage decisions are increasingly evidence-driven.
-
For health systems and procurement: run scenario-based TCO analyses that incorporate consumable utilization, reprocessing costs, and staff time. The apparent unit price of a device can be misleading without modeling the service and consumables run-rate over a 3–5 year horizon.
-
For investors and M&A teams: target capabilities that accelerate recurring revenue — disposables manufacturing, cloud-enabled analytics, or clinic network access — rather than one-time capital sales alone. Integration risk is highest for acquisitions that lack a clear consumables or service upsell path.
Competitive Snapshot — Who’s Shaping the Market
Core incumbents and nimble challengers are blending device innovation with clinical workflow solutions. Examples of technology and strategic positioning observed in our analysis include:
-
Manufacturers of high-resolution platforms that emphasize diagnostic precision, integration with IAWG protocols, and classification frameworks — positioning that supports referral-center adoption and specialist workflows.
-
Global medical device majors offering high-density probes and 3-D mapping features for advanced physiological assessment, generally aligned with tertiary diagnostic centers and research programs.
-
Portable system vendors targeting office-based and ambulatory care with compact hardware and simplified test protocols — accelerating access and procedural throughput.
-
Regional suppliers and specialty firms that compete on tailored service models, local clinical relationships, and price-performance options.
Profiles and capability matrices for named competitors — from established HRAM platform vendors to portable-system innovators and specialized catheter manufacturers — are included in the full report, together with a detailed assessment of each player’s R&D pipeline, regulatory filings, and channel reach.
How PW Consulting’s Report Helps You Move from Insight to Decision
-
Immediate deliverables: executive decision memos, prioritized capability roadmaps, and a procurement checklist tailored to device life-cycle and consumables economics — all structured to be actionable within a 90‑day planning cycle.
-
Scenario toolkits: models that let you stress-test pricing, reimbursement, and adoption assumptions to quantify upside and downside across 2026–2032 horizons.
-
Implementation briefings: operational playbooks for clinical training, coding transitions, and supplier contract renegotiations tied to the January 2026 coding update and related payer policies.
Closing — Why This Report Is a 2026 Essential
Decisions taken in 2026 — about product roadmaps, evidence programs, channel investments, and capital procurement — will determine who captures the next wave of growth in anorectal manometry. PW Consulting’s study synthesizes the quantitative market trajectory, regulatory inflection points, and competitive moves to create a pragmatic blueprint for leaders who need to convert insight into market advantage without getting lost in raw data. We intentionally preserve granular segment tables for the full report to ensure commercial confidentiality and to provide subscribers with the precise, auditable figures they need for contracting and valuation.
To access the detailed segment breakdowns, company profiles, methodology appendix, and scenario models that underpin this strategic preview, please visit the PW Consulting report page or contact our advisory team for a briefing and tailored executive summary.
For detailed analysis of this topic, please visit the official page: Worldwide Anorectal Manometry Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com