

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Pediatric Respiratory Syncytial Virus Infection Market Surges to USD 4,500 Million by 2025

Worldwide Pediatric Respiratory Syncytial Virus (RSV) Infection Market — 2026 Strategic Preview
Executive summary
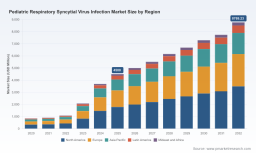
PW Consulting’s latest market research, “Worldwide Pediatric RSV Infection Market,” delivers a data-driven strategic foundation for corporate decision-making in 2026. Using 2025 as the base year, the study traces an accelerated adoption curve over 2020–2025 and provides a robust forecast across 2026–2032. The pediatric RSV prophylaxis and treatment market expanded from under USD 1 billion in 2020 to roughly USD 4.5 billion by 2025 and is projected to continue growing at a compound annual growth rate (CAGR) of approximately 10.01% through the 2026–2032 forecast window. By 2032 the market is forecast to exceed USD 8.7 billion under our central-case assumptions.
Worldwide Pediatric Respiratory Syncytial Virus Infection Market
These topline dynamics are accompanied by a high degree of market concentration: as of the latest assessment the leading three companies command a dominant share of the market, with the top five firms controlling north of 90% of commercial activity — a structure that both accelerates commercialization momentum and raises strategic barriers for new entrants.
Worldwide Pediatric Respiratory Syncytial Virus Infection Market
Why this report matters for 2026 strategic decisions
-
Timing and prioritization: With multiple late-stage clinical programs and newly expanded regulatory labels, 2026 will be a critical year for sequencing clinical investments, launches and capacity commitments. The report pinpoints where momentum is concentrated, and where incremental investments produce the highest marginal returns.
Worldwide Pediatric Respiratory Syncytial Virus Infection Market -
Go-to-market trade-offs: Manufacturers must choose between maternal immunization campaigns, infant monoclonal prophylaxis, or supportive-care strategies. Each route has distinct commercial, regulatory and payer implications — our analysis clarifies where to allocate limited commercial resources for fastest adoption.
-
Pricing and reimbursement strategy: Rapid uptake in some markets is already being shaped by payer coverage decisions and list pricing dynamics. The report synthesizes pricing references, reimbursement precedents and value dossiers to inform negotiations and forecasting.
-
Supply chain and manufacturing planning: The industry has expanded RSV biologics production capacity materially, but capacity will be uneven geographically and by platform. Our modelling helps companies balance inventory, contract manufacturing arrangements and long-term capital projects to support 2026 launches and beyond.
Contents and practical deliverables in the report
This research is designed as a practical playbook, not just an academic exercise. Key modules include:
-
A transparent market-sizing model (base year 2025) with scenario engines to evaluate upside/downside cases driven by regulatory outcomes, adoption curves and pricing sensitivity.
-
Commercial launch blueprints tailored to each prophylactic approach: maternal vaccination, long-acting monoclonal antibodies, and supportive-care therapies. Each blueprint includes channel mix considerations, provider engagement tactics and lifecycle revenue levers.
-
Payer-access and HTA pathway maps for priority markets, with templated evidence packages and economic case structures to accelerate formulary inclusion.
-
Supply chain and manufacturing gap analysis, highlighting geographic chokepoints and mitigation options (contract manufacturing partners, fill-and-finish investments, inventory hedging).
-
Competitor playbooks and scenario-based win/lose matrices for M&A, licensing and co-commercialization strategies.
-
Real-world evidence (RWE) roadmaps and post-market surveillance frameworks to protect and extend market access.
Competitive landscape — what incumbents and challengers are doing
The pediatric RSV market is currently led by a small group of established biopharma companies and rapid innovators. Key strategic positions to note:
-
AstraZeneca (co-commercialized with Sanofi): Markets a long-acting monoclonal antibody for infant RSV prevention and has recently secured expanded authorization that broadens the eligible infant population entering their first RSV season. This regulatory expansion materially changes addressable demand profiles and strengthens tender and hospital-channel leverage.
-
Sanofi: As co-developer and commercial partner, Sanofi’s role remains central to lifecycle management, global rollout and manufacturing scale-up activities tied to the monoclonal product.
-
Pfizer: Leads the maternal vaccination strategy with a bivalent preF vaccine and has secured strong public-health endorsements that accelerate maternal immunization programs in several countries — a strategic channel that reshapes early-life protection approaches.
-
GSK: While primarily focused on an adult RSV vaccine, GSK’s platform and regulatory expertise mean sustained evaluation for pediatric indications and potential line-extension strategies.
-
Merck and Moderna: Advanced candidates — including monoclonal antibodies and mRNA-based vaccines — are moving through late-stage clinical development. Positive Phase 3 results and priority-review designations in 2025 have compressed timelines and made 2026 a make-or-break year for market-entry planning.
Recent industry events that materially affect commercial strategy include regulatory label expansions, major public-health recommendations for maternal immunization, positive late-stage trial readouts, and prioritized regulatory reviews. On the payer front, significant coverage decisions in the U.S. have already demonstrated rapid willingness to reimburse eligible newborn populations, altering commercial forecasting and uptake assumptions.
Market dynamics to factor into 2026 planning
-
Regulatory volatility and acceleration: Priority reviews and label changes can rapidly expand addressable populations; teams must be ready to scale medical affairs and supply contracts on short notice.
-
Reimbursement precedents: Early high-coverage decisions for specific products create reference cases that will be used in negotiations elsewhere. Manufacturers should plan differentiated evidence packages to replicate success in markets with less mature payer systems.
-
Manufacturing and supply capacity: Industry investments have increased monoclonal antibody capacity, but new capacity is concentrated. Firms that fail to secure capacity in advance risk losing share despite clinical success.
-
IP and generic pressure: The expiration of legacy patents has opened avenues for biosimilars/generics that will change price ceilings and competitive dynamics; lifecycle strategies must incorporate defense and hedging mechanisms.
Strategic recommendations for 2026
-
For incumbents: Solidify contracting models with volume-based discounts and real-world outcomes clauses; accelerate RWE collection to defend premium pricing; prioritize capacity agreements to avoid release bottlenecks at launch.
-
For challengers: Use differentiated platforms (e.g., mRNA) to pursue first-mover or niche-indication strategies; consider regional launches where regulatory and payer pathways are fastest and scale later; pursue strategic alliances for distribution and fill-and-finish arrangements.
-
For investors and corporate development teams: Target opportunities where regulatory catalysts in 2025–2026 can produce outsized top-line inflection; prioritize targets with secure manufacturing pathways and clear reimbursement precedents.
-
For hospitals and healthcare systems: Integrate RSV prevention into maternal and neonatal care pathways and prepare logistics for seasonal campaigns; early alignment with payers and public-health bodies will reduce friction at the point of care.
Risks and scenario planning
Our scenarios highlight several downside and upside drivers that companies must monitor closely in 2026:
-
Downside: Regulatory delays, payer pushback on pricing, manufacturing shortfalls, or an unexpected reduction in vaccine/antibody effectiveness due to viral evolution could materially slow adoption.
-
Upside: Rapid policy endorsements (for example, sweeping maternal immunization recommendations) and additional label expansions can accelerate uptake beyond central-case projections and justify earlier capacity investments.
How PW Consulting supports your 2026 playbook
Our engagement suite is built to move teams from strategy to execution quickly. Services include bespoke market modelling, launch-readiness assessments, payer negotiation simulations, partner/asset diligence, and supply-chain optimization programs. For firms preparing for a 2026 entry or defensibility program, we offer a rapid “90-day readiness” engagement that produces an executable commercialization plan and a quantified risk register.
Next steps — where to obtain the full intelligence
This article is a condensed strategic preview designed to demonstrate the report’s practical value while preserving the granular, modeled intelligence available in the full study. The full report contains detailed country- and channel-level forecasts, downloadable financial models, competitor product timelines, and proprietary scenario tools that underpin the conclusions above. To access the complete dataset and proprietary models that inform 2026 decision-making, please visit the PW Consulting report page or contact our team for a briefing and sample model.
For detailed analysis of this topic, please visit the official page: Worldwide Pediatric Respiratory Syncytial Virus Infection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com