

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
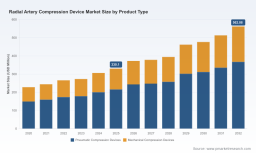
PW Consulting: Radial Artery Compression Device Market to Grow from USD 330.1 Million in 2025 to USD 562.08 Million by 2032 at a 7.9% CAGR

Worldwide Radial Artery Compression Device Market: Strategic Insights for 2026 Decision‑Making
PW Consulting’s new market brief—supported by a full market research dossier covering 2020–2025 (base year 2025) and a forecast out to 2032—provides executive teams with the focused, decision‑grade intelligence required to shape growth, M&A and commercialization strategies in 2026. The worldwide radial artery compression device market is on a sustained growth trajectory: our model shows expansion from an estimated USD 228.45 million in 2020 to USD 330.10 million in 2025, with a forecast compound annual growth rate (CAGR) of 7.9% through 2032, when the market is expected to approach USD 562.08 million. These headline figures frame an attractive market environment—but the strategic value of our work is in the granular, operable insight beneath those totals.
Worldwide Radial Artery Compression Device Market
Why This Report Matters for 2026 Strategy
-
Time-sensitive go-to-market decisions. 2026 is the inflection year for many radial access pathways and device-adjacent innovations. Organizations that align product launches, regulatory filings and commercial investments to the demand curves we model will capture disproportionate share during the next two funding and procurement cycles.
Worldwide Radial Artery Compression Device Market -
Regulatory and reimbursement clarity. The devices are regulated primarily through 510(k) pathways in the U.S. and commonly carry CE marks for Europe; procurement economics are influenced by procedural bundling under Medicare and similar payors. Understanding where regulatory friction and billing constraints create pockets of competitive advantage is essential for prioritizing resources.
Worldwide Radial Artery Compression Device Market -
Concentration and competitive dynamics. The market exhibits meaningful concentration: the top three vendors account for a majority share and the top five consolidate an even larger portion of market value. That structure creates both barriers and opportunities—incumbents can leverage scale and installed OEM relationships, while specialized entrants can displace legacy players by winning distinct clinical or cost advantages.
What’s Inside the PW Consulting Dossier (Operational Summary)
-
Full market sizing and multi-scenario forecasts (2026–2032) with sensitivity analyses calibrated against adoption curves for transradial and distal radial access.
-
Clinical pathway mapping that translates procedure mix and hospital/ASC workflows into device demand, dwell time and consumable-replacement economics.
-
Regulatory and reimbursement playbook that flags filing strategies, incremental data requirements, and the commercial implications of procedural bundling in major payor geographies.
-
Supply‑chain risk heatmap focused on medical‑grade polymers, skin‑contact materials and transparency housings; alternative sourcing pathways and cost levers for 2026 procurement decisions.
-
Competitive benchmarking: qualitative and quantitative vendor scorecards covering product features (e.g., dual‑balloon patent hemostasis, transparent housings, size range), clinical evidence, geographic reach, and pricing posture—designed for rapid vendor selection or M&A diligence.
-
Commercial playbooks: targeted segmentation strategies, channel design for hospitals vs ambulatory surgical centers vs specialty clinics, and pricing tactics supported by elasticity testing and contract negotiation frameworks.
-
Investment thesis and deal pipeline: prioritized M&A targets, plausible consolidation scenarios, and valuation sensitivities for financial sponsors and strategic acquirers.
Market Dynamics: Drivers, Constraints and Supply Considerations
Demand drivers remain clinical and operational: broader adoption of radial access for catheterization, the rise of distal radial approaches, and heightened clinician preference for devices that support patent hemostasis while minimizing nerve compression. Procedure volume recovery post‑pandemic and the shift toward outpatient settings (ASCs) continue to reweight where devices are procured and used.
Regulatory dynamics are stable but nontrivial. Many radial compression devices are cleared through FDA 510(k) pathways (class I/II designations), and the ability to leverage existing clearances or CE marking materially shortens time to market in key geographies. On the reimbursement side, procedural bundling under Medicare and other third‑party payors limits additive device margin capture by providers, placing a premium on institutional value propositions—reduced staff time, lower complication rates, faster turnover—rather than standalone billing.
On the supply side, manufacturers depend on medical‑grade polymers, latex‑free patient contact materials, and transparent housings to meet clinician requirements for visibility and skin safety. These inputs are subject to sourcing concentration and cost variability; our supply‑chain scenarios quantify unit‑cost sensitivity to key polymer price shocks and lead‑time disruptions.
Competitive Landscape: Who’s Playing and Where They Compete
The competitive field blends global incumbents and nimble specialists. A non‑exhaustive set of market participants included in our analysis are:
-
Terumo Corporation (Tokyo): Known for the TR Band product family—dual‑balloon technology that emphasizes precise hemostasis, patent hemostasis protocols, and design features to reduce nerve compression risk.
-
Merit Medical Systems, Inc. (South Jordan, Utah): Broad radial portfolio including PreludeSYNC and related devices; recent 2025 releases (e.g., Prelude Wave Hydrophilic Sheath Introducer with SnapFix Securement) expand Merit’s sheath-to‑hemostasis offering and provide cross‑sell opportunities.
-
Teleflex Incorporated (Wayne, Pennsylvania): Combines positioning splints and topical hemostatic adjuncts to offer a systems approach to radial access care.
-
Abbott Laboratories (Abbott Park, Illinois): Offers integrated hemostasis solutions and capital equipment relationships that can accelerate adoption among institutional customers.
-
Advanced Vascular Dynamics / Semler Technologies (Portland): A portfolio of radial and femoral hemostasis devices often cleared for major markets, positioning the company as a clinical practice innovator.
-
Regional and specialty players (e.g., TZ Medical, Lepu Medical, Beijing Demax, Forge Medical, Galt Medical, Ates/Benrikal, St. Stone, Rising Medical): These firms are important sources of product innovation, price competition and differentiated form‑factors, especially in local markets and niche channels.
Our competitive analysis identifies where feature differentiation (e.g., ease of achieving patent hemostasis, device ergonomics, disposability and packaging), channel strength (hospital group agreements, ASC distributors), and regulatory footprints (510(k), CE marking) most directly translate into commercial advantage.
Strategic Implications and Recommendations for 2026
-
Incumbent manufacturers should prioritize bundled, clinically validated solutions that reduce total procedure cost and staff time. Investment in complementary products (sheaths, securement, topical hemostats) and clinical evidence generation will erect higher switching costs.
-
New entrants and challengers need to pick high-leverage niches: differentiated features for distal radial approaches, compelling cost‑per‑procedure economics for ASCs, or superior ergonomics that reduce nursing time. Focused pilots with high‑volume network partners accelerate diffusion.
-
Private equity and M&A buyers should use the market concentration metrics and our vendor scorecards to identify bolt‑on targets that deliver feature complementarity or geographic expansion—especially where incumbents’ margins can be improved via supply chain rationalization.
-
Hospital and ASC procurement teams should use scenario models to evaluate total cost of ownership across device families, and to structure contracts that reward clinical outcomes and throughput improvements rather than unit price alone.
60‑ and 180‑Day Tactical Playbook for Executives
-
Days 0–60: Run a rapid internal audit—procurement footprints, usage per procedure, price per device, and supply‑chain single points of failure. Validate assumptions against our short report snapshot and request targeted vendor scorecards.
-
Days 60–180: Initiate two parallel projects—a clinical outcomes pilot with a high‑volume center and a sourcing optimization program targeting polymer and housing suppliers. Use pilot results to renegotiate contracts and justify new product introductions in 2027 planning cycles.
What We Intentionally Withhold Here (And Where to Get It)
Consistent with the “trailer” principle of this release, we present the high‑confidence, strategic conclusions and headline market metrics above while withholding the granular segment tables, region‑by‑region sizing, end‑user splits, and vendor share matrices that are essential to transactional diligence. The full PW Consulting report contains those datasets—together with downloadable scenario models, vendor scorecards, and negotiation playbooks—designed to be used directly in boardrooms and M&A committees.
Access to the complete dataset and proprietary models is available through the PW Consulting report portal. For strategy teams preparing 2026 budgets and for investors sizing opportunities, the full report is the practical next step to convert the market’s growth potential into a defensible plan.
Contact PW Consulting to request a guided briefing, obtain customized slices of the model for your geography or channel of interest, or to commission a bespoke vendor due diligence package targeted to an imminent transaction.
For detailed analysis of this topic, please visit the official page: Worldwide Radial Artery Compression Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com