

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Worldwide High Flow Ventilator Market to Grow at 9.25% CAGR, Reaching USD 2,136.21 Million by 2032
By pmarketresearch, 2026-07-17
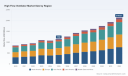
Worldwide High Flow Ventilator Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
PW Consulting today publishes an executive market brief synthesizing our proprietary analysis of the worldwide high flow ventilator market. Designed as a strategic planning tool for senior executives, investors, and health-system procurement leaders, this briefing crystallizes the market dynamics that will shape capital allocation, product roadmaps, and M&A choices through 2026 and beyond.
Worldwide High Flow Ventilator Market
Why this market matters in 2026
High flow oxygen therapy has moved from a niche adjunct to a core modality in acute and subacute respiratory care. Our sizing work shows the global market expanding from a base of approximately USD 1,150 Million in 2025 to an estimated USD 2,136 Million by 2032, implying a compound annual growth rate of 9.25% over the forecast horizon (2026–2032). That growth is being driven by convergent forces: persistent demand for non‑invasive respiratory support across care settings, heightened hospital procurement to reduce intubation rates and length of stay, and vendor innovation that compresses clinical workflows and lifecycle costs.
Worldwide High Flow Ventilator Market
Report structure and practical outputs
The full PW Consulting report is built as an operational playbook for 2026 decision-making. Key deliverables include:
Worldwide High Flow Ventilator Market
- Market sizing and consensus-aligned forecast (base year 2025; historical series 2020–2025; forecast period 2026–2032) with scenario sensitivity for demand shocks and adoption curves.
- Competitive intelligence dossiers covering product portfolios, regulatory footprints, distribution strategies, and differentiated capabilities for leading suppliers.
- Regulatory and reimbursement mapping that ties device classification and 510(k) dynamics to go‑to‑market timing and evidence-generation strategies.
- Commercial playbooks segmented by buyer archetype (acute care buyers, ambulatory center purchasers, and homecare programs) with procurement negotiation levers, TCO templates, and service model options.
- Technology and clinical trend analysis (including single‑circuit disposables, heated humidification advances, and integration of high flow capability into multifunction ventilators) and implications for product roadmaps.
- Supply‑chain and manufacturing risk assessment, including component concentration and ramp strategies for rapid scale-up in pandemic-resurgence scenarios.
- Investment and M&A scoring, with prioritization frameworks for bolt-on acquisitions, strategic partnerships, and cross‑licensing opportunities.
- An interactive dataset and financial model (Excel) that allows users to run custom scenarios and extract the granular tables referenced in our executive narrative.
Competitive landscape — what we distilled
The high flow ventilator arena displays a moderate-to-high degree of concentration. Our CR3 sits just above fifty percent and the top five suppliers collectively command approaching three quarters of the market, indicating meaningful barriers to entry but also space for focused challengers with differentiated propositions.
Several archetypes of competitors are shaping the market:
- Large, diversified ventilator OEMs that bundle high flow capability into broader critical care platforms (examples include multinational medical technology groups). Their advantages are integrated clinical workflows, installed base servicing, and cross-selling into ICU suites.
- Specialist high flow innovators who lead in modality-specific engineering and clinician adoption (companies with legacy HFNC/HVT product lines). These firms often set clinical practice norms and drive disposable accessory ecosystems.
- Emerging challengers and medtech entrants that emphasize cost-effective ventilation platforms or single-circuit disposables tailored for multi‑population use in neonatal, pediatric, and adult patients.
Notable company-level observations from our competitive audit:
- Fisher & Paykel Healthcare retains a leadership position via product depth in nasal high flow systems and strong clinical preference in several markets. Their heated humidification expertise remains a high barrier for newcomers looking to match physiologic performance.
- Vapotherm’s focus on high velocity nasal insufflation and recent regulatory progress strengthens its clinical footprint. Their product architecture and disposable strategy create high switching costs where adoption is established.
- Large ventilator manufacturers (including players such as Hamilton Medical, Dräger, Philips, Medtronic, Getinge, and others) are increasingly embedding high flow modes into intelligent ventilator platforms — a strategy that leverages installed base relationships and service contracts to accelerate adoption in critical care environments.
- Regional OEMs and new entrants (for example, firms expanding from adjacent respiratory device segments) are targeting price-sensitive channels and homecare, applying lean manufacturing and remote monitoring to capture share.
Regulatory, reimbursement and procurement dynamics
Regulation and reimbursement are no longer background considerations — they are core components of commercial strategy. High flow devices are regulated in the United States as Class II devices under the relevant CFR code and commonly require 510(k) clearance to market. Recent approvals have emphasized single‑circuit disposables and multi‑population claims, which compress clinical training needs and can materially alter procurement preferences.
On reimbursement, ventilators with multi‑function capabilities commonly fall under frequently and substantially serviced payment categories for home use; specific HCPCS codes and monthly rental models materially affect the economics of homecare expansion. From a hospital CAPEX perspective, acquisition costs for hospital‑grade high flow systems remain several times higher than low‑flow oxygen setups, but procurement committees increasingly consider total cost of care — reductions in ICU days and intubation rates can justify larger purchases when supported by robust clinical and economic evidence.
Recent developments that alter the 2026 playbook
- Regulatory milestones continue to reframe addressable markets. For example, Vapotherm secured FDA 510(k) clearance in 2026 for a single disposable All Patient Circuit that spans neonatal through adult patient groups — a clear commercial accelerant for sites seeking inventory simplification and workflow uniformity.
- OEMs from high-growth regions have advanced U.S. clearances in recent years, broadening competitive pressure across price and service dimensions and expanding choice for large health systems.
- New product entrants designed for cost-efficient critical care ventilation (cleared in recent years) highlight a persistent opportunity for value-oriented platforms in regional and resource-constrained settings.
Strategic implications and recommended actions for 2026
For corporate executives and health‑system leaders planning in 2026, PW Consulting highlights five pragmatic strategic levers:
- Prioritize clinical-evidence investments that map directly to procurement KPIs. Sponsor randomized or real-world studies that demonstrate intubation avoidance and LOS reductions — these outcomes are decisive in hospital CAPEX committees and reimbursement modeling.
- Rationalize portfolio architecture around clinician workflow simplification. Single‑circuit disposables and multi‑population claims materially shorten training and inventory cycles; product roadmaps should prioritize such features where technically feasible.
- Align regulatory pathways and launch sequencing with reimbursement strategy. Obtain indications and payment codes that unlock rental and homecare economics early in product commercialization to maximize uptake.
- Adopt hybrid commercial models that combine service contracts, managed equipment services, and outcome-based pricing pilots. This mitigates purchasing cyclicality and differentiates offerings in tender processes.
- Evaluate M&A and partnership opportunities to shore up consumables ecosystems or to buy clinical evidence and distribution capabilities. Given the market’s concentration, targeted bolt-on acquisitions can be an effective route to scale quickly without having to displace entrenched incumbents directly.
How to use the PW Consulting deliverable
The brief we release today is a director‑level synthesis intended to orient strategy discussions and prioritize near-term decisions. The full report contains the granular datasets, supplier scorecards, clinical trial matrices, and an interactive financial model that together enable:
- Custom modeling of regional demand scenarios and price elasticity assumptions;
- Vendor due diligence checklists and integration playbooks for M&A; and
- Procurement negotiation templates that quantify lifecycle cost trade-offs between platform purchase and bundled service models.
To preserve the integrity of our competitive analysis and to drive direct engagement, the full subsegment tables and company-level revenue splits are accessible only through the complete report on our site. This “trailer” approach gives decision-makers a rigorous preview while ensuring the actionable inputs required for bidding, capital planning, and product strategy are delivered as part of the full intelligence package.
Final assessment
2026 is a decisive year for stakeholders in the high flow ventilator market. Growth trajectories and clinical imperatives make this category a strategic frontier for medtech R&D and health system modernization. Market expansion is substantial, evidenced by robust CAGR and a doubling‑plus market value through the forecast period, and the competitive dynamics — characterized by a concentrated top tier and nimble challengers — reward clarity of strategy, speed of evidence generation, and operational excellence in supply chain execution.
PW Consulting’s Worldwide High Flow Ventilator Market report translates this complexity into executable strategies. For executives preparing 2026 budgets, pursuing M&A, or building go‑to‑market plans, the full report is designed to be the single source of truth that balances rigorous data with pragmatic recommendations.
Access details and executive summaries are available on the PW Consulting web portal. For tailored briefings, scenario workshops, or bespoke due diligence engagements, contact our Respiratory Devices practice team.
For detailed analysis of this topic, please visit the official page: Worldwide High Flow Ventilator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Radiation Dose Optimisation Software Market to More Than Double — From USD 435.5 Million in 2025 to USD 917.37 Million by 2032 at an 11.23% CAGR
By pmarketresearch, 2026-07-17
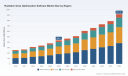
Worldwide Radiation Dose Optimisation Software Market — Strategic Briefing for 2026
PW Consulting’s latest market study on the Worldwide Radiation Dose Optimisation Software market provides a focused, decision-grade perspective designed to inform executive action in 2026. Anchored on a 2025 base year and a comprehensive historical review (2020–2025), the report projects the market through 2032. At the macro level, the market is expected to sustain robust expansion — growing from a global market size of USD 435.5 Million in 2025 toward a substantially larger opportunity by 2032, reflecting a compounded annual growth rate (CAGR) of 11.23% across the 2026–2032 forecast period. This briefing summarizes the strategic implications, competitive dynamics, regulatory and technology catalysts, and the practical deliverables contained in the full report — while reserving the detailed segment- and region-level tables for the full report download.
Worldwide Radiation Dose Optimisation Software Market
Why this brief matters for 2026 corporate decisions
-
Time-sensitive strategic moves: 2026 will be a pivotal execution year for vendors and healthcare providers as buyers shift from pilot projects to enterprise-wide deployments. The pace of adoption and the sustained CAGR imply that first-mover advantage in scalable, enterprise-grade offerings will translate into outsized commercial returns.
Worldwide Radiation Dose Optimisation Software Market -
Portfolio and product planning: Vendors must prioritize regulatory clearances, AI validation, and multi-modality interoperability now to capture share in the high-growth window. Equally, hospital systems should formalize procurement roadmaps to capture clinical and operational ROI from dose optimisation tools.
Worldwide Radiation Dose Optimisation Software Market -
Investment and M&A timing: The market’s structure and growth profile create predictable windows for bolt-on acquisitions (to close capability gaps) and for late-stage investments that de-risk technology and regulatory pathways before scaling.
Market dynamics: drivers, regulation, and technology
The industry is being shaped by three reinforcing dynamics. First, regulatory and accreditation pressure is accelerating adoption: by 2024, approximately 78% of U.S. hospitals had implemented AI-powered dose management systems in response to imaging safety standards, underscoring a shift from discretionary to compliance-driven purchasing. Parallel regulatory activity continues: 510(k) clearances for advanced dosimetry software and harmonized requirements under EU MDR for patient-specific dosimetry are converging to raise market entry bars but also to expand clinical use-cases.
Second, innovation in AI and image-reconstruction is delivering material clinical benefits. Recent clinical syntheses indicate that AI-driven reconstruction and denoising algorithms can deliver clinically meaningful radiation reductions across CT applications — often in the range of tens of percentage points — while preserving diagnostic quality. These capability gains are meaningful competitive differentiators and are reshaping value metrics buyers use to assess suppliers.
Third, modality proliferation (CT, fluoroscopy/interventional suites, mammography, radiography, and targeted radionuclide therapies) and the move toward enterprise imaging strategies are increasing demand for solutions that handle multi-vendor environments and aggregate dose data for population health, patient-specific planning, and regulatory reporting.
Market structure and implications
The market shows evidence of moderate concentration: the top three vendors account for a significant portion of total revenue, and the top five increase that share materially. This concentration (CR3 ~42.5%; CR5 ~61.2%) suggests a competitive landscape where leading global incumbents command advantages in enterprise sales, regulatory credentials, and installed base integration, while specialist and regional vendors compete on niche capabilities, rapid innovation, and service-led business models.
For strategists this means two concurrent approaches are rational: (1) incumbents should double down on enterprise features, certification, and channel partnerships to protect and grow their installed base; (2) challengers and pure-play innovators should emphasize clinical evidence, speed-to-integration, and targeted regulatory clearances where they can create defensible niches.
Competitive landscape — who to watch
The market is populated by a mix of multinational imaging OEMs, enterprise imaging vendors, and specialized software innovators. Key players examined in the report include global OEMs and specialists that differ by go-to-market, product scope, and clinical focus:
-
GE HealthCare — Offers DoseWatch, an enterprise-capable dose management and optimisation platform with multi-vendor monitoring, real-time alerts, and protocol optimisation modules suited for large health systems.
-
Siemens Healthineers — Provides teamplay Dose, a solution that aggregates dose data across modalities and supports quality assurance and compliance workflows for enterprise imaging programs.
-
Bayer AG — Through its radiation safety offerings, delivers personalized radiation and contrast dose management tools with emphasis on workflow integration and compliance reporting.
-
Koninklijke Philips N.V. — Integrates DoseWise Portal and related modules into diagnostic and interventional imaging suites, focusing on automated dose tracking and regulatory reporting.
-
Sectra AB — Offers web-based DoseTrack for automatic collection, storage and monitoring of dose data, emphasizing ease of deployment and reporting.
-
Qaelum N.V. — A specialist in flexible, multi-facility dose monitoring solutions designed for heterogeneous imaging estates.
-
FUJIFILM and Canon Medical Systems — Both integrate dose tracking and protocol optimisation within broader imaging portfolios, targeting customers that prefer vendor-aligned ecosystems.
-
Regional and specialist players — PACSHealth, Medsquare, DOSIsoft, INFINITT, and other innovators provide focused capabilities such as patient-specific dosimetry, radionuclide therapy planning, and modular dose tracking for research and specialty clinics.
Notable recent regulatory and product developments reinforce the speed of innovation: in March 2025, DOSIsoft’s PLANET Onco Dose secured a 510(k) clearance extension for expanded radionuclide therapy dose computation capabilities, and in September 2025 an AI-powered dose prediction solution (Dose+) received FDA 510(k) clearance for clinical use in the U.S. These events illustrate dual trends — specialization in targeted radionuclide dosimetry, and fast-moving AI entrants that are moving through regulatory gates.
What the full report delivers — operational content for 2026
The PW Consulting report is designed for immediate operational use by executives, product teams, procurement officers, and investment professionals. Key deliverables include:
-
Robust market-sizing and forecast model (USD Million), with sensitivity scenarios and CAGR validation across 2026–2032.
-
Vendor scorecards that assess technology maturity, regulatory status, clinical evidence, interoperability, and commercial model (license vs. SaaS vs. services).
-
Buyers’ decision frameworks and procurement checklists — including integration templates for enterprise imaging, data flow maps, and clinical validation study requirements.
-
Deal playbooks for investors and M&A teams: target prioritization, valuation comparables, and regulatory risk matrices.
-
Clinical and operational ROI templates that translate dose reductions and workflow efficiencies into financial and compliance metrics tailored to hospital and imaging centre buyers.
-
Regulatory tracker and certification pathroadmaps for FDA, EU MDR and relevant national bodies, plus an action plan for securing 510(k)/CE Mark where applicable.
-
Use-case vignettes and implementation timelines for enterprise rollouts, including pilot-to-scale staging and KPIs to govern success.
To preserve the report’s role as the authoritative source, the public briefing highlights the nature and utility of these deliverables without reproducing the full tables and granular segment splits; purchasers of the full report gain access to the complete datasets, regional and application breakdowns, and vendor benchmarking matrices.
Actionable recommendations for stakeholders in 2026
-
Vendors: Prioritize regulatory strategies (510(k)/CE) for differentiated capabilities (AI-driven denoising, radionuclide dosimetry), expand SaaS-native delivery for recurring revenue, and invest in enterprise interoperability and API-first architectures.
-
Healthcare providers / CIOs: Formalize enterprise dose governance, mandate vendor-neutral data aggregation, and include dose management KPIs in imaging service contracts. Run head-to-head pilots that measure clinical efficacy, workflow impact, and TCO (total cost of ownership).
-
Investors / M&A teams: Target specialists with validated clinical outcomes or cleared regulatory pathways, and prioritize assets that de-risk enterprise integration (e.g., vendor-agnostic middleware, patient-specific dosimetry for radionuclide therapies).
-
Regulators and policy-makers: Support harmonized guidance for AI validation and create clear performance endpoints for dose optimisation tools to accelerate safe adoption.
How to use the report to inform your 2026 playbook
The full PW Consulting report transforms high-level trends into executable plans: operational scorecards inform product roadmaps; the regulatory tracker accelerates clearance strategies; and the financial models quantify investment timing. For teams preparing budgets, negotiating vendor agreements, or scouting acquisition targets, the report supplies both the “what” (demand drivers, growth vectors) and the “how” (checklists, templates, vendor benchmarks) required to act decisively in 2026.
If your organization needs targeted briefings — for example, a vendor short-list for a multi-hospital roll-out, a regulatory readiness gap analysis, or an investor diligence pack — PW Consulting offers bespoke workstreams that leverage the report’s underlying models and primary research to produce tailored recommendations and deliverables.
To access the full dataset, regional and application breakdowns, and the vendor benchmarking matrices that underpin these strategic recommendations, please visit PW Consulting’s report page for the Worldwide Radiation Dose Optimisation Software Market or contact our advisory team for a private briefing and procurement toolkit.
For detailed analysis of this topic, please visit the official page: Worldwide Radiation Dose Optimisation Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide LAN Cable Tester Market Set to Expand from USD 315.5 Million in 2025 to USD 468.8 Million by 2032 at a 5.82% CAGR
By pmarketresearch, 2026-07-17
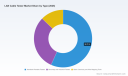
Worldwide LAN Cable Tester Market — Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s latest market brief on the Worldwide LAN Cable Tester Market delivers an actionable, strategy-focused preview designed for enterprise technology leaders, procurement teams, systems integrators, and investors preparing decisions in 2026. Our analysis synthesizes observed deployment patterns, standards-driven compliance needs, and vendor roadmaps into a forward-looking narrative. At the macro level, the market has expanded from approximately USD 225.0 Million in 2020 to roughly USD 315.5 Million in 2025, and is forecast to continue growing through the 2026–2032 horizon at a compound annual growth rate (CAGR) of 5.82%, reaching an expected USD 468.8 Million by 2032. Market concentration is meaningful—our CR3 and CR5 indicators point to a sector where a compact group of suppliers account for the majority of revenue—creating both competitive barriers and predictable partner choices for enterprise buyers.
Worldwide LAN Cable Tester Market
Why this matters for 2026 strategic planning
-
Network upgrade cycles: The migration of enterprise access networks to 2.5G/5G/10GBASE-T and faster optical uplinks to support Wi‑Fi 7/8 and AI-ready workplaces materially changes tester requirements. Buyers must plan for tools that validate multi-gig copper links, PoE performance, and higher-layer Ethernet behaviors before device rollouts.
Worldwide LAN Cable Tester Market -
Compliance and liability: Standards such as TIA/EIA‑568A continue to require documented testing of Ethernet terminations for many public and large private sector procurements. Failing to procure certified testing capability exposes programs to rework and contract risk.
Worldwide LAN Cable Tester Market -
Hyperscale and edge demands: Very Small Form Factor (VSFF) fiber deployments and higher-density optical connectors in data centers mean that test portfolios now must span copper and fiber workflows, with traceability for higher-speed 400G+ link validation in cloud and AI-focused infrastructures.
Key market dynamics shaping near-term choices
Three forces will dominate supplier selection and product investment decisions in 2026:
-
Technology convergence: Certification, qualification/verification, and continuity tools are converging in capability and in field usability. Frontline technicians increasingly require handheld qualification tools that can validate PoE up to higher wattages and quickly triage link issues—while back‑office teams need certifiers that produce audit-grade reports.
-
Value chain consolidation: A mid-to-high level of market concentration means large, established vendors continue to win enterprise rollouts and service-provider contracts. However, accessible and lower-cost handheld offerings maintain strong demand in the SMB and MSP segments, creating parallel product tiers.
-
Standards and procurement rigor: Public and regulated projects are enforcing documented test evidence, which obliges organisations to standardise on test procedures and tools across multi-vendor cabling and equipment deployments.
What PW Consulting’s report delivers — practical assets for decision-makers
We designed this deliverable as a strategic playbook, not an academic summary. The report combines quantitative forecasting with field-proven operational templates that procurement and engineering teams can apply immediately. Highlights include:
-
Market sizing and validated growth forecast (2020–2032) with scenario modelling to stress-test budgets under technology acceleration or slowdown assumptions.
-
Decision matrices mapping use-cases (e.g., enterprise campus, data center, service provider turn‑up, MSP maintenance) to recommended tester types and capability thresholds.
-
Supplier diagnostic framework that evaluates vendors on product breadth, reporting and cloud integration, field ergonomics, certified test modes, and commercial support—enabling RFP language and scorecards.
-
Procurement playbook with TCO templates, spares & calibration planning, and service-level considerations for onsite vs. managed testing models.
-
Lab-to-field validation protocols and a reproducible test plan that maps lab certification methods to real-world qualification steps, including PoE stress procedures and multi-gig copper checks.
-
Risk register for programme managers covering regulatory, interoperability, and obsolescence risks tied to cabling and test equipment choices.
To preserve commercial value for subscribers, the report deliberately limits public disclosure of our detailed segment-level revenue splits and price-point tables—in other words, this release shows the strategic contours and tools you need, while the granular maps and supplier-pricing cells are available in the full report.
Competitive landscape — what to watch in 2026
The supplier ecosystem combines long-standing test-platform incumbents with agile handheld specialists. Our competitive synthesis recognizes distinct value propositions:
-
High-end certifiers and systems vendors maintain dominance where audit-grade certification and multi-protocol testing are required. These suppliers focus on standards compliance, extensive reporting, and integration with enterprise asset management systems.
-
Handheld and frontline-focused vendors compete on ergonomics, speed, and targeted features such as multi-gig validation and enhanced PoE testing. These products are increasingly adopted by MSPs, onsite technicians, and fast-turn installers.
-
Cost-effective entrants, often from regions with high manufacturing density, capture volume in the basic verification and continuity segments. Their route-to-market is frequently channel-driven and price-sensitive, supporting large distributed rollouts where audit-level certification is not mandatory.
Notable vendor activities to factor into 2026 plans include recent product refreshes and expanded PoE validation capabilities that push handhelds closer to qualification role. For example, a frontline equipment vendor released a new LinkRunner model in early 2026 that delivers faster copper link checks and PoE++ validation up to 90W—an important capability given the growth of high-power PoE devices in smart buildings and edge compute nodes.
Operational recommendations for procurement and engineering teams
-
Adopt a tiered-tooling strategy: specify a mix of audit-grade certifiers for critical links, versatile qualification testers for pre-deployment verification, and efficient continuity tools for bulk cable runs. Calibrate the mix against your risk appetite, rework cost, and regulatory obligations.
-
Standardise test artefacts: require machine-readable test reports and test naming conventions to ensure traceability across installers and over lifecycle handovers. This reduces disputes and accelerates troubleshooting.
-
Embed lab-to-field validation: before wide-scale rollouts, run a pilot combining bench certifiers and frontline qualification units to validate that field tests will replicate lab outcomes under site conditions.
-
Budget for obsolescence and calibration: plan replacement and calibration cycles into CAPEX/OPEX models; certification tools carry regulatory weight and therefore require disciplined maintenance and firmware governance.
Strategic M&A and partnership angles
For investors and strategic buyers, the market’s structure presents several playbooks:
-
Horizontal consolidation among handheld specialists can unlock distribution and service synergies targeted at MSPs and telco field teams.
-
Vertical integration between certifier makers and cloud analytics providers creates differentiation through automated compliance workflows and lifecycle asset data.
-
Technology tuck-ins—such as advanced PoE validation, automated reporting stacks, or fiber VSFF connector adapters—can rapidly raise the effective commercial value of a tester portfolio for data center customers supporting AI-scale infrastructure.
Risks and variables to monitor into 2027
-
Standards evolution: shifts in Ethernet or fiber connector standards can change validation requirements; maintain vendor roadmaps as part of contractual review.
-
Procurement policy changes: public-sector bidding rules that tighten test documentation requirements can rapidly move spend toward higher-end certifiers.
-
Technology substitution: accelerating adoption of fiber in access layers for AI and densification could reduce unit demand for copper certifiers, while increasing need for fiber-capable test instruments.
-
Channel dynamics: price competition from low-cost vendors can compress margins in continuity/verification segments even as certification remains higher-margin and supplier‑consolidated.
How to use this analysis
Use this brief as the strategic frame for 2026 budget discussions, RFP specifications, and supplier shortlisting. If your organization is planning large campus refreshes, hyperscale interconnect projects, or to scale an MSP field operation, the choices you make about test-tool portfolios will materially affect rollout speed, rework risk, and compliance costs.
Next steps — get the full intelligence
This public preview highlights the strategic implications and operational playbooks that matter for 2026. The full PW Consulting report includes the complete segment revenue breakdowns, channel pricing matrices, calibrated vendor scorecards, and downloadable test-plan templates that your teams can put to work immediately. To access the detailed datasets, supplier benchmarking tables, and the downloadable toolkit, please visit the report landing page (full subscription required).
For detailed analysis of this topic, please visit the official page: Worldwide LAN Cable Tester Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Traveler’s Diarrhea Treatment Market Set to Expand at 6.12% CAGR, New Report Reveals
By pmarketresearch, 2026-07-17
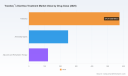
Worldwide Traveler’s Diarrhea Treatment Market: Strategic Preview for 2026 — What Leaders Must Know
Executive summary
PW Consulting’s latest market intelligence shows the Worldwide Traveler’s Diarrhea Treatment market as a resilient, mid-sized therapeutic category poised for steady expansion. After recovering through the early-2020s, the market reached an estimated USD 945.5 Million in 2025 and, under our base assumptions, is forecast to approach roughly USD 1.43 Billion by 2032 — representing a compound annual growth rate (CAGR) of approximately 6.12% across the 2026–2032 forecast window. The evolution of clinical prevention options, sustained demand for symptomatic care, and shifting distribution dynamics underpin this growth.
Worldwide Traveler¡¯s Diarrhea Treatment Market
Why this market matters for 2026 strategic planning
-
Acceleration point for pipeline entrants: The category is at a tactical inflection where late-stage vaccine programs and non-antibiotic biologics can materially alter product mix and competitive dynamics.
Worldwide Traveler¡¯s Diarrhea Treatment Market -
Commercial leverage through differentiated access: Premium pricing for targeted antibiotics in select markets coexists with broad OTC demand for symptomatic therapies, creating differentiated margin pools that influence local go-to-market choices.
Worldwide Traveler¡¯s Diarrhea Treatment Market -
Moderate concentration, meaningful opportunity: A handful of established global and regional players capture the majority of current revenues, yet the map of unmet prevention needs leaves room for new entrants and strategic partnerships.
What the PW Consulting report delivers (practical contents)
-
Robust market model: A transparent, scenario-enabled financial model covering 2020–2032 with base-year calibration to 2025, enabling what-if testing for pricing, launch timing, and reimbursement permutations.
-
Granular segmentation framework: Multi-dimensional segmentation by product class, distribution channel, and epidemiology — with adjustable levers for antibiotic vs. non-antibiotic adoption, OTC trends, and vaccine uptake. (Note: this press brief intentionally omits the detailed segment-level figures contained in the full report.)
-
Competitive intelligence dossier: Company profiles, product positioning maps, launch-readiness assessments, and commercial scorecards for leading incumbents and emerging developers.
-
Regulatory and payer landscape: Country-level policy monitors, reimbursement pathway assessments, and payer negotiation playbooks tuned for anti-infectives and prophylactic biologics.
-
Commercial playbooks and M&A screening: Prioritized strategic options for pharma, biotech, OTC brands, and specialty distributors — from licensing and co-promotion to bolt-on M&A and distribution partnerships.
-
Risk and sensitivity analyses: Epidemiology shocks, resistance trends, pricing pressure scenarios, and macro travel demand contingencies — all modeled to show downside and upside cases to 2032.
Competitive landscape: players, positions, and tactical implications
The market is anchored by established multispecialty and GI-focused firms that combine proprietary prescription antibiotics, OTC symptom relief, and supportive care solutions. Notable participants include developers of targeted non-absorbable antibiotics, major consumer health OTC brands, vaccine manufacturers, and companies developing biologic prophylactics. In concentration terms, the top three companies account for a significant share of the category’s revenues, and the top five capture a clear majority — creating a competitive environment where scale, channel reach, and regional regulatory expertise matter.
-
Bausch Health / Salix (Xifaxan/rifaximin) and other rifaximin proponents: Benefit from strong clinical positioning for noninvasive E. coli indications and sustained premium pricing structures in developed markets. Their strategy focus for 2026 should be lifecycle defense, patient access programs, and selective label extensions where clinical evidence supports expansion.
-
Cosmo Pharmaceuticals / Alfasigma and RedHill Biopharma (Aemcolo/rifamycin): Positioned as prescription alternatives with label-specific constraints (e.g., limitations for febrile or bloody presentations). Commercial playbooks should emphasize targeted physician education, diagnostic stewardship, and payer contracting to defend on-label use.
-
Consumer healthcare majors (Kenvue/Imodium, Procter & Gamble/Pepto-Bismol): Continue to capture symptomatic and prophylactic self-care demand. Their priorities are front-line availability, OTC marketing in travel channels, and digital consumer engagement to convert prophylactic interest into purchases.
-
Large pharma suppliers of broad-spectrum antibiotics (e.g., Pfizer): Remain relevant through off-label or empiric use patterns in regions where clinical practice favours macrolides or other agents for specific traveler cohorts. Strategic stewardship and alignment with local guideline committees are essential risk mitigation steps.
-
Biologic and vaccine developers (Immuron, Valneva, Scandinavian Biopharma): Represent the key disruptive vector. Immuron’s colostrum-based prophylactic approach and Valneva’s Dukoral vaccine (with cross-protection potential against LT-producing ETEC) exemplify non-antibiotic prevention strategies likely to shift long-term demand if uptake accelerates. Recent Phase 2b ETVAX data — demonstrating sizable reductions in ETEC-triggered diarrhea and regulatory readiness signals towards Phase 3 — elevates vaccine-led prevention from theoretical to investment-grade consideration.
Recent clinical and regulatory catalysts — implications for 2026
-
EVTAX vaccine advancement (Phase 2b positive data; Phase 3 readiness): The emergence of robust vaccine efficacy data converts prevention into a nearer-term commercial proposition. For manufacturers and investors, this implies planning for new distribution models (vaccination at travel clinics, pharmacies), cold-chain considerations, and economic evaluations that compare vaccination cost to acute treatment pathways.
-
Product approvals and labels remain decisive: Affirmations of label scope for rifaximin and rifamycin derivatives shape prescribing behaviour and payer coverage. Firms must craft evidence-generation strategies (real-world outcomes, health economic dossiers) that align with local reimbursement criteria.
-
OTC prophylactics and biologics: Non-antibiotic options that avoid antimicrobial resistance concerns will attract regulatory and public health attention — creating both opportunity and additional scrutiny on claims and manufacturing transparency.
Strategic implications & recommended actions for stakeholders in 2026
-
Pharmaceutical & biotech companies: Prioritise balanced portfolios that pair symptomatic/OTC offerings with defensive stewardship of prescription antibiotics. Accelerate partnerships with vaccine developers or consider in-licensing prophylactic biologics to capture upstream prevention value.
-
Commercial teams & distributors: Re-evaluate channel mixes with an emphasis on expanding digital and travel-related touchpoints (online pharmacies, travel clinics, airline/airport retail). Develop bundled offerings (pre-travel kits) that combine prophylaxis, symptomatic care, and education to increase average basket value.
-
Investors & M&A teams: Screen for assets that meaningfully shift the prevention-treatment balance — late-stage vaccines, biologics with scalable manufacturing, or OTC brands with strong travel-market penetration. Use our scenario model to price launches under multiple uptake and price-resistance assumptions.
-
Payers & health systems: Prepare HTA frameworks to evaluate prevention versus episodic treatment economics, considering both direct and indirect cost offsets from reduced traveler morbidity and travel-disruption costs.
-
Public health & guideline developers: Incorporate emerging vaccine evidence into travel medicine recommendations, and coordinate stewardship messaging that balances effective traveler protection with antimicrobial resistance mitigation.
Where the report exercises discretion — and why
In line with PW Consulting’s “trailer” approach to public releases, this brief highlights market-scale trajectories, high-consequence innovations, and strategic implications while intentionally withholding detailed sub-segment numbers (by region, drug class splits, and channel revenues) to preserve the actionable value of the full report. The comprehensive report includes the detailed, auditable segmentation that enables transaction diligence, launch planning, and payer negotiation — the very information that strategic buyers and licensing partners rely upon.
Next steps for decision-makers
-
Download the full PW Consulting report to access the complete segmentation matrices, ‘buy versus build’ M&A scorecards, and the scenario-enabled financial model calibrated to 2025 actuals.
-
Book a strategy briefing: PW Consulting offers bespoke deep-dive sessions that stress-test your 2026 commercial and R&D plans against vaccine-adoption and stewardship scenarios.
-
Engage with our market-entry playbook if you are evaluating in-licensing, regional partnerships, or an expanded OTC portfolio aimed at the travel channel — we can tailor the playbook to your asset and target geographies.
Closing perspective
The traveler’s diarrhea treatment market in 2026 is actionable: steady topline growth, clear pockets of premium pricing, and a near-term disruption vector from prevention technologies. For corporate strategists, the imperative is threefold — protect core prescription revenue through evidence and access tactics; invest selectively in prevention and non-antibiotic prophylactics; and restructure commercial routes to capture higher-value travel and digital channels. PW Consulting’s full report furnishes the detailed, executable intelligence required to translate these imperatives into tangible 12–36 month plans.
To access the full intelligence package and schedule a strategic briefing, please visit our report page.
For detailed analysis of this topic, please visit the official page: Worldwide Traveler¡¯s Diarrhea Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Predicts 10.49% CAGR from 2026–2032 for Worldwide Aircraft AFP and ATL Composites Market
By pmarketresearch, 2026-07-17
Worldwide Aircraft AFP and ATL Composites Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on Worldwide Aircraft Automated Fiber Placement (AFP) and Automated Tape Laying (ATL) Composites evaluates the commercial dynamics, technology trajectories, competitive positions and strategic levers that will shape capital and M&A decisions through 2026 and beyond. Anchored on a 2025 base year and a 2026–2032 forecast window, the report quantifies a clear growth runway — an industry compound annual growth rate of 10.49% — and delivers practical, action-oriented frameworks that procurement, operations and corporate strategy teams can deploy immediately.
Worldwide Aircraft AFP and ATL Composites Market
Why this matters for 2026 planning
-
Capital timing: With the consolidated market momentum visible at the 2025 baseline and a strong mid‑single‑to‑double‑digit growth trajectory into 2032, 2026 represents an inflection year for capacity investments, technology refreshes and automation rollouts.
Worldwide Aircraft AFP and ATL Composites Market -
Risk calibration: Recent regulatory and export-control developments, combined with material and labor cost pressures, are changing the calculus for where and how to deploy AFP/ATL assets and which partners to favor.
Worldwide Aircraft AFP and ATL Composites Market -
Competitive positioning: The market demonstrates meaningful concentration — the leading suppliers capture the majority of market value — creating both barriers and opportunities for targeted entrants, component suppliers and Tier‑1 integrators.
Macro snapshot (what the numbers tell us)
From 2020 through 2025 the market expanded steadily, establishing a robust 2025 base. PW Consulting’s forecast shows the industry nearly doubling over the 2026–2032 horizon, driven by accelerated aircraft production, expanded composite content on new platforms, and continued automation adoption across fuselage, wing and empennage programs. At a 10.49% CAGR, executives should expect both predictable demand growth and episodic volatility tied to program timing, raw material cycles and policy shifts.
Core strategic implications
-
Prioritize flexible automation: AFP and ATL investments should emphasize modularity and multi‑tape/multi‑tow capabilities to support mixed fleets and evolving layup strategies. Flexibility reduces stranded‑asset risk when platform mix or certification requirements change.
-
Localize critical supply chains selectively: Export controls and national security classifications are creating geographic constraints on machinery transfers and technology flows. Commercial planning must integrate export‑control screening and onshoring options into supplier selection and CapEx scenarios.
-
Balance CapEx with services: Given concentration among a few global vendors and the premium for specialist integration expertise, consider hybrid models that combine equipment purchases with long‑term services, performance guarantees and spares agreements.
-
Use automation to offset labor gaps: With skilled labor costs rising and worker shortages persisting, AFP/ATL adoption should be framed as a labor substitution plus qualifications upgrade strategy — reducing routine headcount while increasing demand for advanced technicians and systems engineers.
-
M&A and partnerships: The current competitive structure favors consolidation and strategic alliances. Buyers should target bolt‑on technologies that reduce cycle time, increase yield or unlock thermoplastic processing, while sellers should position on recurring revenue and serviceable installed base growth.
What our report delivers — the practical toolkit
This study is structured to be operationally useful for 2026 decision cycles. Highlights include:
-
Top‑line market sizing and a seven‑year forecast (2026–2032) with scenario alternatives that stress test demand against program deferrals and raw material inflation.
-
Technology roadmaps for AFP and ATL — maturity curves, throughput benchmarks, and certification timelines that translate process capability into production capacity plans.
-
Supplier benchmarking and strategic heatmaps that go beyond brand names to quantify installed base dynamics, service footprints and go‑to‑market models.
-
Investment playbooks: CapEx calculators, break‑even analyses, and ROI thresholds tailored for Tier‑1, OEM and large Tier‑2 operations.
-
Regulatory & compliance playbooks: Practical checklists for certification readiness (including FAA expectations around AFP process controls), and a mapped set of export‑control implications for cross‑border equipment flows.
-
M&A screening matrices and integration trackers that operationalize successful bolt‑ons and technology transfers while mitigating IP and export risks.
-
Interactive scenario dashboards (available in the full report) to model sensitivity to carbon‑fiber costs, labor inflation, and production backlog shifts.
Competitive landscape: who matters and why
The market is shaped around a small set of specialized equipment and integration providers. PW Consulting’s analysis profiles these players not just by product, but by installed base, strategic customers and recent momentum — a necessary vantage for procurement and corporate development teams.
-
Electroimpact Inc. (Mukilteo, WA, USA) — Recognized for large‑scale AFP systems used on primary structures for wide‑body programs. Their delivery track record on composite wings and fuselage components positions them as a partner for very high‑volume production and complex envelope work.
-
MTorres Group (Pamplona, Spain) — Offers both ATL and AFP platforms, with program references across narrow‑ and wide‑body programs. Their dual‑technology portfolio is attractive for OEMs managing mixed layup strategies.
-
Coriolis Composites (Quévert, France) — Specializes in multi‑tow, articulated AFP robotics suited to intricate geometries and high‑precision applications. Their focus on advanced end‑effectors and software integration makes them a prime candidate for performance‑driven upgrades.
-
Mikrosam (Prilep, North Macedonia) — A modular, cost‑competitive supplier with growing presence in thermoplastic systems and nacelle/engine component automation. Their modular approach supports geographically distributed manufacturing models.
-
Accudyne Aerospace (Independence, KS, USA) — With heritage equipment and a strong footprint in large panel manufacturing, Accudyne is a go‑to for integrators aiming to scale panel throughput with proven ATL/AFP variants.
Recent market cues underscore the pace of innovation and deployment: new AFP/ATL demonstrations at major trade shows in 2024, high‑profile deliveries in late 2023, and continued product launches that collectively suggest vendors are racing to capture program content and installed‑base services.
Key dynamics and near‑term risks
-
Raw materials: Aerospace carbon fiber demand rose sharply in 2023; feedstock volatility can materially alter unit economics for composite layup and must be modeled explicitly in 2026 budgets.
-
Backlog-driven investment: A multi‑year commercial aircraft backlog continues to be a primary demand driver for AFP/ATL automation — but program schedule slips change the timing of returns and impact supplier capacity planning.
-
Regulation & certification: Recent amendments emphasizing AFP process controls mean certification costs and lead times are increasing; procurement should insist on supplier capabilities around traceability, process control and auditability.
-
Export controls: Machinery classified under certain export control codes now faces transfer constraints. Strategic players are evaluating dual‑source strategies, domestic production lines, or licensing agreements to maintain program continuity.
-
Labor costs & skills: Rising labor costs and a constrained skilled workforce accelerate the business case for automation but raise the bar for implementation timeframes and training investments.
How to use this study in your 2026 playbook
-
Board level: Use the report’s scenario dashboards to stress test CapEx proposals against downside program deferrals and to set funding thresholds tied to specific throughput and yield improvements.
-
Operations & manufacturing: Apply the process maturity and throughput benchmarks to validate supplier proposals, optimize line balance, and develop a staged deployment plan that prioritizes early returns.
-
Corporate development: Leverage the supplier scorecards and concentration analysis to identify consolidation targets, tech tuck‑ins and service monetization opportunities.
-
Procurement & compliance: Integrate the export‑control heatmaps and certification checklists into RFPs and supplier contracts to reduce delivery and regulatory risk.
Closing — the strategic premium of insight
AFP and ATL technologies are no longer niche process improvements; they are strategic enablers that determine program competitiveness, unit cost curves and factory footprint. Our 2025‑base market sizing and 2026–2032 forecast quantify a compelling growth path, but the real advantage for 2026 decision‑makers lies in operationalizing that insight: timing investments, structuring supplier relationships, and executing M&A with a clear view of installed‑base economics and regulatory constraints.
PW Consulting’s full report delivers the granular tables, segment‑level forecasts, interactive models and supplier scorecards that executives and program leads need to convert these strategic imperatives into action. For access to the complete dataset, downloadable dashboards and implementation templates, visit PW Consulting’s market research portal to request the Worldwide Aircraft AFP and ATL Composites Market report and supporting materials.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft AFP and ATL Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Insight: Worldwide Stadiometers Market to Top USD 203.3 Million by 2032
By pmarketresearch, 2026-07-17
Worldwide Stadiometers Market — 2026 Strategic Preview
PW Consulting’s latest market study on Worldwide Stadiometers delivers a compact, practitioner's guide to the opportunity and competitive dynamics that will shape procurement, product strategy, and M&A activity in 2026. The market has shown steady expansion from an estimated US$105.12 million in 2020 to roughly US$137.0 million in 2025. Our forecast model places the market at approximately US$142.36 million in 2026 and projects growth to about US$203.3 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.8% across the 2026–2032 forecast window. This briefing highlights the report’s strategic value for decision-makers while reserving the full segment-level data and models for the complete report.
Worldwide Stadiometers Market
Market trajectory and the near-term inflection points
-
Macro momentum: The market’s steady expansion is driven by a convergence of healthcare system modernization, standardized clinical workflows, and increasing demand for digital and touchless measurement modalities that improve throughput and infection-control protocols.
Worldwide Stadiometers Market -
2026 as a tactical year: With an estimated market size of ~US$142.36 million in 2026, organizations should treat the year as a tactical window to reposition portfolios, update procurement plans, and pilot product integrations that target clinical workflow efficiency.
Worldwide Stadiometers Market -
Moderate market concentration: Market concentration metrics indicate that the top three suppliers control a meaningful share of industry revenues, with the top five increasing that concentration further. This structure supports both strategic consolidation plays and opportunities for niche specialists to scale through partnerships or targeted product differentiation.
-
Volatility and scenario variance: Our scenario suite captures short-term cyclical effects related to hospital CapEx budgets, replacement cycles for mechanical units, and episodic demand spikes for touchless devices tied to public health priorities—factors that explain some year-to-year variance in our modeled forecasts.
Why this report matters for 2026 decisions
-
Procurement optimization: Hospital and health system procurement teams can use our timing models and CapEx guidance to phase replacements (mechanical → digital/touchless) in ways that maximize ROI and minimize disruption to clinical operations.
-
Product and R&D prioritization: Vendors should prioritize investments that accelerate digital integration (connectivity to EMR and body-composition platforms), reliability in high-throughput settings, and validated touchless measurement technologies—areas we model for adoption curves and margin impacts.
-
Channel and distribution strategy: For distributors and regionally focused players, the report maps buyer personas, decision drivers across clinical, school, and sports applications, and the channel economics that determine profitable service and lifecycle models.
-
Investor playbook: Private equity and strategic buyers will find our valuation overlays, consolidation scenarios, and supplier scorecards useful for rapid target screening in a market with mid-level concentration—ideal for roll-up strategies and bolt-on acquisitions that fill functional or regional gaps.
What the PW Consulting report contains — practical, executable content
-
Transparent market sizing & forecast methodology — year-by-year market estimates from 2020 through 2032 along with sensitivity runs and scenario assumptions.
-
Procurement and CapEx playbooks — hospital budget timing calendars, replacement triggers for mechanical units, and an ROI calculator that models cost-to-benefit for digital/touchless upgrades.
-
Buyer persona and application demand profiles — clinical, academic, and sports-sector use cases with buying criteria, procurement cycles, and service expectations (note: full application share tables are available in the complete report).
-
Regulatory and reimbursement matrix — concise checklists for FDA classification (Class I device considerations and typical 510(k) pathways), CE marking expectations, and the reimbursement reality that routine height measurement is typically embedded within bundled evaluation codes rather than reimbursed separately.
-
Supplier scorecards and comparative benchmarking — structured assessments across product breadth, clinical validation, digital integration, channel strength, and pricing strategy for fast due diligence.
-
Technology trend deep dives — digital stadiometers, touchless sonar and optical solutions, and integration scenarios with body composition analyzers and telehealth platforms.
-
M&A and partnership playbook — target profiles, valuation multipliers, and integration checklists that reflect the market’s concentration dynamics.
Competitive landscape — who matters and why
-
SECA GmbH & Co. KG (Hamburg, Germany): A broad portfolio across wall-mounted, portable and wireless digital models. SECA’s clinical legacy and product breadth make it a reference supplier for hospitals and clinical studies; its portable models are often cited in protocol standards.
-
DETECTO / Cardinal Scale (Webb City, Missouri, USA): Offers mechanical and digital lines as well as touchless sonar solutions; recent public references highlight ongoing product innovation in clinical height measurement.
-
Charder Medical (Taichung, Taiwan): A focused manufacturer in medical measurement equipment, supplying robust clinical and commercial-grade stadiometers.
-
Tanita Corporation (Tokyo, Japan): Leverages integration with body-composition analyzers, offering combined measurement workflows attractive to research and specialty clinics.
-
Marsden Weighing Group (Rotherham, UK): Known for medical-grade devices tailored to professional healthcare environments and strong NHS procurement relationships.
-
ADE (Hamburg, Germany) & Soehnle Professional (Backnang, Germany): European manufacturers with portfolios that emphasize reliability and clinical compliance.
-
Health O Meter (Hillrom/Baxter, Chicago, USA): Focuses on integrated clinical solutions and channel reach into larger health systems.
-
InBody Co., Ltd. (Seoul, South Korea): Differentiates via body-composition integration, targeting clinics and fitness channels that value multi-metric insights.
-
Shanti Engineering (Vadodara, India): Competitive on cost and exports, serving emerging market demand and institutional buyers.
These firms illustrate the competitive vectors that matter in 2026: product breadth vs. focused specialization, digital integration vs. mechanical reliability, and channel reach vs. regional manufacturing cost advantages. Our supplier scorecards and comparative matrices in the full report make it straightforward to prioritize partners, acquisition targets, or R&D investments depending on your strategic objective.
Regulatory and reimbursement realities — actionable levers
-
Device classification and compliance: Stadiometers used in clinical settings typically fall under Class I device frameworks and in many jurisdictions are subject to general controls (with available 510(k) exemptions in the U.S.). Understanding these pathways reduces time-to-market risk for incremental product upgrades.
-
Reimbursement pragmatics: Height measurement is commonly bundled into routine evaluation and management codes rather than reimbursed with a dedicated code. This reality makes the case for non-reimbursement-dependent value propositions: workflow efficiency, accuracy, infection-risk mitigation, and clinical validation.
-
Clinical standardization: Portable models referenced in clinical protocols underscore an opportunity—vendors that can validate accuracy to clinical research tolerances (e.g., millimeter precision) remove buyer objections and strengthen placement in study environments.
How to use this study across planning horizons (90 days → 12 months)
-
90 days: Run targeted supplier due diligence using our scorecards; pilot one digital/touchless device in a high-throughput outpatient clinic to validate workflow benefits against our ROI calculator.
-
6 months: Rework CapEx plans to phase out legacy mechanical units where payback < 36 months; negotiate pilot-to-deployment contracts with tier-1 vendors, leveraging volume and service commitments.
-
12 months: Execute M&A or strategic distribution partnerships informed by our target profiles and valuation guidance; integrate device data streams with EMR and body-composition platforms as a competitive differentiator.
Final note — what’s behind the preview
This briefing is designed as a tactical preview: it demonstrates the analytic depth and actionable frameworks contained in the full PW Consulting Worldwide Stadiometers Market report, while intentionally withholding the granular segment tables and proprietary model outputs that drive end-to-end strategy. The complete study contains the full regional, product, application and installation splits, supplier financial proxies, detailed scenario spreadsheets, and executable playbooks required to operationalize a 2026 strategy.
To access the complete dataset, supplier scorecards, and the interactive ROI models that underwrite our recommendations, request the full report through PW Consulting’s market research portal. For teams preparing 2026 procurement or investment plans, the timing to act is now: the market’s structural growth and shifting technology mix create measurable windows to capture share, improve margins, and secure clinical validation advantages before broader adoption accelerates.
For detailed analysis of this topic, please visit the official page: Worldwide Stadiometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MMA Film & Sheet Market Forecast to Expand at a 5.85% CAGR, Reaching USD 10,198.27 Million by 2032
By pmarketresearch, 2026-07-17
Worldwide MMA Film & Sheet Market — Strategic Outlook for 2026 Decision‑Makers
PW Consulting today releases an executive briefing drawn from our forthcoming Worldwide MMA Film & Sheet Market report (base year 2025, historical 2020–2025, forecast 2026–2032). The industry has transitioned from cyclical recovery to structural growth: total industry revenue rose from approximately USD 5.1 billion in 2020 to USD 6.85 billion in 2025 and is projected to exceed USD 10.2 billion by 2032, representing a compound annual growth rate (CAGR) of 5.85% across the 2026–2032 forecast window. For corporate leaders planning capital allocation, sourcing strategies, and product roadmaps in 2026, the intelligence in this report is designed to convert market signals into defensible, measurable actions.
Worldwide MMA Film & Sheet Market
Why 2026 is a strategic inflection point
Several concurrent forces — raw material volatility, regulatory tightening, trade policy shocks, and logistics instability — are compressing planning horizons and increasing the value of timely, high‑resolution market intelligence. The market’s steady medium‑term growth masks near‑term pockets of disruption that will determine winners and losers in the coming 12–36 months. Executives who align procurement, pricing and product investments before market share consolidation accelerates will capture disproportionate value.
Worldwide MMA Film & Sheet Market
- Market momentum: A multi‑year expansion trajectory offers runway for capacity investment and product innovation, but companies must reconcile long‑cycle build plans with shorter, more volatile input cost cycles.
- Concentration and competition: Market concentration is meaningful but not dominant — the top three suppliers account for roughly a third of global revenue, while the top five collectively approach half the market — creating space for agile incumbents and well‑capitalized challengers.
- Operational risk: Raw material disruptions, freight surcharges tied to geopolitical flashpoints, and punitive trade measures have materially increased execution risk for cross‑border supply chains.
What senior teams will find actionable in the full report
Our report is oriented to the practical needs of corporate strategy, commercial, procurement and M&A teams. It compresses complex industry dynamics into decision‑grade outputs without overloading on raw tables in this release. Highlights include:
Worldwide MMA Film & Sheet Market
- Scenario forecasts and high‑granularity demand curves that translate macro CAGR into realistic near‑term volume and price pathways for budget planning.
- A supplier intelligence module: production footprints, capacity trajectories, and commercial posture assessments for the industry’s leading players, enabling supplier segmentation and contracting strategy.
- Price and margin playbooks: rolling price decks, cost‑pass frameworks, and elasticity estimates that support contract negotiations and list‑price resets.
- Regulatory and compliance matrices: mapped to product families and applications, with a prioritized action list for certification, labelling and substitution risk mitigation.
- Investment and M&A scorecards: financial and strategic filters to identify value‑accretive bolt‑on targets and greenfield opportunities under multiple commodity and policy scenarios.
- Go‑to‑market blueprints: channel strategies, OEM engagement tactics, and product differentiation roadmaps for premiumization and sustainability‑led growth.
To honor the “trailer” principle of this release, detailed segment tables and the interactive dashboards that underpin these outputs are withheld here; they are available in the full report and on our client portal.
Key market dynamics shaping near‑term strategy
Three clusters of dynamics deserve particular attention for 2026 planning: supply‑side cost pressure, policy and trade action, and product lifecycle & sustainability trends.
- Supply‑side cost pressure: MMA monomer supply tightness translated into a notable spike in spot prices in late 2023, raising feedstock cost baselines and compressing margins for producers without integrated feedstocks. Ocean freight surcharges and episodic logistics bottlenecks have further raised landed costs and extended lead times for cross‑border supply chains.
- Policy and trade volatility: Regulatory regimes continue to tighten on additives and chemical components, increasing certification overhead for consumer‑facing applications. In addition, recent antidumping investigations and provisional duties introduced sharp trade‑policy asymmetries that favor regional sourcing and localization strategies.
- Product and sustainability dynamics: End users are accelerating displacement of legacy materials where higher optical performance, thinner gauge options, flame resistance or recycled content create value. Suppliers bringing differentiated grades — impact‑resistant, low‑VOC, or recycled‑content PMMA — are capturing higher ASPs and premium channel placements.
Collectively, these dynamics create a midcycle environment where portfolio pruning, supply‑chain rewiring and selective premiumization will determine margin trajectories more than top‑line growth alone.
Competitive landscape — strategic implications from observed moves
The competitive set blends global integrators and regional champions. PW Consulting’s strategic review of industry leaders surfaces three recurring playbooks: vertical integration to control feedstock exposure; premiumization through differentiated acrylic grades and film technologies; and localized capacity expansion to mitigate trade frictions.
- Röhm GmbH (Darmstadt, Germany) — A global reference in PLEXIGLAS® sheets and films. Recent pricing adjustments reflect a deliberate margin preservation strategy in an inflationary input environment. Strategic takeaway: pricing discipline and brand premium are key levers when feedstock markets are tight.
- Mitsubishi Chemical Group (Tokyo, Japan) — Capacity expansion activity signals a dual bet on sustainable grades and regional demand resilience. Strategic takeaway: expanding differentiated capacity ahead of demand inflection secures commercial leverage and OEM partnerships.
- Chi Mei Corporation (Tainan, Taiwan) — Product innovation, exemplified by new impact‑resistant grades, highlights a route to displace incumbent materials in higher‑value applications. Strategic takeaway: targeted grade launches can unlock cross‑segment share gains when supported by application engineering.
- LG Chem, Arkema, Plaskolite, Sumitomo and others — These players demonstrate a mix of integration, regional strength and product breadth. Collectively they underline a market architecture where no single axis (size, geography, or product breadth) guarantees sustained advantage; orchestration across commercialization, feedstock security and regulatory compliance is required.
Across the sector, the most successful operators are coupling R&D investment with commercial pilots and captive or hedged feedstock arrangements to translate product differentiation into defensible margin pools.
Actionable recommendations for executives preparing 2026 plans
- Rebaseline procurement: create a 12‑to‑24 month feedstock hedging and dual‑sourcing plan that is stress‑tested under high‑price and embargo scenarios.
- Prioritize product tiering: define premium grades and entry‑level SKUs with distinct margin and channel strategies; protect premium positions through specs, co‑development or long‑term OEM agreements.
- Localize selectively: use trade‑policy risk and freight‑cost mapping to decide where nearshore capacity or tolling partnerships are value‑creating versus opportunistic exports.
- Embed regulatory foresight: operationalize a regulatory compliance dashboard that tracks chemical restrictions, labelling requirements and end‑market audits to avoid last‑minute reformulations.
- Shape an M&A playbook: prioritize targets that provide feedstock synergies, access to differentiated grades, or rapid entry into underserved end markets; use our M&A scorecards to size payback under several price regimes.
- Invest in application engineering: allocate resources to convert material advantages into quantified lifecycle benefits for customers (weight reduction, optical performance, recyclability) and document TCO improvements.
- Design contingency logistics: secure alternative routing and inventory buffers for critical inbound flows; evaluate strategic inventory forward‑stocking in high‑risk lanes.
About the PW Consulting report — practicality and provenance
The full Worldwide MMA Film & Sheet Market report combines proprietary primary interviews, disaggregated shipment and pricing models, plant‑level capacity tracking and regional policy overlays to produce decision‑grade outputs. Methodological highlights include detailed supplier capacity maps, application‑level demand simulations, elasticities for price modelling, and a scored regulatory impact matrix. The report also includes an executive toolkit: interactive dashboards, downloadable datasets, and a playbook that translates analysis into prioritized initiatives for P&L and balance‑sheet owners.
In keeping with the briefing nature of this release, we have intentionally withheld granular segment tables and the full set of interactive exhibits. These materials are accessible through the report landing page and as part of our client briefing engagements.
How to engage
For corporate strategists, procurement leads, and private‑equity sponsors preparing 2026 budgets and transaction pipelines, this report provides the analytical foundation to convert uncertainty into competitive advantage. Access to the complete dataset, scenario modelling tools, and an option for a tailored executive briefing are available on PW Consulting’s report page. Our analysts stand ready to translate the findings into bespoke workshops that map the implications to your specific cost structure, product portfolio, and geographic footprint.
For detailed analysis of this topic, please visit the official page: Worldwide MMA Film & Sheet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MPPE Market Poised for 6.0% CAGR, New Report Finds
By pmarketresearch, 2026-07-17
Worldwide Modified Polyphenylene Ether (MPPE) Market: Strategic Imperatives for 2026 — PW Consulting Insights
As global manufacturers prepare strategic roadmaps for 2026, Modified Polyphenylene Ether (MPPE) is fast becoming a material of strategic importance across automotive electrification, advanced electrical & electronics, and select industrial and healthcare applications. PW Consulting’s latest Worldwide MPPE Market study — anchored on a detailed base year of 2025 and a seven-year forecast window (2026–2032) — synthesizes demand drivers, raw-material exposure, regulatory shifts, and competitive positioning to equip C-suite teams with the insights needed to make high-consequence product, capacity, and M&A choices next year.
Worldwide Modified Polyphenylene Ether (MPPE) Market
Market trajectory and what it means for 2026 decision-makers
Our analysis charts a steady expansion of the global MPPE market: from approximately USD 1.52 billion in 2020 to USD 2.04 billion in 2025, with a forecast runway to about USD 3.07 billion by 2032. The forecast period (2026–2032) is modeled with a compound annual growth rate (CAGR) of 6.0%, reflecting the combined pull of electrification, miniaturization and higher thermal/chemical performance demands in core end-use sectors.
Worldwide Modified Polyphenylene Ether (MPPE) Market
For executive teams, three implications follow:
Worldwide Modified Polyphenylene Ether (MPPE) Market
- Timing matters: incremental capacity and product investments made in 2026 will capture a market that is still consolidating around higher-performance grades and sustainability attributes.
- Margin preservation requires upstream visibility: feedstock volatility and regulatory compliance will determine whether value accrues to resin producers or shifts downstream to compounders and OEMs.
- Share gains are attainable, but selective: market concentration is material — the top three suppliers control a clear majority share, and the top five account for a substantial cluster of industry supply — suggesting that scale and technology differentiation remain powerful competitive levers.
What the report delivers — practical, deal-ready intelligence
Our report is designed as a near-operational playbook for strategy and corporate development teams. Key deliverables include:
- Top-down market sizing and a bottom-up demand model calibrated to macro scenarios (baseline, accelerated EV adoption, and slower industrial capex), with sensitivity analyses for raw-material shocks and tariff disruptions.
- Price-formation and margin models linking phenol and styrene price pathways to MPPE-grade economics, enabling decision-makers to stress-test pricing strategies and hedging approaches.
- Manufacturing and capacity maps, including utilization curves and lead-time risk scores, to inform greenfield vs. brownfield investment decisions and site selection under alternate trade-policy scenarios.
- Regulatory impact assessment covering REACH, regional flammability rules, and emerging chemical restrictions, plus reformulation roadmaps and compliance timelines.
- Commercial playbooks for route-to-market optimization — direct OEM engagement, tier-1 partnerships, and co-development models to capture design wins in electronics and automotive subsystems.
- Buy-side intelligence for M&A and joint ventures, including valuation multiples, synergy break-even timelines, and post-merger integration risk checklists.
Supply-side realities: feedstocks, tariffs and price volatility
Raw-material exposure is a defining risk for MPPE producers. During late 2024 market turbulence, phenol spot prices spiked and styrene monomer experienced notable upward pressure. These movements materially shift resin-makers’ cost curves and compress margins unless pricing and sourcing policies are adapted.
Beyond commodity swings, trade policy and regulation are immediately actionable concerns. Higher tariffs on select trade lanes have altered the economics of cross-border supply, while regional chemical restrictions — notably tightening controls on certain flame retardants — are already forcing reformulation and qualification programs in electrical applications. For 2026 planning, companies must explicitly model tariff-impacted flows and allocate R&D resources to compliant flame-retardant systems now, not later.
Competitive landscape — scale, specialization and the race for sustainable grades
The MPPE market exhibits significant consolidation: the top three producers account for a dominant share, and the top five consolidate an even larger portion of industry capacity. This structure rewards technology leadership, branded systems, and supply reliability.
Profiles of strategic incumbents spotlight divergent approaches:
- SABIC: A global leader with a branded PPE-based resin portfolio that emphasizes high heat resistance and flame retardancy. Recent product strategy highlights include a new grade incorporating recycled content, signaling a rapid pivot toward circularity in electronics housings.
- Asahi Kasei: Focused on low-dielectric and high-rigidity MPPE grades suited to connectors and electric-vehicle components; recent capacity expansion at a key plant underscores targeted bets on EV-related demand.
- Mitsubishi Gas Chemical: Concentrates on hydrolysis-resistant grades and performance across electrical insulation and industrial applications; maintains a product strategy anchored in specialty performance rather than commodity scale.
- Sumitomo Chemical: Emphasizes processability and impact strength for automotive under-hood and electronic housings, pursuing a blend of incremental polymer engineering and close OEM partnerships.
Recent market activity — sustainable-grade launches and capacity expansions — signals two concurrent trends: (1) incumbents are competing on decarbonization and circularity credentials as much as on pure performance; and (2) capacity moves are surgical, often tied to regional demand pockets (e.g., EV battery component supply chains).
Strategic priorities for 2026 — a short checklist for executives
Our recommendations are structured for immediate implementation during 2026 planning cycles:
- Secure feedstock flexibility: pursue multi-year contracts and regional supplier diversity for phenol and styrene, and build scenario models that quantify margin sensitivity to +/- 10–20% commodity swings.
- De-risk regulatory exposure: accelerate reformulation projects for REACH-compliant flame-retardant systems, and pre-qualify substitutes through accelerated aging and UL/IEC testing lanes.
- Invest selectively in sustainable grades: develop or license recycled-content and lower-carbon production routes where customers are willing to pay a premium, and create clear cost-pass-through playbooks.
- Optimize footprint against trade-policy realities: evaluate reshoring, nearshoring, or JV models to mitigate tariff drag and reduce lead times into high-growth OEM clusters.
- Pursue targeted M&A and alliances: given market concentration dynamics, tuck-ins that enhance specialty grade portfolios or regional fill-in capacity are likely to deliver faster payback than broad-scale bolt-ons.
- Commercialize system-level solutions: move up the value chain by offering compounder partnerships, design-in support, and validation kits for OEMs in EV and E&E applications to lock design wins early.
Risk register and mitigation — what to monitor quarterly
We recommend establishing a quarterly dashboard that tracks four leading indicators tied directly to MPPE economics:
- Feedstock forward curves (phenol, styrene) and margin-to-price ratios for flagship grades;
- Regulatory milestones and third-party test outcomes affecting flame retardant approval cycles;
- Capacity utilization and shipping lead times across key supply hubs, with stress flags for ports and logistics disruptions;
- OEM design schedules and commodity-spec changes that would shift resin demand profiles.
Why this report matters to private equity, strategy, and supply-chain teams in 2026
For private equity investors, the MPPE space presents buy-and-build opportunities where specialty grade differentiation and regional footprint arbitrage can yield attractive returns, provided buyers internalize reformulation costs and feedstock risks. For corporate strategy teams, the window for securing design wins in high-growth EV and electronics subsegments remains open but competitive — timing product introductions and capacity expansions for 2026 is critical. For supply-chain leaders, the immediate challenge is operationalizing hedging and contract frameworks that preserve margin through commodity cycles while ensuring timely delivery for OEM qualification timelines.
Next steps and how to access the full intelligence
This article outlines the strategic contours and actionable directions we believe will shape MPPE-related decisions in 2026. To preserve the commercial integrity of the detailed segmentation, price-path scenarios, and supplier-level financial models — which include granular regional, application and type-level insights essential to transaction and sourcing decisions — we have intentionally withheld those core tables and numerical splits from this summary.
For companies preparing to finalize budgets and capital allocations for 2026, the full PW Consulting MPPE report provides:
- Granular segmentation by region, type and application with forecasted volumes and revenues;
- Supplier scorecards with technology, capacity, and commercial terms;
- Custom scenario models that can be adapted to client-specific inputs for valuation or sourcing optimization.
Contact PW Consulting to request the full report and a tailored briefing. Our team will run a confidential workshop to overlay your product mix and supply-chain exposures on our modeled scenarios — helping you convert these market signals into implementable 2026 decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Modified Polyphenylene Ether (MPPE) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com