

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Insight: Worldwide Stadiometers Market to Top USD 203.3 Million by 2032

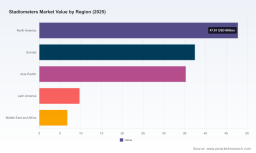
Worldwide Stadiometers Market — 2026 Strategic Preview
PW Consulting’s latest market study on Worldwide Stadiometers delivers a compact, practitioner's guide to the opportunity and competitive dynamics that will shape procurement, product strategy, and M&A activity in 2026. The market has shown steady expansion from an estimated US$105.12 million in 2020 to roughly US$137.0 million in 2025. Our forecast model places the market at approximately US$142.36 million in 2026 and projects growth to about US$203.3 million by 2032, reflecting a compound annual growth rate (CAGR) of 5.8% across the 2026–2032 forecast window. This briefing highlights the report’s strategic value for decision-makers while reserving the full segment-level data and models for the complete report.
Worldwide Stadiometers Market
Market trajectory and the near-term inflection points
-
Macro momentum: The market’s steady expansion is driven by a convergence of healthcare system modernization, standardized clinical workflows, and increasing demand for digital and touchless measurement modalities that improve throughput and infection-control protocols.
Worldwide Stadiometers Market -
2026 as a tactical year: With an estimated market size of ~US$142.36 million in 2026, organizations should treat the year as a tactical window to reposition portfolios, update procurement plans, and pilot product integrations that target clinical workflow efficiency.
Worldwide Stadiometers Market -
Moderate market concentration: Market concentration metrics indicate that the top three suppliers control a meaningful share of industry revenues, with the top five increasing that concentration further. This structure supports both strategic consolidation plays and opportunities for niche specialists to scale through partnerships or targeted product differentiation.
-
Volatility and scenario variance: Our scenario suite captures short-term cyclical effects related to hospital CapEx budgets, replacement cycles for mechanical units, and episodic demand spikes for touchless devices tied to public health priorities—factors that explain some year-to-year variance in our modeled forecasts.
Why this report matters for 2026 decisions
-
Procurement optimization: Hospital and health system procurement teams can use our timing models and CapEx guidance to phase replacements (mechanical → digital/touchless) in ways that maximize ROI and minimize disruption to clinical operations.
-
Product and R&D prioritization: Vendors should prioritize investments that accelerate digital integration (connectivity to EMR and body-composition platforms), reliability in high-throughput settings, and validated touchless measurement technologies—areas we model for adoption curves and margin impacts.
-
Channel and distribution strategy: For distributors and regionally focused players, the report maps buyer personas, decision drivers across clinical, school, and sports applications, and the channel economics that determine profitable service and lifecycle models.
-
Investor playbook: Private equity and strategic buyers will find our valuation overlays, consolidation scenarios, and supplier scorecards useful for rapid target screening in a market with mid-level concentration—ideal for roll-up strategies and bolt-on acquisitions that fill functional or regional gaps.
What the PW Consulting report contains — practical, executable content
-
Transparent market sizing & forecast methodology — year-by-year market estimates from 2020 through 2032 along with sensitivity runs and scenario assumptions.
-
Procurement and CapEx playbooks — hospital budget timing calendars, replacement triggers for mechanical units, and an ROI calculator that models cost-to-benefit for digital/touchless upgrades.
-
Buyer persona and application demand profiles — clinical, academic, and sports-sector use cases with buying criteria, procurement cycles, and service expectations (note: full application share tables are available in the complete report).
-
Regulatory and reimbursement matrix — concise checklists for FDA classification (Class I device considerations and typical 510(k) pathways), CE marking expectations, and the reimbursement reality that routine height measurement is typically embedded within bundled evaluation codes rather than reimbursed separately.
-
Supplier scorecards and comparative benchmarking — structured assessments across product breadth, clinical validation, digital integration, channel strength, and pricing strategy for fast due diligence.
-
Technology trend deep dives — digital stadiometers, touchless sonar and optical solutions, and integration scenarios with body composition analyzers and telehealth platforms.
-
M&A and partnership playbook — target profiles, valuation multipliers, and integration checklists that reflect the market’s concentration dynamics.
Competitive landscape — who matters and why
-
SECA GmbH & Co. KG (Hamburg, Germany): A broad portfolio across wall-mounted, portable and wireless digital models. SECA’s clinical legacy and product breadth make it a reference supplier for hospitals and clinical studies; its portable models are often cited in protocol standards.
-
DETECTO / Cardinal Scale (Webb City, Missouri, USA): Offers mechanical and digital lines as well as touchless sonar solutions; recent public references highlight ongoing product innovation in clinical height measurement.
-
Charder Medical (Taichung, Taiwan): A focused manufacturer in medical measurement equipment, supplying robust clinical and commercial-grade stadiometers.
-
Tanita Corporation (Tokyo, Japan): Leverages integration with body-composition analyzers, offering combined measurement workflows attractive to research and specialty clinics.
-
Marsden Weighing Group (Rotherham, UK): Known for medical-grade devices tailored to professional healthcare environments and strong NHS procurement relationships.
-
ADE (Hamburg, Germany) & Soehnle Professional (Backnang, Germany): European manufacturers with portfolios that emphasize reliability and clinical compliance.
-
Health O Meter (Hillrom/Baxter, Chicago, USA): Focuses on integrated clinical solutions and channel reach into larger health systems.
-
InBody Co., Ltd. (Seoul, South Korea): Differentiates via body-composition integration, targeting clinics and fitness channels that value multi-metric insights.
-
Shanti Engineering (Vadodara, India): Competitive on cost and exports, serving emerging market demand and institutional buyers.
These firms illustrate the competitive vectors that matter in 2026: product breadth vs. focused specialization, digital integration vs. mechanical reliability, and channel reach vs. regional manufacturing cost advantages. Our supplier scorecards and comparative matrices in the full report make it straightforward to prioritize partners, acquisition targets, or R&D investments depending on your strategic objective.
Regulatory and reimbursement realities — actionable levers
-
Device classification and compliance: Stadiometers used in clinical settings typically fall under Class I device frameworks and in many jurisdictions are subject to general controls (with available 510(k) exemptions in the U.S.). Understanding these pathways reduces time-to-market risk for incremental product upgrades.
-
Reimbursement pragmatics: Height measurement is commonly bundled into routine evaluation and management codes rather than reimbursed with a dedicated code. This reality makes the case for non-reimbursement-dependent value propositions: workflow efficiency, accuracy, infection-risk mitigation, and clinical validation.
-
Clinical standardization: Portable models referenced in clinical protocols underscore an opportunity—vendors that can validate accuracy to clinical research tolerances (e.g., millimeter precision) remove buyer objections and strengthen placement in study environments.
How to use this study across planning horizons (90 days → 12 months)
-
90 days: Run targeted supplier due diligence using our scorecards; pilot one digital/touchless device in a high-throughput outpatient clinic to validate workflow benefits against our ROI calculator.
-
6 months: Rework CapEx plans to phase out legacy mechanical units where payback < 36 months; negotiate pilot-to-deployment contracts with tier-1 vendors, leveraging volume and service commitments.
-
12 months: Execute M&A or strategic distribution partnerships informed by our target profiles and valuation guidance; integrate device data streams with EMR and body-composition platforms as a competitive differentiator.
Final note — what’s behind the preview
This briefing is designed as a tactical preview: it demonstrates the analytic depth and actionable frameworks contained in the full PW Consulting Worldwide Stadiometers Market report, while intentionally withholding the granular segment tables and proprietary model outputs that drive end-to-end strategy. The complete study contains the full regional, product, application and installation splits, supplier financial proxies, detailed scenario spreadsheets, and executable playbooks required to operationalize a 2026 strategy.
To access the complete dataset, supplier scorecards, and the interactive ROI models that underwrite our recommendations, request the full report through PW Consulting’s market research portal. For teams preparing 2026 procurement or investment plans, the timing to act is now: the market’s structural growth and shifting technology mix create measurable windows to capture share, improve margins, and secure clinical validation advantages before broader adoption accelerates.
For detailed analysis of this topic, please visit the official page: Worldwide Stadiometers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com