

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Traveler’s Diarrhea Treatment Market Set to Expand at 6.12% CAGR, New Report Reveals

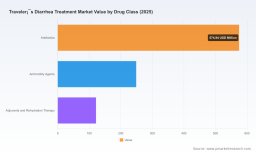
Worldwide Traveler’s Diarrhea Treatment Market: Strategic Preview for 2026 — What Leaders Must Know
Executive summary
PW Consulting’s latest market intelligence shows the Worldwide Traveler’s Diarrhea Treatment market as a resilient, mid-sized therapeutic category poised for steady expansion. After recovering through the early-2020s, the market reached an estimated USD 945.5 Million in 2025 and, under our base assumptions, is forecast to approach roughly USD 1.43 Billion by 2032 — representing a compound annual growth rate (CAGR) of approximately 6.12% across the 2026–2032 forecast window. The evolution of clinical prevention options, sustained demand for symptomatic care, and shifting distribution dynamics underpin this growth.
Worldwide Traveler¡¯s Diarrhea Treatment Market
Why this market matters for 2026 strategic planning
-
Acceleration point for pipeline entrants: The category is at a tactical inflection where late-stage vaccine programs and non-antibiotic biologics can materially alter product mix and competitive dynamics.
Worldwide Traveler¡¯s Diarrhea Treatment Market -
Commercial leverage through differentiated access: Premium pricing for targeted antibiotics in select markets coexists with broad OTC demand for symptomatic therapies, creating differentiated margin pools that influence local go-to-market choices.
Worldwide Traveler¡¯s Diarrhea Treatment Market -
Moderate concentration, meaningful opportunity: A handful of established global and regional players capture the majority of current revenues, yet the map of unmet prevention needs leaves room for new entrants and strategic partnerships.
What the PW Consulting report delivers (practical contents)
-
Robust market model: A transparent, scenario-enabled financial model covering 2020–2032 with base-year calibration to 2025, enabling what-if testing for pricing, launch timing, and reimbursement permutations.
-
Granular segmentation framework: Multi-dimensional segmentation by product class, distribution channel, and epidemiology — with adjustable levers for antibiotic vs. non-antibiotic adoption, OTC trends, and vaccine uptake. (Note: this press brief intentionally omits the detailed segment-level figures contained in the full report.)
-
Competitive intelligence dossier: Company profiles, product positioning maps, launch-readiness assessments, and commercial scorecards for leading incumbents and emerging developers.
-
Regulatory and payer landscape: Country-level policy monitors, reimbursement pathway assessments, and payer negotiation playbooks tuned for anti-infectives and prophylactic biologics.
-
Commercial playbooks and M&A screening: Prioritized strategic options for pharma, biotech, OTC brands, and specialty distributors — from licensing and co-promotion to bolt-on M&A and distribution partnerships.
-
Risk and sensitivity analyses: Epidemiology shocks, resistance trends, pricing pressure scenarios, and macro travel demand contingencies — all modeled to show downside and upside cases to 2032.
Competitive landscape: players, positions, and tactical implications
The market is anchored by established multispecialty and GI-focused firms that combine proprietary prescription antibiotics, OTC symptom relief, and supportive care solutions. Notable participants include developers of targeted non-absorbable antibiotics, major consumer health OTC brands, vaccine manufacturers, and companies developing biologic prophylactics. In concentration terms, the top three companies account for a significant share of the category’s revenues, and the top five capture a clear majority — creating a competitive environment where scale, channel reach, and regional regulatory expertise matter.
-
Bausch Health / Salix (Xifaxan/rifaximin) and other rifaximin proponents: Benefit from strong clinical positioning for noninvasive E. coli indications and sustained premium pricing structures in developed markets. Their strategy focus for 2026 should be lifecycle defense, patient access programs, and selective label extensions where clinical evidence supports expansion.
-
Cosmo Pharmaceuticals / Alfasigma and RedHill Biopharma (Aemcolo/rifamycin): Positioned as prescription alternatives with label-specific constraints (e.g., limitations for febrile or bloody presentations). Commercial playbooks should emphasize targeted physician education, diagnostic stewardship, and payer contracting to defend on-label use.
-
Consumer healthcare majors (Kenvue/Imodium, Procter & Gamble/Pepto-Bismol): Continue to capture symptomatic and prophylactic self-care demand. Their priorities are front-line availability, OTC marketing in travel channels, and digital consumer engagement to convert prophylactic interest into purchases.
-
Large pharma suppliers of broad-spectrum antibiotics (e.g., Pfizer): Remain relevant through off-label or empiric use patterns in regions where clinical practice favours macrolides or other agents for specific traveler cohorts. Strategic stewardship and alignment with local guideline committees are essential risk mitigation steps.
-
Biologic and vaccine developers (Immuron, Valneva, Scandinavian Biopharma): Represent the key disruptive vector. Immuron’s colostrum-based prophylactic approach and Valneva’s Dukoral vaccine (with cross-protection potential against LT-producing ETEC) exemplify non-antibiotic prevention strategies likely to shift long-term demand if uptake accelerates. Recent Phase 2b ETVAX data — demonstrating sizable reductions in ETEC-triggered diarrhea and regulatory readiness signals towards Phase 3 — elevates vaccine-led prevention from theoretical to investment-grade consideration.
Recent clinical and regulatory catalysts — implications for 2026
-
EVTAX vaccine advancement (Phase 2b positive data; Phase 3 readiness): The emergence of robust vaccine efficacy data converts prevention into a nearer-term commercial proposition. For manufacturers and investors, this implies planning for new distribution models (vaccination at travel clinics, pharmacies), cold-chain considerations, and economic evaluations that compare vaccination cost to acute treatment pathways.
-
Product approvals and labels remain decisive: Affirmations of label scope for rifaximin and rifamycin derivatives shape prescribing behaviour and payer coverage. Firms must craft evidence-generation strategies (real-world outcomes, health economic dossiers) that align with local reimbursement criteria.
-
OTC prophylactics and biologics: Non-antibiotic options that avoid antimicrobial resistance concerns will attract regulatory and public health attention — creating both opportunity and additional scrutiny on claims and manufacturing transparency.
Strategic implications & recommended actions for stakeholders in 2026
-
Pharmaceutical & biotech companies: Prioritise balanced portfolios that pair symptomatic/OTC offerings with defensive stewardship of prescription antibiotics. Accelerate partnerships with vaccine developers or consider in-licensing prophylactic biologics to capture upstream prevention value.
-
Commercial teams & distributors: Re-evaluate channel mixes with an emphasis on expanding digital and travel-related touchpoints (online pharmacies, travel clinics, airline/airport retail). Develop bundled offerings (pre-travel kits) that combine prophylaxis, symptomatic care, and education to increase average basket value.
-
Investors & M&A teams: Screen for assets that meaningfully shift the prevention-treatment balance — late-stage vaccines, biologics with scalable manufacturing, or OTC brands with strong travel-market penetration. Use our scenario model to price launches under multiple uptake and price-resistance assumptions.
-
Payers & health systems: Prepare HTA frameworks to evaluate prevention versus episodic treatment economics, considering both direct and indirect cost offsets from reduced traveler morbidity and travel-disruption costs.
-
Public health & guideline developers: Incorporate emerging vaccine evidence into travel medicine recommendations, and coordinate stewardship messaging that balances effective traveler protection with antimicrobial resistance mitigation.
Where the report exercises discretion — and why
In line with PW Consulting’s “trailer” approach to public releases, this brief highlights market-scale trajectories, high-consequence innovations, and strategic implications while intentionally withholding detailed sub-segment numbers (by region, drug class splits, and channel revenues) to preserve the actionable value of the full report. The comprehensive report includes the detailed, auditable segmentation that enables transaction diligence, launch planning, and payer negotiation — the very information that strategic buyers and licensing partners rely upon.
Next steps for decision-makers
-
Download the full PW Consulting report to access the complete segmentation matrices, ‘buy versus build’ M&A scorecards, and the scenario-enabled financial model calibrated to 2025 actuals.
-
Book a strategy briefing: PW Consulting offers bespoke deep-dive sessions that stress-test your 2026 commercial and R&D plans against vaccine-adoption and stewardship scenarios.
-
Engage with our market-entry playbook if you are evaluating in-licensing, regional partnerships, or an expanded OTC portfolio aimed at the travel channel — we can tailor the playbook to your asset and target geographies.
Closing perspective
The traveler’s diarrhea treatment market in 2026 is actionable: steady topline growth, clear pockets of premium pricing, and a near-term disruption vector from prevention technologies. For corporate strategists, the imperative is threefold — protect core prescription revenue through evidence and access tactics; invest selectively in prevention and non-antibiotic prophylactics; and restructure commercial routes to capture higher-value travel and digital channels. PW Consulting’s full report furnishes the detailed, executable intelligence required to translate these imperatives into tangible 12–36 month plans.
To access the full intelligence package and schedule a strategic briefing, please visit our report page.
For detailed analysis of this topic, please visit the official page: Worldwide Traveler¡¯s Diarrhea Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com