

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide High Flow Ventilator Market to Grow at 9.25% CAGR, Reaching USD 2,136.21 Million by 2032

Worldwide High Flow Ventilator Market 2026: Strategic Imperatives from PW Consulting’s New Market Intelligence Brief
PW Consulting today publishes an executive market brief synthesizing our proprietary analysis of the worldwide high flow ventilator market. Designed as a strategic planning tool for senior executives, investors, and health-system procurement leaders, this briefing crystallizes the market dynamics that will shape capital allocation, product roadmaps, and M&A choices through 2026 and beyond.
Worldwide High Flow Ventilator Market
Why this market matters in 2026
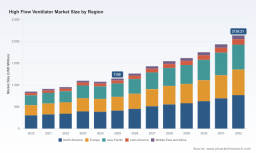
High flow oxygen therapy has moved from a niche adjunct to a core modality in acute and subacute respiratory care. Our sizing work shows the global market expanding from a base of approximately USD 1,150 Million in 2025 to an estimated USD 2,136 Million by 2032, implying a compound annual growth rate of 9.25% over the forecast horizon (2026–2032). That growth is being driven by convergent forces: persistent demand for non‑invasive respiratory support across care settings, heightened hospital procurement to reduce intubation rates and length of stay, and vendor innovation that compresses clinical workflows and lifecycle costs.
Worldwide High Flow Ventilator Market
Report structure and practical outputs
The full PW Consulting report is built as an operational playbook for 2026 decision-making. Key deliverables include:
Worldwide High Flow Ventilator Market
- Market sizing and consensus-aligned forecast (base year 2025; historical series 2020–2025; forecast period 2026–2032) with scenario sensitivity for demand shocks and adoption curves.
- Competitive intelligence dossiers covering product portfolios, regulatory footprints, distribution strategies, and differentiated capabilities for leading suppliers.
- Regulatory and reimbursement mapping that ties device classification and 510(k) dynamics to go‑to‑market timing and evidence-generation strategies.
- Commercial playbooks segmented by buyer archetype (acute care buyers, ambulatory center purchasers, and homecare programs) with procurement negotiation levers, TCO templates, and service model options.
- Technology and clinical trend analysis (including single‑circuit disposables, heated humidification advances, and integration of high flow capability into multifunction ventilators) and implications for product roadmaps.
- Supply‑chain and manufacturing risk assessment, including component concentration and ramp strategies for rapid scale-up in pandemic-resurgence scenarios.
- Investment and M&A scoring, with prioritization frameworks for bolt-on acquisitions, strategic partnerships, and cross‑licensing opportunities.
- An interactive dataset and financial model (Excel) that allows users to run custom scenarios and extract the granular tables referenced in our executive narrative.
Competitive landscape — what we distilled
The high flow ventilator arena displays a moderate-to-high degree of concentration. Our CR3 sits just above fifty percent and the top five suppliers collectively command approaching three quarters of the market, indicating meaningful barriers to entry but also space for focused challengers with differentiated propositions.
Several archetypes of competitors are shaping the market:
- Large, diversified ventilator OEMs that bundle high flow capability into broader critical care platforms (examples include multinational medical technology groups). Their advantages are integrated clinical workflows, installed base servicing, and cross-selling into ICU suites.
- Specialist high flow innovators who lead in modality-specific engineering and clinician adoption (companies with legacy HFNC/HVT product lines). These firms often set clinical practice norms and drive disposable accessory ecosystems.
- Emerging challengers and medtech entrants that emphasize cost-effective ventilation platforms or single-circuit disposables tailored for multi‑population use in neonatal, pediatric, and adult patients.
Notable company-level observations from our competitive audit:
- Fisher & Paykel Healthcare retains a leadership position via product depth in nasal high flow systems and strong clinical preference in several markets. Their heated humidification expertise remains a high barrier for newcomers looking to match physiologic performance.
- Vapotherm’s focus on high velocity nasal insufflation and recent regulatory progress strengthens its clinical footprint. Their product architecture and disposable strategy create high switching costs where adoption is established.
- Large ventilator manufacturers (including players such as Hamilton Medical, Dräger, Philips, Medtronic, Getinge, and others) are increasingly embedding high flow modes into intelligent ventilator platforms — a strategy that leverages installed base relationships and service contracts to accelerate adoption in critical care environments.
- Regional OEMs and new entrants (for example, firms expanding from adjacent respiratory device segments) are targeting price-sensitive channels and homecare, applying lean manufacturing and remote monitoring to capture share.
Regulatory, reimbursement and procurement dynamics
Regulation and reimbursement are no longer background considerations — they are core components of commercial strategy. High flow devices are regulated in the United States as Class II devices under the relevant CFR code and commonly require 510(k) clearance to market. Recent approvals have emphasized single‑circuit disposables and multi‑population claims, which compress clinical training needs and can materially alter procurement preferences.
On reimbursement, ventilators with multi‑function capabilities commonly fall under frequently and substantially serviced payment categories for home use; specific HCPCS codes and monthly rental models materially affect the economics of homecare expansion. From a hospital CAPEX perspective, acquisition costs for hospital‑grade high flow systems remain several times higher than low‑flow oxygen setups, but procurement committees increasingly consider total cost of care — reductions in ICU days and intubation rates can justify larger purchases when supported by robust clinical and economic evidence.
Recent developments that alter the 2026 playbook
- Regulatory milestones continue to reframe addressable markets. For example, Vapotherm secured FDA 510(k) clearance in 2026 for a single disposable All Patient Circuit that spans neonatal through adult patient groups — a clear commercial accelerant for sites seeking inventory simplification and workflow uniformity.
- OEMs from high-growth regions have advanced U.S. clearances in recent years, broadening competitive pressure across price and service dimensions and expanding choice for large health systems.
- New product entrants designed for cost-efficient critical care ventilation (cleared in recent years) highlight a persistent opportunity for value-oriented platforms in regional and resource-constrained settings.
Strategic implications and recommended actions for 2026
For corporate executives and health‑system leaders planning in 2026, PW Consulting highlights five pragmatic strategic levers:
- Prioritize clinical-evidence investments that map directly to procurement KPIs. Sponsor randomized or real-world studies that demonstrate intubation avoidance and LOS reductions — these outcomes are decisive in hospital CAPEX committees and reimbursement modeling.
- Rationalize portfolio architecture around clinician workflow simplification. Single‑circuit disposables and multi‑population claims materially shorten training and inventory cycles; product roadmaps should prioritize such features where technically feasible.
- Align regulatory pathways and launch sequencing with reimbursement strategy. Obtain indications and payment codes that unlock rental and homecare economics early in product commercialization to maximize uptake.
- Adopt hybrid commercial models that combine service contracts, managed equipment services, and outcome-based pricing pilots. This mitigates purchasing cyclicality and differentiates offerings in tender processes.
- Evaluate M&A and partnership opportunities to shore up consumables ecosystems or to buy clinical evidence and distribution capabilities. Given the market’s concentration, targeted bolt-on acquisitions can be an effective route to scale quickly without having to displace entrenched incumbents directly.
How to use the PW Consulting deliverable
The brief we release today is a director‑level synthesis intended to orient strategy discussions and prioritize near-term decisions. The full report contains the granular datasets, supplier scorecards, clinical trial matrices, and an interactive financial model that together enable:
- Custom modeling of regional demand scenarios and price elasticity assumptions;
- Vendor due diligence checklists and integration playbooks for M&A; and
- Procurement negotiation templates that quantify lifecycle cost trade-offs between platform purchase and bundled service models.
To preserve the integrity of our competitive analysis and to drive direct engagement, the full subsegment tables and company-level revenue splits are accessible only through the complete report on our site. This “trailer” approach gives decision-makers a rigorous preview while ensuring the actionable inputs required for bidding, capital planning, and product strategy are delivered as part of the full intelligence package.
Final assessment
2026 is a decisive year for stakeholders in the high flow ventilator market. Growth trajectories and clinical imperatives make this category a strategic frontier for medtech R&D and health system modernization. Market expansion is substantial, evidenced by robust CAGR and a doubling‑plus market value through the forecast period, and the competitive dynamics — characterized by a concentrated top tier and nimble challengers — reward clarity of strategy, speed of evidence generation, and operational excellence in supply chain execution.
PW Consulting’s Worldwide High Flow Ventilator Market report translates this complexity into executable strategies. For executives preparing 2026 budgets, pursuing M&A, or building go‑to‑market plans, the full report is designed to be the single source of truth that balances rigorous data with pragmatic recommendations.
Access details and executive summaries are available on the PW Consulting web portal. For tailored briefings, scenario workshops, or bespoke due diligence engagements, contact our Respiratory Devices practice team.
For detailed analysis of this topic, please visit the official page: Worldwide High Flow Ventilator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com