

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Predicts 10.49% CAGR from 2026–2032 for Worldwide Aircraft AFP and ATL Composites Market

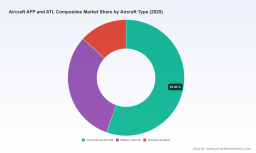
Worldwide Aircraft AFP and ATL Composites Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on Worldwide Aircraft Automated Fiber Placement (AFP) and Automated Tape Laying (ATL) Composites evaluates the commercial dynamics, technology trajectories, competitive positions and strategic levers that will shape capital and M&A decisions through 2026 and beyond. Anchored on a 2025 base year and a 2026–2032 forecast window, the report quantifies a clear growth runway — an industry compound annual growth rate of 10.49% — and delivers practical, action-oriented frameworks that procurement, operations and corporate strategy teams can deploy immediately.
Worldwide Aircraft AFP and ATL Composites Market
Why this matters for 2026 planning
-
Capital timing: With the consolidated market momentum visible at the 2025 baseline and a strong mid‑single‑to‑double‑digit growth trajectory into 2032, 2026 represents an inflection year for capacity investments, technology refreshes and automation rollouts.
Worldwide Aircraft AFP and ATL Composites Market -
Risk calibration: Recent regulatory and export-control developments, combined with material and labor cost pressures, are changing the calculus for where and how to deploy AFP/ATL assets and which partners to favor.
Worldwide Aircraft AFP and ATL Composites Market -
Competitive positioning: The market demonstrates meaningful concentration — the leading suppliers capture the majority of market value — creating both barriers and opportunities for targeted entrants, component suppliers and Tier‑1 integrators.
Macro snapshot (what the numbers tell us)
From 2020 through 2025 the market expanded steadily, establishing a robust 2025 base. PW Consulting’s forecast shows the industry nearly doubling over the 2026–2032 horizon, driven by accelerated aircraft production, expanded composite content on new platforms, and continued automation adoption across fuselage, wing and empennage programs. At a 10.49% CAGR, executives should expect both predictable demand growth and episodic volatility tied to program timing, raw material cycles and policy shifts.
Core strategic implications
-
Prioritize flexible automation: AFP and ATL investments should emphasize modularity and multi‑tape/multi‑tow capabilities to support mixed fleets and evolving layup strategies. Flexibility reduces stranded‑asset risk when platform mix or certification requirements change.
-
Localize critical supply chains selectively: Export controls and national security classifications are creating geographic constraints on machinery transfers and technology flows. Commercial planning must integrate export‑control screening and onshoring options into supplier selection and CapEx scenarios.
-
Balance CapEx with services: Given concentration among a few global vendors and the premium for specialist integration expertise, consider hybrid models that combine equipment purchases with long‑term services, performance guarantees and spares agreements.
-
Use automation to offset labor gaps: With skilled labor costs rising and worker shortages persisting, AFP/ATL adoption should be framed as a labor substitution plus qualifications upgrade strategy — reducing routine headcount while increasing demand for advanced technicians and systems engineers.
-
M&A and partnerships: The current competitive structure favors consolidation and strategic alliances. Buyers should target bolt‑on technologies that reduce cycle time, increase yield or unlock thermoplastic processing, while sellers should position on recurring revenue and serviceable installed base growth.
What our report delivers — the practical toolkit
This study is structured to be operationally useful for 2026 decision cycles. Highlights include:
-
Top‑line market sizing and a seven‑year forecast (2026–2032) with scenario alternatives that stress test demand against program deferrals and raw material inflation.
-
Technology roadmaps for AFP and ATL — maturity curves, throughput benchmarks, and certification timelines that translate process capability into production capacity plans.
-
Supplier benchmarking and strategic heatmaps that go beyond brand names to quantify installed base dynamics, service footprints and go‑to‑market models.
-
Investment playbooks: CapEx calculators, break‑even analyses, and ROI thresholds tailored for Tier‑1, OEM and large Tier‑2 operations.
-
Regulatory & compliance playbooks: Practical checklists for certification readiness (including FAA expectations around AFP process controls), and a mapped set of export‑control implications for cross‑border equipment flows.
-
M&A screening matrices and integration trackers that operationalize successful bolt‑ons and technology transfers while mitigating IP and export risks.
-
Interactive scenario dashboards (available in the full report) to model sensitivity to carbon‑fiber costs, labor inflation, and production backlog shifts.
Competitive landscape: who matters and why
The market is shaped around a small set of specialized equipment and integration providers. PW Consulting’s analysis profiles these players not just by product, but by installed base, strategic customers and recent momentum — a necessary vantage for procurement and corporate development teams.
-
Electroimpact Inc. (Mukilteo, WA, USA) — Recognized for large‑scale AFP systems used on primary structures for wide‑body programs. Their delivery track record on composite wings and fuselage components positions them as a partner for very high‑volume production and complex envelope work.
-
MTorres Group (Pamplona, Spain) — Offers both ATL and AFP platforms, with program references across narrow‑ and wide‑body programs. Their dual‑technology portfolio is attractive for OEMs managing mixed layup strategies.
-
Coriolis Composites (Quévert, France) — Specializes in multi‑tow, articulated AFP robotics suited to intricate geometries and high‑precision applications. Their focus on advanced end‑effectors and software integration makes them a prime candidate for performance‑driven upgrades.
-
Mikrosam (Prilep, North Macedonia) — A modular, cost‑competitive supplier with growing presence in thermoplastic systems and nacelle/engine component automation. Their modular approach supports geographically distributed manufacturing models.
-
Accudyne Aerospace (Independence, KS, USA) — With heritage equipment and a strong footprint in large panel manufacturing, Accudyne is a go‑to for integrators aiming to scale panel throughput with proven ATL/AFP variants.
Recent market cues underscore the pace of innovation and deployment: new AFP/ATL demonstrations at major trade shows in 2024, high‑profile deliveries in late 2023, and continued product launches that collectively suggest vendors are racing to capture program content and installed‑base services.
Key dynamics and near‑term risks
-
Raw materials: Aerospace carbon fiber demand rose sharply in 2023; feedstock volatility can materially alter unit economics for composite layup and must be modeled explicitly in 2026 budgets.
-
Backlog-driven investment: A multi‑year commercial aircraft backlog continues to be a primary demand driver for AFP/ATL automation — but program schedule slips change the timing of returns and impact supplier capacity planning.
-
Regulation & certification: Recent amendments emphasizing AFP process controls mean certification costs and lead times are increasing; procurement should insist on supplier capabilities around traceability, process control and auditability.
-
Export controls: Machinery classified under certain export control codes now faces transfer constraints. Strategic players are evaluating dual‑source strategies, domestic production lines, or licensing agreements to maintain program continuity.
-
Labor costs & skills: Rising labor costs and a constrained skilled workforce accelerate the business case for automation but raise the bar for implementation timeframes and training investments.
How to use this study in your 2026 playbook
-
Board level: Use the report’s scenario dashboards to stress test CapEx proposals against downside program deferrals and to set funding thresholds tied to specific throughput and yield improvements.
-
Operations & manufacturing: Apply the process maturity and throughput benchmarks to validate supplier proposals, optimize line balance, and develop a staged deployment plan that prioritizes early returns.
-
Corporate development: Leverage the supplier scorecards and concentration analysis to identify consolidation targets, tech tuck‑ins and service monetization opportunities.
-
Procurement & compliance: Integrate the export‑control heatmaps and certification checklists into RFPs and supplier contracts to reduce delivery and regulatory risk.
Closing — the strategic premium of insight
AFP and ATL technologies are no longer niche process improvements; they are strategic enablers that determine program competitiveness, unit cost curves and factory footprint. Our 2025‑base market sizing and 2026–2032 forecast quantify a compelling growth path, but the real advantage for 2026 decision‑makers lies in operationalizing that insight: timing investments, structuring supplier relationships, and executing M&A with a clear view of installed‑base economics and regulatory constraints.
PW Consulting’s full report delivers the granular tables, segment‑level forecasts, interactive models and supplier scorecards that executives and program leads need to convert these strategic imperatives into action. For access to the complete dataset, downloadable dashboards and implementation templates, visit PW Consulting’s market research portal to request the Worldwide Aircraft AFP and ATL Composites Market report and supporting materials.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft AFP and ATL Composites Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com