

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Radiation Dose Optimisation Software Market to More Than Double — From USD 435.5 Million in 2025 to USD 917.37 Million by 2032 at an 11.23% CAGR

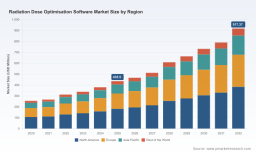
Worldwide Radiation Dose Optimisation Software Market — Strategic Briefing for 2026
PW Consulting’s latest market study on the Worldwide Radiation Dose Optimisation Software market provides a focused, decision-grade perspective designed to inform executive action in 2026. Anchored on a 2025 base year and a comprehensive historical review (2020–2025), the report projects the market through 2032. At the macro level, the market is expected to sustain robust expansion — growing from a global market size of USD 435.5 Million in 2025 toward a substantially larger opportunity by 2032, reflecting a compounded annual growth rate (CAGR) of 11.23% across the 2026–2032 forecast period. This briefing summarizes the strategic implications, competitive dynamics, regulatory and technology catalysts, and the practical deliverables contained in the full report — while reserving the detailed segment- and region-level tables for the full report download.
Worldwide Radiation Dose Optimisation Software Market
Why this brief matters for 2026 corporate decisions
-
Time-sensitive strategic moves: 2026 will be a pivotal execution year for vendors and healthcare providers as buyers shift from pilot projects to enterprise-wide deployments. The pace of adoption and the sustained CAGR imply that first-mover advantage in scalable, enterprise-grade offerings will translate into outsized commercial returns.
Worldwide Radiation Dose Optimisation Software Market -
Portfolio and product planning: Vendors must prioritize regulatory clearances, AI validation, and multi-modality interoperability now to capture share in the high-growth window. Equally, hospital systems should formalize procurement roadmaps to capture clinical and operational ROI from dose optimisation tools.
Worldwide Radiation Dose Optimisation Software Market -
Investment and M&A timing: The market’s structure and growth profile create predictable windows for bolt-on acquisitions (to close capability gaps) and for late-stage investments that de-risk technology and regulatory pathways before scaling.
Market dynamics: drivers, regulation, and technology
The industry is being shaped by three reinforcing dynamics. First, regulatory and accreditation pressure is accelerating adoption: by 2024, approximately 78% of U.S. hospitals had implemented AI-powered dose management systems in response to imaging safety standards, underscoring a shift from discretionary to compliance-driven purchasing. Parallel regulatory activity continues: 510(k) clearances for advanced dosimetry software and harmonized requirements under EU MDR for patient-specific dosimetry are converging to raise market entry bars but also to expand clinical use-cases.
Second, innovation in AI and image-reconstruction is delivering material clinical benefits. Recent clinical syntheses indicate that AI-driven reconstruction and denoising algorithms can deliver clinically meaningful radiation reductions across CT applications — often in the range of tens of percentage points — while preserving diagnostic quality. These capability gains are meaningful competitive differentiators and are reshaping value metrics buyers use to assess suppliers.
Third, modality proliferation (CT, fluoroscopy/interventional suites, mammography, radiography, and targeted radionuclide therapies) and the move toward enterprise imaging strategies are increasing demand for solutions that handle multi-vendor environments and aggregate dose data for population health, patient-specific planning, and regulatory reporting.
Market structure and implications
The market shows evidence of moderate concentration: the top three vendors account for a significant portion of total revenue, and the top five increase that share materially. This concentration (CR3 ~42.5%; CR5 ~61.2%) suggests a competitive landscape where leading global incumbents command advantages in enterprise sales, regulatory credentials, and installed base integration, while specialist and regional vendors compete on niche capabilities, rapid innovation, and service-led business models.
For strategists this means two concurrent approaches are rational: (1) incumbents should double down on enterprise features, certification, and channel partnerships to protect and grow their installed base; (2) challengers and pure-play innovators should emphasize clinical evidence, speed-to-integration, and targeted regulatory clearances where they can create defensible niches.
Competitive landscape — who to watch
The market is populated by a mix of multinational imaging OEMs, enterprise imaging vendors, and specialized software innovators. Key players examined in the report include global OEMs and specialists that differ by go-to-market, product scope, and clinical focus:
-
GE HealthCare — Offers DoseWatch, an enterprise-capable dose management and optimisation platform with multi-vendor monitoring, real-time alerts, and protocol optimisation modules suited for large health systems.
-
Siemens Healthineers — Provides teamplay Dose, a solution that aggregates dose data across modalities and supports quality assurance and compliance workflows for enterprise imaging programs.
-
Bayer AG — Through its radiation safety offerings, delivers personalized radiation and contrast dose management tools with emphasis on workflow integration and compliance reporting.
-
Koninklijke Philips N.V. — Integrates DoseWise Portal and related modules into diagnostic and interventional imaging suites, focusing on automated dose tracking and regulatory reporting.
-
Sectra AB — Offers web-based DoseTrack for automatic collection, storage and monitoring of dose data, emphasizing ease of deployment and reporting.
-
Qaelum N.V. — A specialist in flexible, multi-facility dose monitoring solutions designed for heterogeneous imaging estates.
-
FUJIFILM and Canon Medical Systems — Both integrate dose tracking and protocol optimisation within broader imaging portfolios, targeting customers that prefer vendor-aligned ecosystems.
-
Regional and specialist players — PACSHealth, Medsquare, DOSIsoft, INFINITT, and other innovators provide focused capabilities such as patient-specific dosimetry, radionuclide therapy planning, and modular dose tracking for research and specialty clinics.
Notable recent regulatory and product developments reinforce the speed of innovation: in March 2025, DOSIsoft’s PLANET Onco Dose secured a 510(k) clearance extension for expanded radionuclide therapy dose computation capabilities, and in September 2025 an AI-powered dose prediction solution (Dose+) received FDA 510(k) clearance for clinical use in the U.S. These events illustrate dual trends — specialization in targeted radionuclide dosimetry, and fast-moving AI entrants that are moving through regulatory gates.
What the full report delivers — operational content for 2026
The PW Consulting report is designed for immediate operational use by executives, product teams, procurement officers, and investment professionals. Key deliverables include:
-
Robust market-sizing and forecast model (USD Million), with sensitivity scenarios and CAGR validation across 2026–2032.
-
Vendor scorecards that assess technology maturity, regulatory status, clinical evidence, interoperability, and commercial model (license vs. SaaS vs. services).
-
Buyers’ decision frameworks and procurement checklists — including integration templates for enterprise imaging, data flow maps, and clinical validation study requirements.
-
Deal playbooks for investors and M&A teams: target prioritization, valuation comparables, and regulatory risk matrices.
-
Clinical and operational ROI templates that translate dose reductions and workflow efficiencies into financial and compliance metrics tailored to hospital and imaging centre buyers.
-
Regulatory tracker and certification pathroadmaps for FDA, EU MDR and relevant national bodies, plus an action plan for securing 510(k)/CE Mark where applicable.
-
Use-case vignettes and implementation timelines for enterprise rollouts, including pilot-to-scale staging and KPIs to govern success.
To preserve the report’s role as the authoritative source, the public briefing highlights the nature and utility of these deliverables without reproducing the full tables and granular segment splits; purchasers of the full report gain access to the complete datasets, regional and application breakdowns, and vendor benchmarking matrices.
Actionable recommendations for stakeholders in 2026
-
Vendors: Prioritize regulatory strategies (510(k)/CE) for differentiated capabilities (AI-driven denoising, radionuclide dosimetry), expand SaaS-native delivery for recurring revenue, and invest in enterprise interoperability and API-first architectures.
-
Healthcare providers / CIOs: Formalize enterprise dose governance, mandate vendor-neutral data aggregation, and include dose management KPIs in imaging service contracts. Run head-to-head pilots that measure clinical efficacy, workflow impact, and TCO (total cost of ownership).
-
Investors / M&A teams: Target specialists with validated clinical outcomes or cleared regulatory pathways, and prioritize assets that de-risk enterprise integration (e.g., vendor-agnostic middleware, patient-specific dosimetry for radionuclide therapies).
-
Regulators and policy-makers: Support harmonized guidance for AI validation and create clear performance endpoints for dose optimisation tools to accelerate safe adoption.
How to use the report to inform your 2026 playbook
The full PW Consulting report transforms high-level trends into executable plans: operational scorecards inform product roadmaps; the regulatory tracker accelerates clearance strategies; and the financial models quantify investment timing. For teams preparing budgets, negotiating vendor agreements, or scouting acquisition targets, the report supplies both the “what” (demand drivers, growth vectors) and the “how” (checklists, templates, vendor benchmarks) required to act decisively in 2026.
If your organization needs targeted briefings — for example, a vendor short-list for a multi-hospital roll-out, a regulatory readiness gap analysis, or an investor diligence pack — PW Consulting offers bespoke workstreams that leverage the report’s underlying models and primary research to produce tailored recommendations and deliverables.
To access the full dataset, regional and application breakdowns, and the vendor benchmarking matrices that underpin these strategic recommendations, please visit PW Consulting’s report page for the Worldwide Radiation Dose Optimisation Software Market or contact our advisory team for a private briefing and procurement toolkit.
For detailed analysis of this topic, please visit the official page: Worldwide Radiation Dose Optimisation Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com