

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Bipolar Plate Fuel Cell Market to Surge from USD 1,933.55 Million in 2025 to USD 9,219.88 Million by 2032 at a 25.04% CAGR

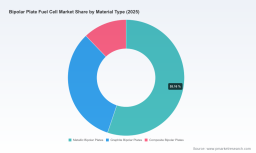
Worldwide Bipolar Plate Fuel Cell Market — Strategic Outlook for 2026
PW Consulting’s new market study, “Worldwide Bipolar Plate Fuel Cell Market,” provides a focused, decision-ready perspective for executives and investors planning capital allocation, product strategies, and partnerships in 2026. Built on a 2025 base year and grounded in a 2020–2025 historical dataset, the study projects the market through 2032 and models the structural forces shaping material choices, manufacturing scale-up, and customer adoption curves. This release highlights the macro trajectory and strategic imperatives revealed in our analysis while withholding detailed regional and application splits to encourage access to the full report.
Worldwide Bipolar Plate Fuel Cell Market
Market Snapshot: Rapid Expansion, Structural Inflection
The bipolar plate market is experiencing an accelerated adoption phase. After steady growth through the early 2020s, the market surged in the 2023–2025 period and reached USD 1,933.55 Million (revenue unit: Million USD) in 2025. Our forecast indicates sustained momentum: the market is expected to expand at a compound annual growth rate (CAGR) of 25.04% across the 2026–2032 forecast window, reaching USD 9,219.88 Million by 2032. These headline figures reflect not only rising demand for fuel cell systems across mobility and stationary power, but also intensified investment in high-volume manufacturing, material innovations, and stack-level integration.
Worldwide Bipolar Plate Fuel Cell Market
Concentration metrics underscore opportunities and competitive pressure. The market exhibits moderate concentration—top-three suppliers account for roughly 38.5% of value, and the top five capture approximately 52.15%—leaving room for new entrants that can deliver demonstrable cost, durability, or integration advantages.
Worldwide Bipolar Plate Fuel Cell Market
Why the 2026 Inflection Matters for Corporate Strategy
-
Capital allocation: With stacked annual growth and clear cost-down pathways, 2026 is a critical year for firms to decide between scaling internal manufacturing vs. partnering for outsourced, ready-to-install plates. Our analysis quantifies breakeven volumes and capex payback windows under multiple automation and coating scenarios.
-
Material strategy: Material choices—metallic, graphite, composite—carry distinct trade-offs across weight, manufacturability, cost, and corrosion management. The market is not “one-size-fits-all”: heavier-duty and stationary systems prioritize durability and recyclability, while light-duty mobility emphasizes weight and cost per kW. Our scenario models show how small shifts in adoption mix materially change supplier economics and raw-material procurement needs.
-
Manufacturing scale and automation: Regulatory and programmatic targets (for example, DOE guidance on manufacturing throughput) are pushing suppliers toward high-throughput systems. The U.S. DOE’s manufacturing benchmarks suggest single production systems capable of thousands of plates per hour at full maturity—targets that meaningfully affect footprint, tooling, and labor strategies.
-
Regulatory alignment and standards: International standards (notably the IEC 62282 series and national adaptations) and DOE technical targets for plate cost, weight, permeability, and corrosion behavior are shaping product specifications upstream. Firms that align development roadmaps to these specifications de-risk customer qualification and accelerate adoption.
What the Report Delivers — Practical, Actionable Content
-
Market modeling and forecasting engine: Transparent assumptions and sensitivity testing across scenario sets (base, accelerated adoption, and downside demand shock) enabling rapid recalculation of revenue and margin outcomes under alternative policy and technology shifts.
-
Cost and technology ladders: Detailed cost-driver breakdowns (materials, coatings, forming, secondary operations, and assembly) and roadmap pathways to meet DOE and industry cost targets—allowing procurement and R&D teams to prioritize interventions with the highest ROI.
-
Manufacturing playbooks: Benchmarked production concepts from pilot lines to automated high-throughput systems, including equipment capex ranges, floor-space envelopes, throughput gating points, and time-to-volume estimates.
-
Competitive supplier matrix: Vendor profiling across capabilities—material expertise, coating technologies, forming methods, geographic footprint, and commercialization status—paired with an executable partner-screening framework for OEMs and integrators.
-
Regulatory and standards mapping: A pragmatic guide that aligns product specs with relevant international and national standards, plus a compliance checklist to accelerate product certification and market entry.
-
Investment and M&A dashboard: Valuation comparables, M&A themes (vertical integration, IP consolidation, and localization), and trigger scenarios that make bolt-on acquisitions or greenfield investments compelling.
Competitive Landscape: Who’s Driving Innovation and How
Our industry mapping identifies a diverse set of incumbents and scale-up specialists, each positioning along different points of the value chain. The following executive snapshots summarize strategic plays observed in 2024–2026 that matter for 2026 decision-making:
-
Ballard Power Systems Inc. (Burnaby, Canada) — Focus: Graphite bipolar plates. Ballard is advancing scaled production strategies and cost reductions for next-generation graphite designs aimed at heavy-duty and stationary markets. Their emphasis on high-volume graphite production remains a benchmark for durability-focused applications.
-
Dana Incorporated (Maumee, United States; Neu-Ulm operations, Germany) — Focus: Metallic bipolar plates and electrolyzer components. Dana’s recent product launches combine precision forming with advanced coatings and integrated sealing; the company is positioning metallic plates as enablers for higher power density and lower system cost in green hydrogen applications.
-
SGL Carbon (Wiesbaden, Germany) and Schunk Carbon Technology (Heuchelheim, Germany) — Focus: Graphite and composite plates with high-volume capabilities. Both firms are scaling manufacturing to meet automotive and energy segment demand while protecting performance characteristics.
-
ElringKlinger / EKPO Fuel Cell Technologies (Dettingen/Erms, Germany) — Focus: Metallic plates and high-power stacks. EKPO’s product announcements of higher-power stacks with improved bipolar plates underline a push into heavy-duty transport and stationary solutions requiring recyclability and enhanced power density.
-
Feintool (Lyss, Switzerland; Taicang, China operations) — Focus: High-volume ready-to-install metallic plates. Feintool’s production ramp and high-volume orders for commercial vehicle programs demonstrate the readiness of stamped-metal approaches for mobility scale-up.
-
Cell Impact AB and Impact Coatings AB (Karlskoga & Linköping, Sweden) — Focus: Flow plate manufacturing technology and advanced coatings. Their capabilities are central to enabling cost-effective, corrosion-resistant metallic plates at scale.
-
Borit NV, GrafTech, POCO Graphite (Entegris), Nisshinbo Chemical, Shanghai Hongfeng — Focus: Material supply and specialty graphite/composite expertise. These players remain critical upstream suppliers as OEMs balance cost and performance trade-offs.
-
Schaeffler (Herzogenaurach, Germany) and Hutchinson (Paris, France) — Focus: Integrated solutions and sealing innovations. Strategic projects such as Hutchinson’s OBI-1 and Schaeffler’s Enertect-coated components highlight the move toward integrated, lower-cost fuel cell subsystems.
Recent Developments That Move the Needle
-
Product launches and orders: 2025–2026 saw multiple announcements of high-volume orders and product launches for metallic plates and stacks, signaling commercial momentum in mobility and stationary segments. Notable activity includes new electrolyzer plate offerings, high-volume manufacturing orders, and stack power-density improvements that alter system economics.
-
Pilot and scale-up demonstrations: Research institutes and industrial partners have showcased pilot plants and production demonstrations focused on rapid, cost-effective plate manufacture—reducing time-to-volume and enabling earlier qualification cycles for OEMs.
-
Standards and targets alignment: DOE technical targets and international standards are increasingly referenced by buyers as part of procurement criteria; suppliers aligning to these metrics are shortening the path to commercialization.
Strategic Recommendations for 2026 Decision-Makers
-
Prioritize modular production investments that can pivot between metal and composite flowplate lines. Flexibility will preserve optionality as customer specifications and material economics continue to evolve.
-
Invest in coatings and integrated sealing capabilities or secure tier-one partnerships to mitigate corrosion and contact-resistance risks—two failure modes that materially affect warranty costs and lifecycle performance.
-
Build supplier linkages for raw-material access (graphite powders, stainless and coated steels) and qualify multiple sources early to avoid single-point supply disruptions as volumes ramp.
-
Embed regulatory and standards compliance into product roadmaps. Aligning early to DOE and IEC targets will reduce qualification cycles with OEMs and expedite procurement wins.
-
Adopt staged expansion playbooks: pilot → contract-manufacture → brownfield expansion → greenfield automation. This minimizes cash exposure while enabling rapid capacity scaling when offtake is confirmed.
Closing: Why the Full Report Is a Necessity for 2026 Planning
This market snapshot conveys the macro trajectory and the practical levers that will determine winners over the next investment cycle. PW Consulting’s full report contains the underlying datasets, regional and application splits, supplier scorecards, detailed cost curves, and executable roadmaps that will enable procurement, R&D, and corporate development teams to make defensible 2026 spending and partnership decisions. To access the complete market tables, sensitivity models, and supplier benchmarking that we intentionally withhold here as part of this preview, please consult the full “Worldwide Bipolar Plate Fuel Cell Market” report.
For detailed analysis of this topic, please visit the official page: Worldwide Bipolar Plate Fuel Cell Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com