

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Arthroscopy Simulator Market Poised to Expand at a 9.15% CAGR, Unlocking New Training Opportunities

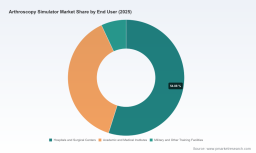
Worldwide Arthroscopy Simulator Market — Strategic Imperatives for 2026
PW Consulting’s newest market study on the Worldwide Arthroscopy Simulator Market distills five years of observed adoption dynamics (2020–2025) and delivers an actionable 2026–2032 forecast with frameworks designed for immediate operational use. The report quantifies a clear upward trajectory: the market has grown steadily through 2025 and, under our base-case assumptions, is set to expand at a compounded annual growth rate of 9.15% across the 2026–2032 forecast window. For executive teams planning capital allocation, product roadmaps, training partnerships or M&A activity in 2026, the implications are material — and time-sensitive.
Worldwide Arthroscopy Simulator Market
Market trajectory at a glance
-
Observed momentum (2020–2025): Consistent year-on-year expansion driven by curriculum integration, increasing institutional procurement and early deployment of portable VR solutions.
Worldwide Arthroscopy Simulator Market -
Near- and medium-term outlook (2026–2032): Under our central forecast the market continues to scale, reflecting broader acceptance of simulation-based credentialing, continued regulatory clarity for medical-training devices, and technology convergence between tactile models, augmented reality and portable virtual reality.
Worldwide Arthroscopy Simulator Market -
Concentration profile: The market exhibits moderate concentration; top-tier vendors account for a meaningful share of revenue and influence through partnerships with professional societies and hospital systems. Market consolidation, vertical partnerships and licensing deals are expected to increase strategic differentiation.
Why 2026 is a strategic inflection point
Several converging forces make 2026 a decision year for both incumbent vendors and new entrants:
-
Curriculum and credential alignment: Leading professional bodies have begun embedding simulation into proficiency-based curricula and exams, shifting procurement from discretionary training tools to mission-critical certification infrastructure.
-
Regulatory and validation tailwinds: Increasing regulatory clarity for training devices (e.g., pathway requirements in major markets) and a growing evidence base of construct validity for established platforms reduce purchaser risk and accelerate institutional adoption.
-
Technology displacement dynamics: Portable wireless VR solutions and hybrid AR/tactile platforms are lowering access barriers, enabling decentralized training models (on-site, mobile units, and remote programs) that change total cost of ownership calculus for buyers.
-
Service and outcome expectations: Buyers are prioritizing validated measurement, learning analytics and integration into clinical curricula — not just hardware — creating recurring revenue opportunities for vendors that can deliver software-as-a-service and managed training programs.
What PW Consulting’s report delivers (practical content summary)
The report is structured to be operationally useful on day one. Key deliverables include:
-
Proprietary market sizing and a 2026–2032 forecast model with scenario levers for regulatory shifts, adoption rates and unit economics.
-
Segmentation frameworks across geography, product type and end-user, with purchase-cycle mapping and demand drivers. (Note: detailed segment-level data and revenue splits are reserved for the full report.)
-
A validated vendor matrix profiling product capabilities, customer references, unit economics and go-to-market footprints.
-
Regulatory and reimbursement landscape mapping, including key clearance/certification pathways and regional compliance checklists.
-
Operational playbooks for training adoption: procurement checklists, pilot KPIs, validation protocols and integration timelines.
-
M&A and partnership heatmap with valuation considerations and diligence templates for strategic buyers and financial investors.
Competitive landscape — strategic read-throughs
Our competitive analysis highlights several distinct strategic archetypes among active suppliers and the implications for 2026 planning:
-
Platform integrators with society-level footprint: Vendors that combine validated curricula, measurable performance metrics, and formal partnerships with professional societies occupy a privileged position for large institutional contracts. Such firms derive competitive advantage from clinical validation and endorsement networks that reduce buyer friction.
-
Portable VR innovators: Solutions that decouple simulation from fixed hardware — particularly wireless/mobile VR offerings — are reshaping addressable markets by enabling low-cost, high-frequency training at the point of need. Partnerships between simulator developers and device OEMs/distributors accelerate deployment in decentralized training models.
-
High-fidelity / tactile specialists: Providers that deliver realistic haptic feedback and anatomical fidelity appeal to high-acuity training programs; however, their value proposition increasingly depends on measurable training outcomes and integration with digital assessment tools.
-
Regional and niche suppliers: Local manufacturers and training-model suppliers retain importance for institutions seeking cost-effective or deeply localized solutions, particularly where service, maintenance and language/localization are critical.
Recent market actions underline these dynamics: society-led mobile simulation programs and manufacturer partnerships to deliver portable VR training are accelerating institutional trials and procurement cycles. Longitudinal validation studies for some established platforms continue to be cited as decisive evidence in procurement decisions.
Implications for incumbents and new entrants
-
Incumbents: Protect validated advantages by packaging competence-based curricula, performance analytics and managed educational services. Invest selectively in portability and cloud-enabled analytics to capture recurring revenue streams and to defend against lower-cost mobile entrants.
-
New entrants: Focus on narrow, defensible use-cases where portability or price-performance materially expands addressable demand. Establish early partnerships with training programs and societies to accelerate validation and create reference customers.
-
Service companies and integrators: There is a rising opportunity to offer ‘simulation-as-a-service’ programs (including mobile simulators, on-site training, and assessment services) to bridge the gap between vendors and large institutional buyers.
Actionable recommendations for 2026 decision-makers
For executive teams preparing 2026 plans, we recommend the following prioritized actions:
-
Manufacturers — product and commercial strategy:
-
Prioritize modular, upgradeable architectures that support both tactile and VR modes to maximize addressable use-cases.
-
Design subscription pricing and managed-service bundles that align vendor success with institutional training outcomes (e.g., per-credential, per-learner models).
-
Secure validation partnerships with leading academic centers and specialty societies early to accelerate procurement cycles.
-
-
Hospitals & training centers — procurement and integration:
-
Run staged pilots that measure learning transfer and time-to-competency using standardized KPIs before committing to fleet purchases.
-
Embed simulators into mandatory credentialing and CME pathways to ensure utilization rates and to justify capex/opex.
-
Negotiate total-cost-of-ownership contracts including training, support and software updates rather than device-only purchases.
-
-
Investors & corporate development:
-
Prioritize targets with demonstrated institutional partnerships, recurring revenue models and validated clinical outcomes.
-
Perform diligence on data‑governance, integration APIs and regulatory pathway readiness — these are common deal-breakers post-acquisition.
-
Go-to-market playbook highlights
-
Leverage society endorsements and certification pilots to build referenceability; use co-branded pilot outcomes to shorten sales cycles.
-
Bundle hardware with outcome‑linked analytics and service-level agreements to transition buyers from capex-led to opex-led purchasing.
-
Localize service and maintenance footprints in target markets to minimize downtime and maximize program utilization.
-
Invest in comparative validation studies and publish measurable improvements in learner performance to reduce buyer uncertainty.
How PW Consulting accelerates your 2026 decisions
Our report pairs empirical demand modelling with operational playbooks so leaders can convert market forecasts into executable plans. If your 2026 priorities include launching a portable training product, negotiating institutional contracts, or evaluating acquisition targets, PW Consulting’s study provides the scenario-tested frameworks, procurement templates and valuation heuristics required to act with confidence.
For a detailed view of market splits, proprietary modeling assumptions and vendor scorecards (including performance, pricing and contract archetypes), access the full Worldwide Arthroscopy Simulator Market report and our interactive forecast model on PW Consulting’s publications page.
For detailed analysis of this topic, please visit the official page: Worldwide Arthroscopy Simulator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com