

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Automotive Inertial Systems Market to Rise from USD 4,250.0 Million in 2025 to USD 8,484.42 Million by 2032 at a 10.38% CAGR

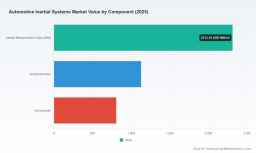
PW Consulting Releases Worldwide Automotive Inertial Systems Market — Strategic Briefing for 2026 Decision-Makers
Executive summary
PW Consulting’s latest market study on Worldwide Automotive Inertial Systems provides an evidence-based strategic roadmap for companies planning capital allocation, product roadmaps, supply‑chain decisions, and M&A activity in 2026 and beyond. The global market for automotive inertial systems — encompassing accelerometers, gyroscopes, and integrated inertial measurement units (IMUs) used across ADAS, stability control, navigation and safety systems — reached approximately USD 4.25 billion in 2025. Under our baseline scenario the market expands to roughly USD 8.48 billion by 2032, representing a compound annual growth rate (CAGR) of 10.38% over the forecast window. The sector is already moderately concentrated (CR3 ≈ 54.2%; CR5 ≈ 76.5%), but competitive dynamics are accelerating as incumbents and challengers reposition for higher-value autonomous and navigation-grade opportunities.
Worldwide Automotive Inertial Systems Market
Why this matters in 2026
-
Electrification and ADAS proliferation: The increase in vehicle electrification and ADAS penetration is raising average inertial sensor content per vehicle. Inertial sensors are no longer purely “background” components — they are integral to sensor fusion stacks, vehicle dynamics control, and autonomy verification.
Worldwide Automotive Inertial Systems Market -
Regulatory and qualification pressure: Functional safety (ISO 26262) and automotive qualification (AEC‑Q) requirements are imposing longer validation timelines and higher engineering costs on sensor suppliers and OEM integration programs. Safety-critical ASIL-B through ASIL-D qualifications are table stakes for IMUs used in vehicle control and autonomous functions.
Worldwide Automotive Inertial Systems Market -
Supply‑chain and materials constraints: MEMS inertial sensors depend on semiconductor-grade substrates; the global silicon wafer market (a key upstream input) was valued at approximately USD 15 billion in 2024–2025, and capacity competition is emerging as automotive demand competes with broader semiconductor demand.
-
Rising value of navigation-grade solutions: As autonomy ambitions grow, demand shifts from commodity MEMS to higher-performance inertial systems and sensor fusion packages, creating tiering within supplier value chains and margin dispersion.
What the report delivers (practical, action-ready content)
-
Proprietary market sizing and 2026–2032 forecasts with scenario sensitivity testing (conservative / baseline / accelerated adoption scenarios).
-
Supplier landscape and capability matrix: technology readiness, ASIL and AEC‑Q qualifications, production footprint, and typical OEM engagement models.
-
Commercial & procurement playbook: cost modeling for IMU and gyroscope assemblies, total cost of ownership comparisons across sourcing options, contractual levers to mitigate lead‑time and price volatility.
-
Technology roadmaps and product road‑testing checklist: MEMS performance ceilings, GNSS/INS fusion architectures, FOG/RLG positioning use cases, and verification regimes for safety-critical deployments.
-
M&A and partnering heatmap: target profiles, integration risks, and value-creation levers for strategic buyers, financial sponsors, and corporate development teams.
-
Supply‑chain risk register: wafer supply scenarios, single-source exposures, qualification timelines, and recommended dual-sourcing strategies.
-
Regulatory compliance guide: mapping of ISO 26262 and AEC‑Q requirements to product development milestones and procurement gating criteria.
Competitive landscape: what we found
The market is anchored by established Tier‑1 and semiconductor players that combine deep automotive qualifications with scale manufacturing. At the same time, focused MEMS specialists and defense/aerospace suppliers are pushing into automotive via crossover opportunities and targeted funding. Our analysis profiles primary players across technology, production footprint, safety credentials and commercial positioning — and identifies where winners will extract premium value.
-
Robert Bosch GmbH (Germany) — Bosch remains a leader in automotive MEMS IMUs and high-reliability sensors, with strong integration into ADAS and vehicle dynamics stacks. Their ASIL-D capable offerings and broad OEM relationships make Bosch a default primary supplier for safety‑critical programs, but high-tier pricing and long qualification lead times present opportunities for agile competitors on lower-cost, high-volume platforms.
-
Continental AG (Germany) — Continental’s focus on 6DoF inertial sensors and sensor-fusion ECUs positions them as an integrator for chassis control and diagnostics. Their recent partnerships underline a strategy to move up the value chain through software-enabled analytics and AI-driven diagnostics — a competitive vector for suppliers willing to co-develop platforms.
-
STMicroelectronics N.V. (Switzerland) — Following the strategic acquisition of an NXP MEMS unit in 2025, ST is consolidating volume MEMS capability with enhanced production scale. Their combination of automotive-grade MEMS, AI-enabled processing, and wafer supply control strengthens their position in both commodity and differentiated IMU segments.
-
Honeywell, Analog Devices, Safran, Northrop Grumman — These players bring high-performance and navigation-grade solutions, often crossing from aerospace and defense. Their strength is in precision and reliability rather than low-cost volume; they are preferred partners for premium and development programs requiring navigation-grade performance.
-
TDK (InvenSense), Murata, ACEINNA, Sensata — These suppliers occupy the broad middle: from high-volume automotive MEMS to feature-rich 6-axis IMUs. Recent product launches and partnerships suggest a push for broader distribution and system-level integration with GNSS and odometry partners.
-
Startups and niche players — Funding activity in 2025 (e.g., iNGage) highlights continued VC interest in high‑performance multi-axis MEMS for autonomous systems. These entrants can be acquisition targets or technology partners for OEMs seeking to accelerate roadmap gaps.
Recent market movements to watch
-
Strategic M&A and consolidation of MEMS lines — exemplified by STMicroelectronics’ acquisition activity — is reshaping manufacturing capacity and product portfolios.
-
Product launches and partnerships from established MEMS vendors (e.g., TDK’s automotive 6-axis IMU and Trimble collaboration) are accelerating system-level integration and shortening time-to-deployment for fused navigation solutions.
-
Tier‑1s are moving from component procurement to platform co‑development; Continental’s recent co‑development announcements reflect this trend.
Supply-chain and regulation: practical impacts for 2026 budgeting
Qualification timelines for AEC‑Q and ISO 26262 compliance add measurable calendar and cost premiums to new sensor introductions. OEMs and suppliers must model multi‑year lead times for validation and factor in wafer‑capacity risk tied to the broader USD 15 billion silicon wafer market. Our report provides a probabilistic model for supply constraints (and mitigation options such as multi-sourcing, captive fabs, or inventory buffering) and quantifies the margin and cash-flow implications for different sourcing strategies.
Technology trajectories and use-case segmentation
MEMS-based inertial solutions remain the dominant technology vector for mainstream ADAS and vehicle stability functions because of their favorable cost, size and scalability. Navigation-grade applications — including high-precision dead-reckoning for autonomous stacks and premium navigation — continue to pull demand toward higher-performance FOG/RLG or fused MEMS with advanced calibration and AI-based error compensation. Our report maps realistic performance-improvement curves for each technology path, and shows when hybrid approaches (e.g., MEMS + occasional high-grade aiding) become more economical than direct replacement of navigation-grade sensors.
Strategic recommendations for 2026
-
OEMs: Move from transactional procurement to strategic supplier partnerships for IMUs. Lock down ASIL-compliant suppliers early in program timelines; make investment decisions that prioritize supplier capacity verification and co‑development clauses to secure differentiated capabilities.
-
Tier‑1s and system integrators: Invest now in software and AI layers that extract value from inertial data (diagnostics, drift compensation, cybersecurity-aware fusion). Packages that combine sensor hardware with analytics will command margin premiums.
-
Semiconductor & MEMS suppliers: Consider selective vertical integration or long-term wafer agreements to de‑risk upstream constraints. Prioritize AEC‑Q and ISO 26262 certifications to shorten OEM qualification cycles and reduce go-to-market friction.
-
Investors and M&A teams: Target bolt-on assets that fill roadmap gaps (e.g., advanced calibration algorithms, navigation-grade MEMS die, or AI fusion middleware). Expect consolidation around players that can deliver both qualification credentials and volume scale.
-
Procurement leaders: Revisit total cost models to include qualification amortization, warranty exposure for safety-critical functions, and supply‑chain resilience costs. Contract structures should balance capacity guarantees, price transparency, and technical support obligations.
How PW Consulting’s report supports 2026 decision-making
Our study is designed as a decision-support tool — not just a market scoreboard. Clients receive the forecast models, supplier scorecards, procurement playbooks, and scenario toolkits necessary to: quantify the financial impact of supplier choices; prioritize R&D and capex decisions; stress-test M&A cases against supply-chain disruption scenarios; and align safety‑qualification timelines with product launch schedules. The study intentionally leaves detailed sub-segment tables and proprietary supplier revenue splits out of the public briefing to preserve the competitive value of the primary dataset; full access to the data tables and vendor-level revenue models is available through the report portal.
Next steps and call to action
For executives planning budgets, strategic partnerships, or M&A activity in 2026, the time to model inertial‑system risk and opportunity is now. PW Consulting’s Worldwide Automotive Inertial Systems Market report equips leaders with the evidence, scenario tools, and supplier intelligence required to make confident, time‑sensitive decisions. To review the full dataset, vendor revenue models, and the procurement playbook that underpins our recommendations, please consult the report gateway where the comprehensive segment breakdowns and interactive forecast tools are available.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Inertial Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com