

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Microencapsulated Paraffin Phase Change Materials Market to Grow at 13.52% CAGR, Hit USD 486 Million in 2025 and Top USD 1.18 Billion by 2032

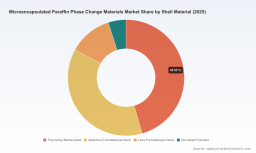
Worldwide Microencapsulated Paraffin PCM Market: Strategic Imperatives for 2026
As organizations race to embed energy efficiency and thermal intelligence across buildings, textiles, electronics and thermal storage systems, microencapsulated paraffin phase change materials (microPCM) have moved from niche lab curiosity to commercial lever. PW Consulting’s new market study — built on a 2020–2025 historical base and projecting through 2032 — quantifies that transition and translates it into actionable strategy for 2026 decision-makers.
Worldwide Microencapsulated Paraffin Phase Change Materials Market
Snapshot: What the numbers tell us (without giving everything away)
- The global microencapsulated paraffin PCM market has more than doubled in five years: from a modest industry tally in 2020 to nearly half-a-billion USD (base year 2025) in revenue. Our model anticipates continued momentum into the forecast window, with the market roughly doubling again by 2032.
- Growth is robust: the market is projected to expand at a compound annual growth rate (CAGR) of approximately 13.5% over the 2026–2032 forecast period — a rate that signals sustained commercial interest and multiple inflection opportunities for suppliers, integrators and end-users.
- Competitive structure is moderately concentrated: the top-tier players capture a meaningful share of sales while a mid-tier of specialized manufacturers and technology providers remain influential. This dynamic creates both scale advantages and openings for focused innovators.
Why this matters for 2026 strategy
For industrial strategists, procurement leads, product development executives and investors, the market metrics above are not mere vanity statistics — they are a directional guide to resource allocation in 2026. Key strategic implications include:
Worldwide Microencapsulated Paraffin Phase Change Materials Market
- Demand predictability: the size and growth trajectory validate investments in application-specific formulations and encapsulation capacity. Organizations that can match tailored PCM properties to end-use performance requirements will win the highest-margin contracts.
- Supply-chain sensitivity: paraffin feedstock pricing and regional availability remain key operational levers. Recent cycle volatility tied to crude-derived feedstocks has introduced margin variability, making sourcing strategies and hedging important near-term priorities.
- Sustainability and differentiation: bio-based polymer shells and lower-carbon paraffin routes are not just regulatory plays — they are commercial differentiators in tendering processes for green buildings, sustainable textiles and environmentally conscious OEMs.
- Integration over commodity-selling: the most durable opportunities lie where microPCM are integrated into finished systems (e.g., façade boards, smart textiles, battery modules) rather than sold as standalone powders. Partnerships with OEMs and systems integrators will accelerate uptake.
Report coverage — what you’ll find inside (practical deliverables)
PW Consulting’s study was designed as a practitioner's guide. The report synthesizes primary interviews, proprietary supply-chain mapping, material-cost modelling and techno-commercial case work to deliver useable outputs, including:
Worldwide Microencapsulated Paraffin Phase Change Materials Market
- Market sizing and conservative/optimistic scenario forecasts by product form, shell chemistry and application group (2020–2032).
- Supply-side playbook: manufacturer profiles, capacity maps, technology readiness assessments and white-space opportunity matrices.
- Raw material sensitivity analysis and a rolling-cost model that links paraffin and polymer feedstock swings to product margin bands.
- Commercial playbooks for embedding microPCM into building envelopes, HVAC components, technical textiles and battery thermal management systems — including sample ROI and payback templates.
- Regulatory and standards landscape: implications for certifications, fire performance and sustainability claims in major markets.
- M&A and partnership scouting framework with scorecards for target screening (technology fit, route-to-market, manufacturing footprint).
- Actionable risk register and mitigation strategies covering feedstock price shocks, scaling challenges, and IP/encapsulation quality risks.
Competitive landscape: what incumbents and challengers are doing
The market is populated by a mix of chemical majors, specialty PCM houses and regional manufacturers. Our company-level intelligence highlights how different players are positioning themselves for 2026 opportunities:
- Microtek Laboratories (Dayton, Ohio, United States; https://www.microteklabs.com): Established specialist with a diverse microPCM portfolio targeted at building materials, textiles and electronics. Their depth in paraffin-based microPCM and established customer relationships make them an important bellwether for demand trends.
- Rubitherm Technologies GmbH (Berlin, Germany; https://www.rubitherm.eu): European organic PCM manufacturer focused on construction and cold-chain applications. Rubitherm’s product development emphasizes integration with thermal energy storage systems and industrial applications.
- Croda International Plc (Snaith, United Kingdom; https://www.crodaindustrialspecialties.com): Broad-based specialty chemicals player pushing bio-based microPCM solutions. Their CrodaTherm line highlights the strategic pivot toward sustainable formulations valued by premium customers.
- PCM Products Ltd (United Kingdom; https://www.pcmproducts.net): Niche PCM producer with solutions across HVAC and thermal storage segments. Strong in applications requiring certification and proven fire/safety performance.
- Andores New Energy CO., Ltd (China; https://www.andores.com): Regional manufacturer with competitive cost structures, supplying microencapsulated paraffin for cold chain and building applications — a key participant in Asia’s scaling story.
- Honeywell International Inc. (Charlotte, NC, United States; https://www.honeywell.com): Leveraging systems expertise, Honeywell is integrating microPCM into intelligent HVAC and building control ecosystems — an example of the shift to system-level offerings.
- Encapsys, PureTemp, Climator, Phase Change Energy Solutions and other specialists: These players provide targeted encapsulation technologies, bio-based PCM alternatives and sector-specific solutions (textiles, battery thermal management, façade products).
Recent sector moves underscore the momentum: major chemical and technology firms have launched new microencapsulated paraffin product lines, expanded partnerships with HVAC and building systems OEMs, and announced bio-based initiatives. These developments accelerate commercialization and raise the bar on product validation for scale.
Segment dynamics and raw-material context (strategic takeaways only)
Rather than enumerating granular regional or application share data, our analysis maps qualitative drivers across the segments that matter:
- Building and construction: Regulatory pressure for energy efficiency and occupant comfort actively pushes façade, wallboard and insulation manufacturers to pilot microPCM-enhanced products. Procurement timelines are medium-term and dependent on certification pathways.
- Textiles and apparel: Demand is driven by premium performance wear and temperature-regulating consumer goods; product differentiation is achieved through encapsulation stability and wash durability.
- Electronics and battery thermal management: This is a high-growth technical application where reliability and thermal cycling performance are critical. Qualification cycles are longer, but payoffs for successful integrations are significant.
- Thermal energy storage systems: Macro and microPCM combinations are used to improve charge/discharge control and reduce system footprint; opportunities are project- and policy-driven.
On the raw-material front, paraffin feedstock pricing and regional availability continue to be principal sources of margin volatility. European feedstock pricing has tended to be at the upper end of the range, with North American and Asia variations influenced by local refining dynamics and crude feedstock movements. For procurement managers, this demands a dual approach: (1) diversified sourcing with contractual protections and (2) exploration of bio-based or alternative shell chemistries to reduce exposure.
What PW Consulting recommends companies do in 2026
We translate market intelligence into a prioritized action agenda for leadership teams:
- Fast-track application pilots that couple microPCM performance metrics with clear ROI frameworks — prioritize applications where simplicity of integration and short payback can be demonstrated.
- Lock in strategic supply agreements for paraffin and shell polymers with price-adjustment mechanisms; evaluate co-located manufacturing near major customers to reduce logistics and ensure rapid qualification cycles.
- Invest in encapsulation quality and cyclability testing as a means to differentiate — superior encapsulation reduces replacement costs and warranty exposure.
- Partner with systems integrators (HVAC, textile brands, battery OEMs) rather than selling commodity powders; embed PCM into solution bundles to capture lifecycle value.
- Assess acquisition or JV targets using our scoring framework to accelerate capability acquisition in bio-based shells, encapsulation IP or regional manufacturing footprints.
- Implement a scenario-based pricing and inventory strategy to manage raw-material volatility, and model the P&L impact of feedstock swings under multiple demand scenarios.
How the report helps with executive decision-making in 2026
PW Consulting’s market study is structured to inform board-level and commercial decisions with consequence: it reduces uncertainty around demand sizing, provides procurement-tested costing tools, and gives operators a step-by-step roadmap to scale production and commercialization. The report’s scenario modelling allows executives to stress-test capital allocation choices — from greenfield encapsulation lines to partnership-driven go-to-market pilots — under a range of realistic macro and commodity trajectories.
Next steps and how to obtain the detailed intelligence
This release is a strategic preview designed to surface the essential implications of the microencapsulated paraffin PCM market for 2026. To access the full dataset, granular segmentation tables, company revenue benchmarks, exhaustive competitive profiles and the actionable spreadsheets used in our sensitivity modelling, please consult PW Consulting’s report page or contact our sales team. The complete report contains the comprehensive figures and appendices necessary for transactional diligence, procurement negotiations and R&D prioritization.
In a market expanding at double-digit CAGR and shifting from material-level innovation to system-level impact, 2026 will separate speculative suppliers from those who can operationalize performance at scale. PW Consulting’s study equips you to be in the latter group.
For detailed analysis of this topic, please visit the official page: Worldwide Microencapsulated Paraffin Phase Change Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com