

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Subsea Umbilical Service Market to Reach USD 2,015.7 Million by 2032, Expanding at a 4.82% CAGR (2026–2032)
By pmarketresearch, 2026-07-17
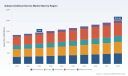
Subsea Umbilical Service Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive Summary
PW Consulting’s latest market brief on the Subsea Umbilical Service Market—anchored on a 2025 base year and covering historical performance from 2020–2025 with a forecast horizon of 2026–2032—delivers evidence-based guidance that c-suite leaders, project sponsors, and procurement strategists can put to work immediately. Our forecast models show the market expanding from an estimated USD 1,450.0 Million in 2025 to roughly USD 2,015.65 Million by 2032, corresponding to a compound annual growth rate (CAGR) of 4.82% across the 2026–2032 period. These headline figures are more than projection; they quantify the opportunity envelope within which companies must prioritize investments, partnerships, and capability-building in 2026.
Subsea Umbilical Service Market
Why This Brief Matters for 2026 Decisions
-
Timing of capital allocation: With steady mid-single-digit CAGR and a clear trajectory into 2032, operators and service providers must recalibrate CAPEX schedules and vendor selection frameworks now to capture growth windows in 2026–2028.
Subsea Umbilical Service Market -
Contracting strategy: The report’s scenario work identifies when medium- and long-lead procurements for umbilicals and associated SURF services should be initiated to mitigate supply-chain and manufacturing bottlenecks.
Subsea Umbilical Service Market -
Risk-adjusted bidding: Tender teams gain a forward-looking cost and schedule sensitivity analysis that helps structure technically robust yet commercially competitive bids under evolving raw-material and logistics pressures.
What’s Inside: Actionable Deliverables
Our brief is intentionally practical. It blends quantitative models with implementation guidance so that users can translate insight into action within weeks—not months. Key components include:
-
Proprietary forecasting engine: Scenario-based revenue trajectories for the market through 2032, allowing stakeholders to stress-test strategies under price, demand, and schedule shocks.
-
Commercial playbooks: Tailored contracting templates and sourcing routes for installation, inspection & monitoring, and maintenance & repair services that reflect current supplier behavior and project execution risk.
-
Supply-chain alpha map: A diagnostic of lead-time exposures, manufacturing capacity constraints, and procurement levers—designed to reduce time-to-deployment for umbilical systems.
-
CapEx/Opex sensitivity matrices: Trade-off analyses to inform build-vs-buy, life-extension, and refurbishment decisions that materially affect project NPV under different oil & gas commodity and service-price regimes.
-
Regulatory and qualification tracker: A consolidated view of offshore safety, environmental, and qualification requirements that accelerate vendor pre-qualification and reduce certification slippage.
-
Technology & materials horizon: A roadmap for specialized materials (advanced polymers, nickel alloys, titanium, composites) and developments in dynamic steel-tube designs that influence long-term TCO and operability.
-
Competitor capability matrix: A structured comparator that highlights where firms differentiate—manufacturing scale, service breadth, regional execution footprint, and lifecycle support offerings—enabling targeted partnership or competitive strategies.
Market Structure and Competitive Dynamics
The subsea umbilical services market remains moderately concentrated; our analysis places the top three players at a notable share of industry revenues, while the top five increase that concentration further—signalling that scale and integrated SURF capability continue to be strategic advantages. This market structure creates both barriers and levers for challengers: incumbents can defend margin through integrated project delivery, while nimble specialists can win by targeting lifecycle services and aftermarket maintenance niches.
Core participants profiled in the brief include JDR Cable Systems, TechnipFMC, Oceaneering International, Aker Solutions, Prysmian Group, OneSubsea (SLB), Subsea 7, Nexans, and Umbilicals International. For each, we analyze positioning across manufacturing footprint, service lifecycle coverage, technology differentiation, and commercial posture—highlighting where alliances, M&A, or capability investments would most change competitive balance.
Recent Signals from the Market (Implications for 2026)
-
JDR Cable Systems: Recent contract awards (including an April 2026 supply commitment for hydraulic control umbilicals for an East Coast project in Australia, and a 2025 testing contract in the Middle East) underscore JDR’s manufacturing cadence and its strategic use of regional facilities to secure multi-year delivery pipelines. For buyers, JDR’s actions indicate a reliable supplier for long-lead hydraulic control systems, but also a vendor with limited short-notice capacity during peak demand.
-
Subsea 7: The 2025 award for integrated engineering and offshore installation for flexible pipe, umbilicals, and subsea equipment reiterates the market premium placed on end-to-end SURF integrators capable of delivering complex offshore campaigns. Project sponsors evaluating fixed-price EPC options should weight Subsea 7-style propositions against provider risk appetites and execution track records.
-
Oceaneering International: The 2025 contract to supply a long-length electro-hydraulic steel tube dynamic umbilical for a Gulf of Mexico project demonstrates demand continuity for dynamic steel-tube solutions in deepwater environments and Oceaneering’s ability to mobilize manufacturing in North American facilities—an important consideration for clients prioritizing nearshore fabrication for logistics efficiency.
Sector Dynamics: Constraints and Tailwinds
Several cross-cutting trends define the operating environment:
-
Raw-material pressure: Rising prices for high-grade steel and advanced polymers, along with the use of specialty alloys and composites, are increasing CAPEX and elongating procurement lead times. The brief shows how material-cost volatility propagates into tender pricing and the optimal hedging approaches for large project sponsors.
-
Technical qualification burden: Stringent offshore safety and environmental standards raise up-front testing, certification, and qualification costs. Our regulatory tracker maps country- and project-level certification milestones so companies can pre-empt schedule slippage.
-
Deepwater expansion: Continued activity in deepwater developments and tie-back projects is a primary demand driver for umbilical services. The brief dissects how growth in deepwater tie-backs versus greenfield deepwater projects influences demand composition across installation, inspection, and lifecycle maintenance services.
Strategic Playbook for 2026
Based on the brief’s synthesis, we recommend a three-tiered strategic approach for companies seeking to convert 2026 market dynamics into sustained advantage:
-
Short-term (0–12 months): Lock in supply for long-lead items, execute risk-sharing contracts to manage raw-material cost exposure, and pre-qualify multiple manufacturing sources. Prioritize bidding on projects where integration and local delivery provide defensible margins.
-
Medium-term (12–36 months): Invest in aftermarket services and digital inspection platforms to capture higher-margin maintenance and monitoring revenue streams. Consolidate strategic partnerships with fabricators to expand capacity without onerous capex.
-
Long-term (36+ months): Build or acquire niche capabilities in advanced materials and dynamic umbilical systems, and pursue geographic diversification aligned with operators’ shifting project pipelines. Consider vertical integration selectively where lifecycle control yields measurable NPV uplift.
How PW Consulting’s Brief Enables Better Decision-Making
This report isn’t an academic exercise; it is the operational manual for executives making consequential 2026 choices. By combining robust market sizing (USD-denominated, with unit granularity), concentration metrics, supplier intelligence, and executable templates, the brief reduces time-to-insight and increases the probability of commercial success. Practical outputs—such as procurement playbooks, qualification timelines, and capex/opex trade-off models—translate forecast precision into executable boardroom decisions.
Next Steps: Where to Access the Full Intelligence
In keeping with our “preview” approach, this press summary surfaces the strategic observations and operational recommendations that PW Consulting stands behind, while reserving full segment-level tables, supplier scorecards, and the granular scenario models for the full report. Clients and decision-makers who require the detailed segmentation, vendor-level revenue estimates, and downloadable financial models should consult the full market study.
For procurement leaders, project managers, and strategy teams preparing their 2026 roadmaps: the full report contains the templates, timelines, and vendor comparators you will use to execute. Visit PW Consulting’s Subsea Umbilical Service Market page to license the complete study, obtain a tailored briefing, or request a client workshop to apply the models directly to your project pipeline.
For detailed analysis of this topic, please visit the official page: Subsea Umbilical Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Polyester Coating Market Reaches USD 12,825.4 Million in 2025, Poised for Robust Expansion
By pmarketresearch, 2026-07-17
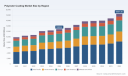
Worldwide Polyester Coating Market — Strategic Implications for 2026: A PW Consulting Executive Brief
As PW Consulting publishes its latest Worldwide Polyester Coating Market report, this executive brief surfaces the analysis executives need to orient strategic decisions for 2026. Drawing on a structured historical baseline (2020–2025), a clearly defined base year (2025), and a seven‑year forecast window (2026–2032), the full study quantifies a market that reached approximately USD 12,825.4 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.35% through 2032. By 2032 the market is modeled to approach the high‑teens (USD millions), reflecting a confluence of demand recovery in key end markets, incremental material- and process-driven innovation, and regulatory tailwinds toward low‑emission coating solutions.
Worldwide Polyester Coating Market
Why this report matters in 2026
-
Decision timing: 2026 is the year many capital projects, product launches, and procurement frameworks—initiated during the uneven recovery of 2021–2024—move from planning to execution. Our report bridges historical volatility with forward scenarios that materially affect investment sizing and timing.
Worldwide Polyester Coating Market -
Risk calibration: Raw material volatility and localized regulatory changes are altering cost structures and total landed costs for polyester resins and finished coatings. The study provides sensitivity models that translate PTA and other feedstock scenarios into margin impact across coated product families.
Worldwide Polyester Coating Market -
Competitive posture: The sector remains structurally fragmented at the global level, with the leading three and five suppliers accounting for a meaningful but not dominant share of the market. That fragmentation creates opportunities for targeted consolidation, capability-driven differentiation, and regional scale plays.
What the report delivers — practical, executable outputs
-
Market sizing & forward revenue scenarios: A 2025 baseline and a granular projection through 2032 under multiple macroeconomic and feedstock scenarios, enabling CFOs and strategy teams to stress‑test revenue and capex plans.
-
Segment playbooks (commercially designed): Prioritized go‑to‑market frameworks for powder, liquid, water‑borne, and UV/specialized polyester technologies—each with recommended channel strategies, OEM engagement tactics, and pricing levers. (Note: the public brief intentionally omits the proprietary breakdowns by region and end‑use that are provided in the paid report.)
-
Raw material sensitivity matrices: PTA pricing pathways and their modeled pass‑through to finished coating prices, margin compression thresholds, and hedging trigger points for procurement teams.
-
Regulatory impact maps: Jurisdictional summaries that correlate regulatory levers—such as low‑VOC mandates and surtax regimes—to demand shifts across coating types and substrate classes.
-
Competitive benchmarking and capability gaps: Side‑by‑side assessments of R&D pipelines, manufacturing footprints, and sustainability propositions to prioritize M&A targets and strategic partnerships.
-
Implementation tools: Template ROI models for capacity expansion, supplier risk heatmaps, and product roadmap prioritization sheets that accelerate decision cycles from months to weeks.
Macro drivers shaping 2026 strategy
-
Feedstock economics: Purified Terephthalic Acid (PTA) remains the dominant raw material driver for polyester coatings. The report models divergence in PTA price levels across regions and quantifies the margin sensitivity of common product platforms—information procurement and pricing teams need to determine when to hedge, pass costs through, or reengineer formulations.
-
Regulatory pressure and product substitution: Regulatory momentum—particularly in the EU—continues to favor powder and other low‑VOC systems over traditional solvent‑borne chemistries. That dynamic is accelerating R&D and commercial programs aimed at reformulation, testing, and certification.
-
Supply chain localization: The interplay of feedstock cost differentials, freight economics, and tariff/waiver developments (including specific surtax remission measures still in effect through 2026 in certain jurisdictions) is prompting manufacturers to consider localized resin production or nearer‑shore compounding lines to preserve margin and service levels.
-
End‑market recovery patterns: Appliance and consumer electronics, coil coatings, automotive components and construction markets are each rebounding on different rhythms. The report provides scenario mapping to show how shifts in capex, renovation cycles, and OEM sourcing decisions translate into polyester coating demand pockets.
Competitive landscape — strategic takeaways
The market’s leading suppliers combine broad technology portfolios, branded product suites, and regional manufacturing reach. Our competitive review concentrates on capability and intent rather than solely on revenue share, enabling a forward‑looking assessment of where competitive advantage will be established by 2028.
-
PPG Industries: Continues to play a leadership role in durable and weather‑resistant polyester systems while expanding sustainability credentials through product lines that incorporate recycled content. Recent product innovation signals a focus on both performance parity and lifecycle narratives that appeal to large OEMs and architects.
-
AkzoNobel: Maintains a global platform for powder and liquid polyester technologies with an emphasis on architectural and protective applications. Brand strength and channel access remain assets for rapid commercialization of low‑VOC solutions.
-
Axalta: Positioned for performance applications in industrial and refinish markets; strategic value for partners stems from application engineering and color management systems that lock in OEM relationships.
-
BASF: Investment into resin capacity and integrated feedstock strategies underscores a vertical approach—reducing feedstock exposure and enabling faster reformulation for evolving regulations.
-
The Sherwin‑Williams Company: Supply expansion and automation in coil lines highlight a play to lower unit costs and tighten lead times for industrial and architectural customers—important where speed and color consistency matter.
-
Arkema, Huntsman, Jotun, Nippon Paint, Allnex: Each of these players brings targeted strengths—resin innovation, specialty polyols, regional protection systems, Asia‑centric production scale, and specialized powder resin portfolios respectively. Collectively they create a competitive landscape where partnerships, co‑development and selective M&A will be decisive.
Recent corporate developments in 2025–2026 reinforce these themes: targeted new product launches incorporating recycled content; capacity expansions to support automotive and industrial demand; and strategic plant upgrades emphasizing automation and output efficiency. These are not isolated events but signals of a market entering a phase of capacity rationalization and technology differentiation.
How corporate leaders should act in 2026
-
Prioritize capex by scenario: Use the report’s scenario outputs to rank potential capacity investments against three topline scenarios (low, base, high). This avoids overcommitting ahead of feedstock normalization while preserving optionality for demand upside.
-
Hedge strategically: Procurement teams should adopt a rules‑based hedging calendar tied to PTA sensitivity thresholds identified in our models, rather than ad hoc spot reactions.
-
Reformulate for regulation: R&D leaders must fast‑track lower‑VOC powder and water‑borne alternatives in product families that face the strictest regulatory pressure—especially in key export corridors to the EU.
-
Lock in OEM relationships: Commercial teams should convert technical trials into long‑term supply agreements by coupling product guarantees with service commitments (color matching, lead time SLAs, testing certifications).
-
Screen targets for tuck‑ins and capability buys: The report identifies the types of assets and technology competencies that accelerate time‑to‑market—these should be prioritized over large bolt‑on buys that dilute focus.
The PW Consulting advantage — what you get in the full report
Our full report goes beyond high‑level commentary. It includes interactive models, proprietary supplier scorecards, an M&A hit‑list, and step‑by‑step playbooks to convert insight into action. We intentionally omit the detailed regional and application splits from this brief to preserve the integrity of the strategic intelligence reserved for subscribers and clients; these granular breakdowns are the core of valuation exercises, commercial targeting, and procurement restructuring.
For strategy teams preparing 2026 budgets and three‑year operating plans: this report supplies the decision‑grade inputs you need—market sizing by product family, scenarioed margin impacts from feedstock shocks, regulatory compliance cost ladders, and a ranked list of capability acquisitions that unlock near‑term revenue. For investors and M&A advisors: it identifies valuation levers tied to proprietary performance benchmarks and synergy capture opportunities.
Next steps
-
Download the full report to access the granular regional and application data and the downloadable financial models that underlie our scenario outputs.
-
Engage PW Consulting for a bespoke workshop to translate the report’s scenarios into a 90‑day action plan for procurement, R&D, and commercial teams.
-
Request the supplier heatmap and target list if you are evaluating strategic partnerships, technology licensing, or selective acquisitions in 2026.
In an industry where feedstock swings, regulation, and end‑market cycles intersect, 2026 will reward companies that combine disciplined capital allocation with rapid, application‑driven product adaptation. PW Consulting’s Worldwide Polyester Coating Market report gives leaders the analytical rigor and tactical toolkits to make those calls with confidence. For the full data set, segmented forecasts, and executable playbooks, visit our report page or contact our advisory team to schedule a strategy session.
For detailed analysis of this topic, please visit the official page: Worldwide Polyester Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Gluten-Free Baking Flour Market Tops USD 5,200 Million in 2025, Poised to Reach USD 9,116 Million by 2032 on 8.35% CAGR
By pmarketresearch, 2026-07-17
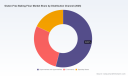
PW Consulting: Strategic Brief — The Gluten-Free Baking Flour Market and What the 2026 Playbook Should Look Like
PW Consulting today publishes a strategic preview of our forthcoming Gluten-Free Baking Flour Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). The quick thesis: gluten-free baking flours are transitioning from a niche, health-driven category to a structurally larger segment that demands distinct commercial playbooks across sourcing, manufacturing, and go-to-market models. Our analysis shows the addressable market reached approximately USD 5,200 Million in 2025 and is expected to grow at a compound annual growth rate of 8.35% through the 2026–2032 forecast horizon — putting long-term scale and margin opportunity squarely within reach of both ingredient suppliers and finished-goods players.
Gluten-Free Baking Flour Market
Why this matters for 2026 decisions
-
Scale is no longer a hypothetical: five years of elevated demand have transformed capacity and supplier dynamics. The market trajectory from 2020 to 2025 demonstrates durable consumer adoption and repeat-purchase behavior that justify near-term investments in supply continuity and product differentiation.
Gluten-Free Baking Flour Market -
Moderate concentration, material opportunity: competitive concentration metrics indicate a market where the top three firms capture roughly a third of value while the top five approach half — sufficient concentration to enable scale advantages, yet open enough for challengers to gain share through focused product, channel, or cost strategies.
Gluten-Free Baking Flour Market -
Raw-material exposure is a strategic lever and a vulnerability: rice and nut-based flours remain foundation ingredients for many blends. Volatility in rice or almond inputs (including the observed premium on blanched almond flour) can swing COGS and positioning. Procurement sophistication and alternative-source R&D will be differentiators in 2026.
-
Regulatory and operational compliance will be front-and-center: FDA labeling rules (gluten threshold under 20 ppm) remain the baseline, and ongoing regulatory activity — including extended comment periods on cross-contact prevention — will raise the bar for manufacturing controls and third-party auditing in 2026.
-
Recall risk is a real P&L and reputational event: recent voluntary recalls tied to undeclared allergens reinforce that gluten-free positioning does not by itself guarantee broad food-safety resilience. Companies must treat allergen-control as a board-level risk.
What PW Consulting’s full report delivers (practical, executable content)
The full report moves beyond market sizing to provide operational playbooks and decision-grade tools tailored for 2026 execution. Highlights include:
-
Proprietary forecasting models (scenario-based) for 2026–2032 that map demand by consumption driver and channel elasticity assumptions.
-
Go-to-market modules: SKU prioritization logic for retail, e-commerce, and foodservice; product-tier strategies (value, mainstream, premium); and private-label vs. branded margin analysis.
-
Supply-chain diagnostics and hedging frameworks: supplier concentration heatmaps, contract structuring templates, and cost-to-serve models for price-pass-through analysis.
-
Manufacturing and risk playbook: facility segregation decision tree for dedicated gluten-free lines, cross-contact prevention checklist aligned with current FDA guidance, and recall-response templates.
-
Innovation roadmaps and ingredient substitution matrices designed to preserve sensory quality while reducing input volatility and cost exposure.
-
Competitor benchmarking and M&A scouting: profiles, capability gaps, integration risk ratings, and a prioritized list of acquisition targets aligned to strategic intents.
Because this release is a strategic preview, we have intentionally withheld full numerical segment splits (regional/source/channel shares) here — those datasets, plus interactive dashboards and model access, are available through the full PW Consulting report.
Competitive landscape — what to watch in 2026
The market comprises vertically integrated brands, ingredient giants, and specialty innovators. Each archetype has a different route to competitive advantage.
-
Specialty retail leaders (example profile): Brands that manufacture in dedicated gluten-free facilities and emphasize artisanal or heritage positioning are capitalizing on trust and sensory fidelity. Their advantage is brand equity and control over cross-contact risks.
-
Mainstream consumer-packaged-goods players: Large food companies bring scale in distribution, pricing, and promotional reach. Their play is to simplify gluten-free usage for mass bakers via 1:1 blends and co-branded mixes, leveraging mainstream retail footprint.
-
Ingredient suppliers and millers: Bulk suppliers and ingredient processors are targeting B2B opportunities by providing stabilized, tested flours and custom blends that remove formulation complexity for food manufacturers and private-label customers.
How these archetypes map to recognizable names:
-
Companies with dedicated gluten-free manufacturing and consumer trust: Organizations that emphasize certified dedicated facilities and broad multipurpose blends can command premium shelf placement and justify higher retail prices through claims and trusted production practices.
-
Mainstream and scale players: Large CPGs are aiming to own penetration at grocery and club formats by offering approachable, familiar SKUs that reduce friction for everyday baking.
-
Ingredient and bulk suppliers: Commodity and specialty flour suppliers are expanding into premixed solutions for co-manufacturers and industrial bakers — an area where procurement sophistication pays off.
We analyze the strategic postures of leading participants across the value chain and provide playbooks for how each should prioritize investments in 2026 to either defend market share or accelerate growth.
Market dynamics and short-term shocks to model in 2026
-
Raw material constraints: Rice flour remains a foundational base for many blends; separate market analysis shows significant scale in rice-derived baking inputs, and price or quality shifts will transmit rapidly into flour blends. Blanched almond flour commands a material premium versus natural almond flour — this premium is a key lever for premiumization strategies but a risk for margin erosion.
-
Regulatory tightening: Continued FDA focus on cross-contact and labeling creates both compliance costs and competitive advantage for companies that operationalize higher standards early.
-
Operational risk: Recent voluntary recalls tied to undeclared allergens highlight the need for robust supplier controls, lot-tracing capabilities, and crisis-response readiness.
Concrete recommendations for executives — a 90-day prioritization for 2026
-
Stabilize supply by design: Identify critical ingredient exposures and implement a two-tier procurement strategy: strategic long-term contracts for core inputs and a secondary, validated supplier pool for contingency. Prioritize supply-chain audits for facilities claiming dedicated gluten-free production.
-
Invest in verification now: Upgrade in-house testing and third-party certification programs for gluten and major allergens. Current regulatory developments make this a defensive necessity and a commercial differentiator.
-
Revisit portfolio economics: Re-segment SKUs into value, mainstream, and premium tiers and run rapid pilots in e-commerce where sell-through data will validate willingness-to-pay. Reduce low-velocity SKUs that consume capacity without commensurate margin.
-
Operationalize recall-readiness: Implement lot-level traceability for at-risk SKUs, run tabletop exercises, and pre-negotiate PR and legal playbooks to reduce time-to-response.
-
Pursue targeted partnerships: For players lacking milling capability, consider co-manufacturing with certified facilities to accelerate market entry while protecting brand integrity.
-
Use M&A and JV selectively: Seek bolt-on acquisitions that close sensory or capacity gaps rather than broad horizontal deals; prioritize firms with validated gluten-free facilities and established private-label revenue.
Final note — how PW Consulting can accelerate your 2026 plan
For executives preparing capital allocations, commercial plans, or M&A theses for 2026, PW Consulting’s full report provides the numerical granularity and operational templates required to move from strategy to execution. The preview above is designed to surface the strategic choices we expect to determine winners and losers next year: supply certainty, testable product claims, channel-tailored SKUs, and fortified manufacturing controls.
If you are evaluating new production investments, supplier contracts, or portfolio changes for 2026, our advisory team can provide an executive briefing, custom scenario runs from our forecast model, and a tailored 90–180 day implementation roadmap. Note: this public briefing omits detailed regional, source, and channel splits — the full datasets and interactive dashboards are included with the PW Consulting report and available via our client portal.
For detailed analysis of this topic, please visit the official page: Gluten-Free Baking Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Belimumab Market Poised to Surge at 15.01% CAGR Through 2032 — Subcutaneous Adoption and North America to Drive Growth
By pmarketresearch, 2026-07-17
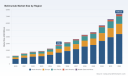
Worldwide Belimumab Market: Strategic Imperatives for 2026 — A PW Consulting Preview
As global health systems recalibrate post-pandemic, few orphan-to-specialty biologics present as focused and strategically consequential an opportunity as belimumab. PW Consulting’s new Worldwide Belimumab Market report (base year 2025; forecast 2026–2032) synthesizes market-scale economics, regulatory inflection points, supply-chain realities, and commercial playbooks into a single decision-grade resource for executive teams preparing plans for 2026.
Worldwide Belimumab Market
Why belimumab matters to 2026 strategy
Belimumab occupies a rare position: a clinically differentiated monoclonal antibody with established labels across systemic lupus erythematosus (SLE) and lupus nephritis (LN), delivered via both intravenous and subcutaneous routes, and with pediatric approvals expanding the addressable population. The market trajectory is robust — our model projects the global market expanding from USD 2,780.0 Million in 2025 to roughly USD 7,399.4 Million by 2032, at a compound annual growth rate (CAGR) of approximately 15.01% over the forecast horizon. That velocity, coupled with an exceptionally concentrated competitive structure (CR3 ≈ 96.4%; CR5 ≈ 99.1%), makes the space uniquely actionable for incumbents, potential entrants, and strategic investors alike.
Worldwide Belimumab Market
Key dynamics shaping 2026 decisions
-
Regulatory and label runway: Recent regulatory decisions — notably a 2025 FDA clearance of a pediatric autoinjector formulation and contemporaneous label updates to subcutaneous dosing — materially change prescribing patterns and patient uptake dynamics. These approvals create immediate tactical options for market access teams and longer-term implications for lifecycle management planning.
Worldwide Belimumab Market -
Commercial adoption and reimbursement: Benlysta retains broad formulary coverage across major commercial markets. Observed payer behaviors and public reimbursement analyses (including country-level cost benchmarks) underscore a willingness to fund this therapy where clinical and economic value are demonstrated — yet access remains sensitive to evidence depth and negotiated net price.
-
Manufacturing and supply: As a mammalian-cell-produced biologic, belimumab’s supply profile is capital- and time-intensive. Historical capacity investments and contract-manufacturing arrangements contribute to current supply resilience, but any strategic shift (e.g., line extensions, biosimilar entrants or dose-format proliferation) will require near-term CMO or in-house capacity decisions.
-
IP and competitive timing: Composition-of-matter protections persist into the early 2030s in major markets, with certain formulation-level IP cliffs projected around the mid- to late-2020s. No biosimilars are commercially available today — this creates a multi-year window to extract value and execute lifecycle strategies, but also to prepare defensive or offensive moves ahead of patent expiries.
What the report delivers — operationally focused insight
This is not a high-level synopsis. The report is engineered for 2026 decision cycles and includes a mix of quantitative models, playbooks and executable analytics:
-
Market sizing and scenario forecasts: A base-case projection (2026–2032) built on demand drivers, label events, and payer-access scenarios, with upside/downside scenarios to stress-test investment cases.
-
Commercial segmentation playbooks: Pragmatic go-to-market options for manufacturers and partners — covering channel mix optimization, formulary negotiation levers, pricing corridors, and patient-support program architectures. (Note: detailed sub-segment revenue tables are available in the full report.)
-
Regulatory & evidence strategy roadmap: A timeline of critical regulatory milestones and an evidence-generation blueprint that aligns RWE, pediatric data strategies, and pharmacoeconomic dossiers to payer decision criteria.
-
Manufacturing and supply-chain diagnostic: Assessment of biologics manufacturing bottlenecks, CMO partner evaluation criteria, capital-expansion scenarios, and inventory strategies to protect launches and mitigate volatility.
-
Competitive intelligence and M&A playbook: Deep profiles of incumbents, pipeline watchlists, and transaction archetypes — from bolt-on manufacturing assets to licensing deals that accelerate access into fragmented markets.
-
Risk register and mitigation strategies: Early-warning indicators for pricing pressure, biosimilar emergence, and regulatory setbacks; practical hedges spanning contracting, lifecycle R&D, and geographic prioritization.
Competitive landscape: strategic read on the originator
GlaxoSmithKline plc (GSK) remains the originator and primary commercial steward of belimumab (Benlysta). The company’s portfolio and recent actions illustrate how incumbents can extend value beyond origin IP:
-
Formulation and label extension: GSK’s multi-format approach (intravenous and subcutaneous autoinjector/prefilled syringe) and its recent pediatric autoinjector approval materially increase adoption flexibility — especially for outpatient and pediatric care settings.
-
Commercial momentum: Public disclosures indicate double-digit revenue growth for Benlysta into 2025, underscoring continued market penetration even as global stakeholders tighten budgets. This demonstrates an ability to grow through both label expansion and improved access strategies.
-
Supply posture and partnerships: GSK’s capacity investments and historical CMO relationships reflect an active approach to securing commercial supply. Any counterparty or new entrant must account for long lead times and the technical demands of monoclonal antibody production.
-
Intellectual property strategy: With core protections extending into the early 2030s and some formulation-level protections approaching mid-decade cliffs, the incumbent can strategically sequence lifecycle initiatives (new presentations, pediatric data, real-world safety/effectiveness packages) to preserve revenue while preparing for eventual competitive entry.
Strategic recommendations for 2026 planning
For executive teams shaping 2026 playbooks, the following priorities should be considered actionable and time-sensitive:
-
Prioritize evidence that matters to payers: Invest selectively in outcomes and cost-offset studies that align with major payer value frameworks. The nearer-term return on HEOR and RWE is high in negotiations for both launch sequencing and label extension value capture.
-
Lock in supply and CMO options now: Given biologic lead times and capacity constraints, secure manufacturing capacity and contingency agreements in 2026 to avoid disruption as demand scales through the forecast period.
-
Calibrate pricing strategies around segmentation levers: Use differential contracting (risk-sharing, indication-specific discounts, outcome-based agreements) to protect margins while expanding access into politically sensitive geographies.
-
Prepare IP and biosimilar playbooks: Whether defending through lifecycle innovation or preparing to compete post-patent, develop coordinated R&D and commercial scenarios that include timeline-based triggers for M&A, licensing, or pivot strategies.
-
Leverage pediatric and format innovations commercially: The autoinjector approval creates new channels to scale adoption; integrate patient-support models and decentralised-care capabilities to maximize uptake in ambulatory and pediatric settings.
What to expect in the near term (2026–2028)
Our scenarios show the market remains in a growth phase as label and format innovations convert latent demand into realized revenue. However, the window for strategic maneuvering is bounded: IP timelines and potential formulation-patent cliffs create a defined runway for value extraction and defensive planning. Tactical moves in 2026 — particularly around real-world evidence, manufacturing capacity, and payer contracting — will disproportionately affect medium-term outcomes through 2028 and beyond.
How PW Consulting can accelerate your 2026 decisions
PW Consulting’s report is structured as a decision support system, not just a market brief. Beyond the forecast and competitive snapshots, it provides executable templates for contracting, manufacturing sourcing scorecards, payer-differentiated evidence packages, and acquisition target shortlists calibrated to different risk appetites. For teams preparing board-level submissions or investment memoranda in 2026, the report’s modeling assets and playbooks can be adapted for immediate use.
Next steps
This preview is designed to outline the strategic contours of the belimumab opportunity and the priority decisions facing leadership teams in 2026. For detailed sub-segment economics, country-level forecasts, granular pricing scenarios, and the full set of commercial templates, please consult the full Worldwide Belimumab Market report on the PW Consulting portal — where the annexed data tables, downloadable models, and bespoke advisory options are provided to support rapid execution.
For detailed analysis of this topic, please visit the official page: Worldwide Belimumab Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Sunlight Simulators Market Projected to Reach USD 890.52 Million by 2032, Growing at a 7.0% CAGR
By pmarketresearch, 2026-07-17
Worldwide Sunlight Simulators Market — Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s new Worldwide Sunlight Simulators Market report presents an operationally-focused intelligence package designed to inform board-level and commercial decisions in 2026 and beyond. The market has moved from a mid-single‑hundred million dollar niche in 2020 to a robust platform market by 2025, with total revenues of USD 554.57 Million (base year 2025). Over the next seven years (forecast period 2026–2032) the market expands at a compound annual growth rate (CAGR) of 7.0%, reaching an estimated USD 890.52 Million by 2032.
Worldwide Sunlight Simulators Market
This press briefing synthesizes the strategic implications of that trajectory without exposing the full granularity contained in the report. We intentionally withhold proprietary product-, region-, and application-level splits here to preserve the report’s role as the single source of truth for practitioners seeking the full dataset and decision support models.
Worldwide Sunlight Simulators Market
Why sunlight simulators matter now — market drivers and inflection points
- Photovoltaic innovation is reshaping demand profiles: the rapid emergence of tandem and perovskite technologies, higher-throughput production lines, and wider area module formats are increasing the need for high‑accuracy, high‑repeatability light sources for both R&D and production acceptance testing.
- Aerospace and specialized science applications continue to broaden the use cases where standards-compliant AM0 and AM1.5G spectral fidelity matters, expanding the addressable market beyond traditional PV labs.
- Technology substitution and product evolution are under way: tunable LED systems, long-pulse and xenon flash architectures, and hybrid approaches are each capturing design wins in different use cases — creating both competitive disruption and new specialty product segments.
- Regulatory and standardization alignment (ASTM/IEC/JIS/ISO and sector-specific regulators) is pushing buyers toward accredited, traceable solutions and recurring calibration services — a structural tailwind for suppliers that can demonstrate compliance and measurement chains.
What the PW Consulting report delivers — practical content for 2026 action
- Rigorous market sizing and forecast model (2020–2025 historical, 2026–2032 forecast) with sensitivity scenarios and demand drivers mapped to macro and technology adoption pathways.
- Segment-level diagnostic tools: product architecture (LED, xenon, metal halide/others), application archetypes (from PV module testing to aerospace, materials, biotech/agriculture), and go-to-market vectors — each with profitability and time‑to‑market overlays. Note: detailed numeric splits are available only in the full report.
- Competitive landscape playbook: profiles of leading incumbents, recent M&A, product roadmaps, manufacturing footprints, and an acquisition pipeline heat map useful for assessing consolidation targets and partnership candidates.
- Supply chain and component risk assessments focused on LED chip availability, optics and integrating‑sphere vendors, high‑precision detectors, and xenon lamp lead times; plus mitigations to protect throughput and after‑sales uptime.
- Procurement and pricing benchmarking, including service-attach economics and lifecycle cost modeling that translates product choices into lab-level and factory-level TCOs.
- Practical checklists and KPIs for 2026: procurement timelines, expected calibration cadence, service-response SLAs, and R&D validation cycles aligned to buyers’ procurement habits.
Competitive landscape — who matters and why
The market exhibits increasing clustering around a handful of specialist players while remaining open to targeted entrants. The three‑company concentration (CR3) is meaningful but not dominant; the five‑company concentration (CR5) underlines a mid-tier of influential firms, creating a landscape where differentiated product features, standards compliance, and services determine commercial outcomes.
Worldwide Sunlight Simulators Market
- G2V Optics Inc. (Canada) — Known for tunable LED solar simulators with strong automation support and extended LED lifetimes. Their product philosophy emphasizes spectral agility (AM0 to AM1.5G replication) and modular scalability — important attributes for labs validating multi‑junction and perovskite architectures.
- Eternal Sun (Netherlands) — A leader in steady‑state LED and xenon flash solutions with strong traction in module IV‑testing. Their combined emphasis on temperature control and high‑class steady‑state fidelity positions them well for production acceptance workflows.
- Avalon ST (France) — Developer of large‑area, long‑pulse LED systems and, following its acquisition of PASAN SA in June 2025, now complements LED capability with xenon‑based metrology. The acquisition is a textbook example of strategic capability stacking to serve both R&D and large‑format module testing markets.
- Newport Corporation (Oriel), Solar Light Company, Abet Technologies, Sciencetech Inc. — Each brings differentiated strengths: broad standards compliance, specialized SPF and materials testing heritage, a wide SKU range, and the ability to deliver custom high‑flux systems. Notably, Sciencetech’s recent high‑flux installation demonstrates demand for bespoke, research‑grade assets.
These firms exemplify the dual-playbook that is emerging: (1) integrate measurement and spectral control with automation and data capture, and (2) monetize after-sales calibration and service as a stable recurring revenue stream. The market’s CR3 and CR5 metrics show room for strategic consolidation; acquirers should be selective in using M&A to fill capability gaps (e.g., xenon competence, calibration laboratories, software analytics) rather than simply scale.
Strategic imperatives for 2026 — what leaders must do now
- Prioritize product-platforms that map to validated use cases. For vendors, this means investing in modular architectures that serve both high‑accuracy R&D customers and high‑throughput production lines with differentiated firmware, spectral libraries, and automation interfaces.
- Monetize services and traceability. Develop accredited calibration and certification services as part of a bundled offering to capture lifetime value and reduce buyer procurement friction.
- Pursue targeted inorganic moves to complete capability stacks. The Avalon‑PASAN example underscores the strategic lift achieved when LED and xenon competencies are combined with precision metrology.
- De‑risk supply chains. Secure LED die supply, optics, and detector components through multi-source contracts and qualified second‑tier suppliers, and build inventory policies that balance working capital with service continuity.
- Standardize interfaces and data. Offer open APIs and compliance-ready reporting aligned to ASTM/IEC/JIS and lab accreditation expectations to accelerate buyer adoption and create lock‑in.
- Invest in go‑to‑market segmentation. Tailor sales motions to distinct buyer personas — R&D labs prioritize spectral fidelity and flexibility, manufacturing buyers prioritize throughput, uptime, and local support.
- Leverage calibration labs and test houses as channel partners. Strategic partnerships with accredited providers can extend geographic reach without capital‑intensive footprint expansion.
- Embed sustainability and lifecycle thinking. Highlight product energy efficiency (especially for LED‑based systems), end‑of‑life component recycling, and lower maintenance footprints as differentiators for enterprise customers.
Risks, unknowns, and what to watch in 2026
- Technology bifurcation — if a single light‑source architecture gains dominant validation for next‑gen PV cells, the installed base could re‑rate quickly, creating stranded R&D capital for non‑aligned suppliers.
- Standards evolution — shifts in ASTM/IEC test methods, or new regulatory push for traceability in aerospace or medical testing, could force rapid retrofits or validation cycles.
- Supply shocks — concentrated LED or optics suppliers could impose lead‑time volatility; firms that lack dual sourcing may face order cancellations or margin erosion.
- Consolidation dynamics — mid‑market M&A activity will accelerate; acquirers must balance scale benefits against integration risk, especially for calibration and software stacks.
How PW Consulting’s report supports 2026 decision-making
The report is designed as a practical decision tool for commercial planning, M&A diligence, product roadmaps, and operations. It combines a transparent, auditable market model with executable playbooks and vendor scorecards. For executives preparing budgets, the model translates projected module and aerospace testing demand into equipment, calibration, and service revenue streams — enabling scenario planning that aligns capital allocation with go‑to‑market timing.
We have deliberately presented the strategic narrative and headline macro figures here while preserving the report’s proprietary segment tables, regional dashboards, and supplier-level financial overlays for readers who require the complete intelligence package.
Next steps
If your organization is evaluating product investments, M&A targets, or a service expansion into calibration and lab partnership models, PW Consulting’s full Worldwide Sunlight Simulators Market report offers the granular datasets, vendor scorecards, and scenario models required to make confident 2026 decisions. For access to the full dataset, segmentation matrices, and downloadable models, please consult the official report release page referenced in the PW Consulting distribution channels.
Our team stands ready to support bespoke briefings, M&A diligence workshops, and implementation blueprints tailored to your strategic priorities for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Sunlight Simulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Aircraft Pressurisation Systems Market Poised for 6.32% CAGR During 2026–2032
By pmarketresearch, 2026-07-17
Worldwide Aircraft Pressurisation Systems Market: Strategic Imperatives for 2026
Executive preview — why this matters for 2026 decision-making
PW Consulting’s new market study on Worldwide Aircraft Pressurisation Systems synthesizes commercial, military and business aviation dynamics into an actionable roadmap for executives planning through 2026 and beyond. Built on a five‑year historical base (2020–2025) with 2025 as the base year and a detailed forecast window (2026–2032), the report quantifies the sector in USD Million and models market growth at a compound annual growth rate (CAGR) of 6.32% through the forecast period. The market reached an estimated USD 8,450.5 Million in 2025 and is projected to continue expanding into the second half of the decade — a trajectory driven by fleet renewal, retrofit activity, regulatory tightening and the gradual shift toward more‑electric architectures.
Worldwide Aircraft Pressurisation Systems Market
What this report delivers (practical, transaction‑ready deliverables)
- Market sizing and demand curves (historical 2020–2025; forecast 2026–2032) presented in USD Million with scenario sensitivity to fuel prices, OEM production plans and retrofit cycles.
- Systematic segmentation and go‑to‑market analysis across standard industry dimensions (geography, aircraft type, component systems, and service vs new‑build channels) — modelled to support target setting without disclosing granular segment tables in this summary.
- Competitive benchmarking and strategic profiles for leading OEMs and Tier‑1 suppliers, including product roadmaps, certification posture and after‑sales footprints.
- Regulatory and certification impact analysis (FAA/EASA) with timelines and critical path items for new system approvals and smoke/contamination mitigation requirements.
- Technology scenarios mapping — from incremental digital cabin pressure controllers to disruptive electric compressors and health‑monitored, software‑defined systems — with adoption curves and ROI templates for product managers.
- A practical M&A and partnership playbook including target archetypes, valuation sensitivity wedges, integration checklists and vendor due‑diligence templates.
- Actionable recommendations for procurement, aftermarket service strategy, retrofit market entry and capital allocation for 2026 planning cycles.
Market snapshot (concise, decision‑relevant numbers)
After steady recovery through the early 2020s, the pressurisation systems market reached approximately USD 8.45 billion in 2025. Our baseline scenarios project continued expansion with near‑term uplift as carriers accelerate retrofit programs and OEMs integrate more advanced, weight‑ and energy‑efficient solutions into new platform launches. The forecast (2026–2032) reflects a 6.32% CAGR, with the 2026 model year already showing a meaningful increase on 2025 levels under base assumptions. These topline trends should be read as directional signals for capital allocation, not as a substitute for the granular, region‑ and component‑level forecasts included in the full report.
Worldwide Aircraft Pressurisation Systems Market
Competitive landscape — concentration and strategic implications
The market demonstrates moderate‑to‑high concentration: our analysis of installed base and program wins shows that the top three players together control a majority share, while the top five command a significant incremental portion of market revenue. This structure creates both barriers and openings for challengers: scale and certification experience accelerate wins on large commercial platforms, while niche suppliers and innovators can capture aftermarket and advanced electric architecture opportunities.
Worldwide Aircraft Pressurisation Systems Market
- Honeywell Aerospace — advancing digital cabin pressure control with clear weight and reliability claims; its fourth‑generation DCPCS emphasizes brushless DC architectures and a 30% weight reduction narrative that materially alters aircraft-level tradeoffs between fuel burn and electrical load.
- Collins Aerospace (RTX) — positioning through integrated air management offerings and enhanced health‑monitoring for longer service intervals; its focus on retrofit friendliness is important for airlines seeking lower life‑cycle cost.
- Safran Group and Liebherr‑Aerospace — bring deep certification experience and test lab capabilities that reduce program risk on large transport platforms and military programs.
- ACE Thermal Systems (Signia) , Aeronamic and other emerging specialists — represent the innovation layer: automated scheduling, electric compressors and high‑speed e‑compressors aimed at more‑electric and zero‑bleed architectures.
- Moog and Parker Aerospace — focus on valves, actuators and the component ecosystem that remain strategically important to systems integrators and MROs.
Recent product activity underscores where competitive advantage is being established: Honeywell’s February 2025 DCPCS brochure refines a weight‑reduction and electrification narrative, while Collins’ May 2024 introduction of enhanced health‑monitoring systems signals a growing aftermarket and reliability‑led battleground. Suppliers investing in test capability, digital twin validation and retrofit kits are better positioned to capture near‑term upside.
Technology and regulatory dynamics shaping investment choices
- Transition to more‑electric architectures: Electric compressors and e‑CPS solutions reduce bleed‑air dependency, limiting contamination risks and enabling finer cabin‑altitude control. These technologies align with OEM goals to shrink environmental control system (ECS) weight and complexity but require new certification pathways and electrical power budgets.
- Digitalization & prognostics: Integrated cabin pressure controllers with health monitoring are extending service intervals and creating aftermarket differentiation. Systems with embedded prognostics enable outcome‑based maintenance contracts and predictable spares planning.
- Regulatory constraints and safety primacy: FAA and EASA standards (Part/CS‑25 and 14 CFR § 25.841) continue to enforce strict cabin altitude and relief‑valve redundancy requirements. Ongoing FAA research on bleed‑air contaminants elevates the compliance burden for bleed‑dependent systems and accelerates interest in non‑bleed solutions.
- Air quality and fume event mitigation: Operators and lessors are increasingly valuing designs that demonstrably reduce contamination risk or provide rapid isolation features — a trend that will influence procurement specifications and retrofit priorities in 2026 RFPs.
Practical implications by stakeholder for 2026 planning
- OEMs — Integrate electrification roadmaps with platform power budgets and certify early with regulators. Prioritize modular architectures that enable mixed fleets to adopt electric modules without extensive aircraft rework.
- Tier‑1 suppliers — Invest in digital diagnostics and certification capabilities; consider strategic partnerships with niche electric compressor innovators to accelerate platform‑ready offerings.
- Airlines & lessors — Target retrofit programs that maximize passenger perception (air quality) and operator economics (reduced maintenance and fuel tradeoffs). Demand supplier SLAs with prognostic data sharing for fleet‑level reliability modeling.
- MROs — Build competencies in electrical system maintenance and diagnostic software; retrofit service bundles will be a high‑margin growth area as operators seek lower life‑cycle costs.
- Investors & private equity — Seek targets with strong IRAD, test labs and certification track records. Favor assets that unlock recurring aftermarket revenue and those positioned for integration into more‑electric ecosystems.
Risks and mitigations for 2026
- Certification delays: Factor a 6–24 month certification risk premium into go‑to‑market timelines for electric compressors and major control system changes. Mitigate by parallel engagement with regulatory bodies and early test‑program commitments.
- Supply chain concentration: Diversify critical components and secure long‑lead items through multi‑sourcing or strategic inventory to avoid program slippage.
- Technology adoption uncertainty: Use staged investment linked to milestone gates (lab validation, flight test, certification) to manage R&D exposure.
- Regulatory shocks on bleed‑air: Model scenario contingencies for accelerated bleed‑air restrictions and identify retrofit paths for mixed fleets.
How to use this report in your 2026 planning cycle
- Set capital allocation priorities: use our ROI templates to compare retrofit vs new‑build investment cases across alternate technology scenarios.
- Refine supplier scorecards: apply the report’s vendor benchmarking to adjust procurement KPIs toward reliability, certification lead time and systems integration capacity.
- Identify quick wins: target aftermarket service bundles and retrofit kits for high‑utilization fleet types that can deliver near‑term cash flow enhancement.
- Plan M&A and partnerships: leverage the playbook to shortlist technical acquisition targets and evaluate integration risk using PW Consulting’s diligence checklist.
Conclusion & next steps
For executives preparing 2026 strategy, this sector is transitioning from component supply to system‑led offerings where software, prognostics and electrification are the primary differentiators. PW Consulting’s full report contains the granular regional and component forecasts, supplier share tables, and unit‑level economics that underpin the strategic recommendations summarized here. To access the complete dataset, proprietary supplier scorecards and the scenario model that produces the USD‑Million forecasts through 2032, please consult the PW Consulting report page or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Pressurisation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Metal Scavenging Agents Market to Expand at 6.85% CAGR Through 2032
By pmarketresearch, 2026-07-17
Worldwide Metal Scavenging Agents Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases a strategic preview of our forthcoming market research publication, Worldwide Metal Scavenging Agents Market (Base year: 2025). Designed as an executive decision-support tool for C-suite leaders, R&D heads, and corporate strategy teams, the full report combines primary interviews, manufacturing intelligence, and scenario modelling to inform high-stakes choices through 2032.
Worldwide Metal Scavenging Agents Market
Why this market matters in 2026
Metal scavenging agents — the materials and chemistries used to remove residual metals from process streams, products, and waste — are a quietly critical part of modern manufacturing quality and circularity. Our analysis shows the market expanding substantially in recent years, rising from roughly USD 178 million in 2020 to USD 245 million in 2025, with a projected year‑on‑year acceleration into 2026 and beyond. Over the forecast horizon (2026‑2032) we model a compound annual growth rate of 6.85%, driving the market toward an estimated USD 390 million by 2032.
Worldwide Metal Scavenging Agents Market
For 2026 specifically, several converging forces elevate the strategic importance of metal scavengers for enterprises: tightening regulatory scrutiny on metal impurities in pharmaceuticals and fine chemicals; increasing corporate commitments to resource recovery and circular manufacturing; technology shifts toward higher‑value, selective scavengers for precious metal recovery; and evolving supply‑chain risk profiles for specialty silica and polymer feedstocks. These dynamics make 2026 a critical planning year for capex, supplier strategy, product portfolio decisions, and M&A prioritization.
Worldwide Metal Scavenging Agents Market
What the PW Consulting report delivers — practical, transaction‑ready content
- Market sizing and validated historical performance (2020–2025) plus a detailed 2026–2032 forecast, with scenario and sensitivity analyses tailored to regulatory, commodity, and demand shocks.
- Demand drivers and end‑market mapping that link metal scavenger types to user pain points (e.g., trace Pd removal in small‑molecule pharma vs. bulk precious metal recovery in catalyst recycling).
- Competitive landscape diagnostics: vendor scorecards, manufacturing capacity maps, and a supplier risk heatmap calibrated to near‑term raw material pressures and geopolitical exposure.
- Commercial playbooks for three archetypes — global incumbents, regional specialists, and high‑growth niche innovators — including go‑to‑market, pricing and bundling recommendations, and play‑by‑play M&A targets.
- Operational benchmarks: typical cost structures, capex and scale thresholds for multi‑ton manufacturing, and QC/analytics investments required to support pharma GMP and advanced materials customers.
- Regulatory and quality matrix across major jurisdictions, with action lists for customers to demonstrate compliance and for suppliers to build defensible differentiation.
- Primary research appendices: anonymized buyer interviews, procurement RFP language examples, and a prioritized list of technical validation studies that accelerate commercial adoption.
Key, data‑driven market insights (trailer edition)
- Recovery and momentum: The market experienced a modest dip and stabilization in the early 2020s before accelerating into 2024–2025, reflecting recovering industrial throughput and renewed investment in purification capacity. The base‑year figure for 2025 is USD 245.0 million, and the model shows a meaningful step‑up in 2026 as several demand vectors re‑assert.
- Mid‑to‑long term growth: Our forecast CAGR of 6.85% for 2026–2032 embeds conservative and upside scenarios tied to regulatory tightening and expanded reuse/recovery use cases. Under our central case, the market approaches roughly USD 390 million by 2032.
- Concentration and competitive implications: Market concentration is meaningful but not prohibitive — the top three firms account for a sizeable share while the top five account for a majority. This structure creates durable advantages for scale players in manufacturing and distribution, while leaving distinct, addressable niches for specialized entrants and material innovators.
Competitive landscape: where incumbents and challengers stand
Our vendor analysis focuses on the leading technology providers and specialty chemical firms shaping the market. Below is a concise strategic read on the core players evaluated in the report:
- SiliCycle Inc. (Quebec City, Canada) — Strength: deep specialization in functionalized silica and multi‑ton manufacturing capability. Strategic priority: move from product sales toward service models that tie scavenger deployment to client process validation and precious‑metal recovery guarantees.
- Johnson Matthey (London, UK) — Strength: portfolio breadth (polymeric and silica offerings) and strong customer relationships in pharma & chemicals. Strategic priority: leverage scale to standardize higher‑margin, application‑specific kits and licensing for process validation workflows.
- Biotage (Uppsala, Sweden) — Strength: integrated toolkits and strong presence in small‑molecule pharma purification. Strategic priority: extend digital QC and analytics services to convert kit users into subscription customers.
- PhosphonicS (Abingdon, UK) — Strength: advanced functional materials and niche expertise in value recovery. Strategic priority: partner with recyclers and catalysts processors to monetize recovered metal streams at scale.
- BASF SE (Ludwigshafen, Germany) — Strength: global reach within a diversified chemical portfolio. Strategic priority: incubate specialized scavenging formulations within existing customer programs and offer integrated purification solutions.
- Merck KGaA / Sigma‑Aldrich (Darmstadt, Germany) — Strength: chemical distribution network and brand trust in pharma. Strategic priority: bundle scavengers with analytical reagents and validation services to capture higher wallet share in regulated segments.
- Fuji Silysia Chemical (Aichi, Japan) — Strength: silica material expertise with regional manufacturing strengths. Strategic priority: deepen partnerships with Asian pharmaceutical manufacturers and develop rapid‑deployment purification systems.
- United Chemical Technologies (UCT, Bristol, USA) — Strength: high‑purity silica products for analytical and pharma markets. Strategic priority: tighten supply assurances and develop GMP‑aligned product lines to migrate lab buyers into production accounts.
- Apollo Scientific (Stockport, UK) — Strength: high‑capacity, high‑loading scavengers and cross‑industry applicability. Strategic priority: pursue selective verticals (battery materials, electronics, refining) where large volumes justify dedicated formulations.
Each company brief in the full report pairs public and proprietary intelligence with an actionable SWOT and a short list of 90‑day moves to improve market position.
Strategic recommendations for 2026 decision‑makers
Based on the market dynamics and vendor intelligence captured in our study, PW Consulting recommends the following priority actions for companies making strategic commitments in 2026:
- Align product R&D to regulatory timelines. If serving pharma or fine chemicals, prioritize scavenger chemistries and qualification data that preempt stricter impurity limits announced or expected in core markets.
- Invest in circularity pilots. Run joint trials with catalyst processors and recyclers to recover precious metals from spent scavengers — projects that can convert waste streams into new revenue while de‑risking feedstock exposure.
- Pursue selective scale or partner play. Medium‑sized suppliers should choose between investing in multi‑ton capacity (to compete on unit economics) or forming strategic alliances to offer differentiated, application‑specific bundles (to capture margin).
- Strengthen supply assurance. For manufacturers, secure multi‑year supply agreements for critical silica and polymer inputs and map alternate feedstock sources to mitigate regional disruptions.
- Embed analytics and services. Differentiate on data — combine scavenger materials with on‑site or cloud‑based analytics and validation reporting to create higher retention and recurring revenue streams.
KPIs and decision milestones for a 2026 roadmap
- Short term (0‑6 months): complete supplier risk audit and run two targeted application validation studies that quantify metal removal, cycle life, and total cost of ownership.
- Medium term (6‑18 months): secure one strategic supply or offtake agreement and launch a joint piloting program for material recovery or process intensification.
- Long term (18+ months): hit defined ROI thresholds on capex investments (scale or analytics) and convert 25–40% of pilot customers into commercial accounts (benchmarked in the report by customer type).
How to use the full report — and what you won’t find in this preview
This preview is intentionally selective: it demonstrates the analytical depth and strategic orientation of the full PW Consulting study while withholding the granular segmentation tables, regional and application revenue splits, vendor scorecard scores, pricing curves, and the full set of primary interview excerpts — all of which are included in the paid report. Those detailed data and appendices are essential for transaction modeling, tender preparation, procurement negotiations, and M&A diligence.
For companies planning capital allocation, supplier consolidation, or M&A activity in 2026, the full report translates market forecasts and vendor diagnostics into a step‑by‑step playbook: validated market sizes by segment, mapped demand pathways by end‑use, unit economics and breakeven charts for scale investments, and a prioritized targets list for strategic partnerships and acquisitions.
Next steps
Contact PW Consulting to schedule an executive briefing and receive the full Worldwide Metal Scavenging Agents Market report package. Our advisory teams can also provide tailored workshops that convert the report’s insights into 90‑day implementation plans, procurement RFP templates, and investor‑grade diligence memos for potential M&A targets.
PW Consulting’s research is crafted to transform insight into action. In a market set to expand steadily through the next decade, using the right scavenger strategy in 2026 will determine who captures margin, who controls supply, and who turns spent materials into value.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Scavenging Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Valeryl Chloride Market to Grow at 5.15% CAGR to USD 105.45 Million by 2032 as Asia‑Pacific Commands 38.5% Share
By pmarketresearch, 2026-07-17
Worldwide Valeryl Chloride Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market study on Valeryl Chloride (n-pentanoyl chloride) delivers a compact, decision-ready briefing for corporate leaders preparing 2026 strategies across procurement, manufacturing, regulatory compliance, and M&A. Drawing on five years of historical analysis (2020–2025) and a seven-year forecast horizon (2026–2032), the report combines quantitative market modelling with hands‑on operational playbooks. To preserve commercial value and guide direct engagement with our research portal, we present high‑fidelity directional findings here while withholding granular subsegment allocations and supplier-level metrics.
Worldwide Valeryl Chloride Market
Market snapshot: trajectory and momentum
-
Base year and forecast framework — The study uses 2025 as the base year and projects the market across 2026–2032. We model in USD (revenue reported in Million USD) and apply scenario analysis to stress-test demand under policy, raw-material and macroeconomic shocks.
Worldwide Valeryl Chloride Market -
Historical performance and near-term outlook — The market demonstrated recovery and expansion across 2020–2025, moving from a lower base in 2020 through cyclical volatility to a stronger 2025 position. Under our central forecast, the market grows at a compound annual growth rate (CAGR) of 5.15% through the 2026–2032 period.
Worldwide Valeryl Chloride Market -
End-of-horizon scale — In the base and forecast scenarios the market is expected to expand materially by 2032 compared with 2025. This creates a window for capacity investors and for buyers to lock favorable terms before mid-horizon pricing recalibrations occur.
What the report delivers — practical content for operators and strategists
-
Market sizing and methodology: transparent model, assumptions, and sensitivity runs so finance teams can import figures directly into corporate planning tools.
-
Scenario playbooks: three demand/policy/scarcity scenarios with trigger indicators and recommended actions by stakeholder (procurement, production, regulatory, commercial).
-
Supplier benchmarking: qualitative and quantitative scorecards covering capability, quality grades, geographic exposure, compliance posture, and contract flexibility (note: supplier-specific scorecards and exact rankings are available in the full report).
-
Price and cost drivers analysis: raw-material linkages, particularly sensitivity to pentanoic (valeric) acid supply and reagent availability, plus freight and packaging premium impacts.
-
Regulatory and EHS matrix: jurisdictional compliance milestones (e.g., European REACH implications), handling/packaging requirements and CAPEX implications for storage and containment.
-
Commercial playbooks: template RFPs, risk-adjusted contract clauses for purity grades, sample testing protocols, and logistics/packaging specifications for safe cross-border movement.
-
Opportunities & threats: a prioritized list of high-conviction strategic moves, from near-term procurement levers to longer-term capacity expansions or vertical integration choices.
Dynamics shaping 2026 decision-making
-
Raw‑material and reagent sensitivity — Production of Valeryl Chloride is fundamentally linked to feedstock availability and chlorination reagents. Industry practice relies predominantly on conversion routes from valeric (pentanoic) acid using chlorinating agents such as thionyl chloride or phosphorus trichloride. Volatility in feedstock markets or constraint on specialty reagents can compress margins quickly; tactical inventory and alternate-supply qualification are therefore high-priority levers.
-
Regulatory and EHS pressure — Valeryl Chloride is corrosive and flammable with a low flash point and a propensity to hydrolyse. Handling, storage and disposal fall under strict regulatory regimes in many jurisdictions (including but not limited to frameworks like REACH). Companies should anticipate rising compliance costs, mandated reporting, and potential restrictions on intermediates handling — all of which affect total landed cost and working-capital requirements.
-
Packaging and logistics constraints — Practical constraints (e.g., lined or fluorinated drums to mitigate corrosion and migration, stability testing for hydrolysis) add non-trivial premiums to small-batch and specialty shipments. Buyers that optimize packaging specifications to supplier capabilities can reduce wastage and transport risk.
-
Market concentration and negotiating dynamics — The market sits at a level of concentration where top suppliers command a meaningful share. This creates both counterparty risk for large buyers and potential arbitrage opportunities for entrants that can offer differentiated compliance, quality, or service features.
Competitor landscape — what strategic profiles mean for buyers and investors
Our competitive review highlights a mix of regional production leaders, specialty producers focused on high-purity grades, and contract manufacturers with custom-synthesis capabilities. Key strategic observations:
-
China-based scale players — Incumbent manufacturers in China have broad product portfolios, integrated supply chains for intermediates, and strong position in cost-sensitive volumes. Their playbook emphasizes volume production, domestic integration and export-led sales. Buyers should factor in lead-time variability and compliance documentation when engaging these suppliers.
-
Specialty North American producers — Specialty firms in the U.S. emphasize high-purity material, rigorous technical documentation (TDS, CoA) and supply formats tailored for regulated pharma synthesis. These suppliers are often preferred by customers who prioritize traceability, packaging for phosgene-derived routes, and familiarity with advanced quality systems.
-
Indian manufacturers and exporters — Indian suppliers offer a competitive balance of cost and tailored services, especially for research-grade and industrial intermediates. Their strengths are in fast order fulfillment for mid-size volumes and export readiness, but buyers should validate quality systems and regulatory documentation for critical applications.
-
Service differentiation — The competitive advantage increasingly resides in service: contract-manufacturing flexibility, custom synthesis capabilities, rapid quality release testing, and specialized packaging for stability. Our full report contains supplier scorecards and a recommended short‑list framework for qualification.
Strategic playbook for 2026 — recommended priorities
-
Procurement: implement a two‑tier sourcing strategy that combines a core roster of qualified, audited suppliers with a rotating secondary bench to manage price and supply shocks. Include contractual clauses for reagent pass‑throughs and force‑majeure scenarios tied to reagent scarcity.
-
Risk mitigation: develop a raw-material hedging and inventory policy sensitive to valeric acid—and related reagents—price swings. Run stress scenarios that incorporate a reagent shortage and a regulatory tightening event.
-
Compliance investment: accelerate capital allocation for storage containment, upgraded drum-lining and hydrolysis mitigation systems to reduce loss rates and regulatory non-compliance exposure.
-
Commercial structuring: negotiate purity‑linked pricing bands and quality acceptance testing windows to reduce disputes and expedite batch release, especially for pharmaceutical intermediates where cycle time affects downstream drug production.
-
M&A and partnerships: target acquisitions that offer either geographic proximity to strategic end markets or capabilities in custom synthesis and specialty packaging to capture margin uplift.
90‑day action plan — operationalizing the insight
-
Week 0–4: run a supplier health audit focused on documentation (CoA, TDS), packaging capability, and regulatory certifications. Prioritize suppliers by strategic exposure.
-
Week 4–8: deploy a scenario-based procurement RFP that includes clauses for reagent disruptions and packaging requirements; secure at least one back-up qualified source.
-
Week 8–12: finalize short-term capital works for storage/containment and update SOPs for handling corrosive intermediates; integrate supplier performance KPIs into the procurement dashboard.
Why PW Consulting’s report matters for 2026 strategy
In a market where feedstock volatility, regulatory tightening and concentrated supplier power intersect, our 2026-focused guidance translates technical market intelligence into executable steps. The report bridges the gap between high-level forecasts (driven by our 2026–2032 CAGR modelling) and the on-the-ground operational measures procurement, quality and operations teams must adopt immediately.
We have deliberately preserved confidential segmentation details and supplier-specific rankings to ensure clients who need the full analytical depth and scorecards visit our research portal or engage directly with our advisory team. That deeper layer contains the validated supplier scorecards, subsegment allocations by application and region, and transaction-ready benchmarking tables that support contract negotiations and M&A diligence.
Next steps / contact
If your 2026 planning cycle includes exposure to pharmaceutical intermediates, agrochemical synthesis chains, or specialty chemicals procurement, PW Consulting’s Worldwide Valeryl Chloride Market report provides the data, playbooks and supplier intelligence to turn uncertainty into advantage. Access to the full dataset, segmentation breakdowns and supplier-level analytics is available via our report portal, where you can also request a tailored briefing or an executive workshop to translate the findings into your 2026 operating plan.
Engage with PW Consulting to convert market foresight into contractual leverage, operational resilience and targeted growth moves in the Valeryl Chloride value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Valeryl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com