

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Sunlight Simulators Market Projected to Reach USD 890.52 Million by 2032, Growing at a 7.0% CAGR

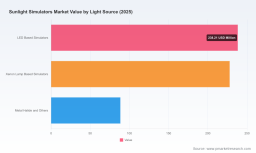
Worldwide Sunlight Simulators Market — Strategic Preview for 2026 Decisions
Executive summary
PW Consulting’s new Worldwide Sunlight Simulators Market report presents an operationally-focused intelligence package designed to inform board-level and commercial decisions in 2026 and beyond. The market has moved from a mid-single‑hundred million dollar niche in 2020 to a robust platform market by 2025, with total revenues of USD 554.57 Million (base year 2025). Over the next seven years (forecast period 2026–2032) the market expands at a compound annual growth rate (CAGR) of 7.0%, reaching an estimated USD 890.52 Million by 2032.
Worldwide Sunlight Simulators Market
This press briefing synthesizes the strategic implications of that trajectory without exposing the full granularity contained in the report. We intentionally withhold proprietary product-, region-, and application-level splits here to preserve the report’s role as the single source of truth for practitioners seeking the full dataset and decision support models.
Worldwide Sunlight Simulators Market
Why sunlight simulators matter now — market drivers and inflection points
- Photovoltaic innovation is reshaping demand profiles: the rapid emergence of tandem and perovskite technologies, higher-throughput production lines, and wider area module formats are increasing the need for high‑accuracy, high‑repeatability light sources for both R&D and production acceptance testing.
- Aerospace and specialized science applications continue to broaden the use cases where standards-compliant AM0 and AM1.5G spectral fidelity matters, expanding the addressable market beyond traditional PV labs.
- Technology substitution and product evolution are under way: tunable LED systems, long-pulse and xenon flash architectures, and hybrid approaches are each capturing design wins in different use cases — creating both competitive disruption and new specialty product segments.
- Regulatory and standardization alignment (ASTM/IEC/JIS/ISO and sector-specific regulators) is pushing buyers toward accredited, traceable solutions and recurring calibration services — a structural tailwind for suppliers that can demonstrate compliance and measurement chains.
What the PW Consulting report delivers — practical content for 2026 action
- Rigorous market sizing and forecast model (2020–2025 historical, 2026–2032 forecast) with sensitivity scenarios and demand drivers mapped to macro and technology adoption pathways.
- Segment-level diagnostic tools: product architecture (LED, xenon, metal halide/others), application archetypes (from PV module testing to aerospace, materials, biotech/agriculture), and go-to-market vectors — each with profitability and time‑to‑market overlays. Note: detailed numeric splits are available only in the full report.
- Competitive landscape playbook: profiles of leading incumbents, recent M&A, product roadmaps, manufacturing footprints, and an acquisition pipeline heat map useful for assessing consolidation targets and partnership candidates.
- Supply chain and component risk assessments focused on LED chip availability, optics and integrating‑sphere vendors, high‑precision detectors, and xenon lamp lead times; plus mitigations to protect throughput and after‑sales uptime.
- Procurement and pricing benchmarking, including service-attach economics and lifecycle cost modeling that translates product choices into lab-level and factory-level TCOs.
- Practical checklists and KPIs for 2026: procurement timelines, expected calibration cadence, service-response SLAs, and R&D validation cycles aligned to buyers’ procurement habits.
Competitive landscape — who matters and why
The market exhibits increasing clustering around a handful of specialist players while remaining open to targeted entrants. The three‑company concentration (CR3) is meaningful but not dominant; the five‑company concentration (CR5) underlines a mid-tier of influential firms, creating a landscape where differentiated product features, standards compliance, and services determine commercial outcomes.
Worldwide Sunlight Simulators Market
- G2V Optics Inc. (Canada) — Known for tunable LED solar simulators with strong automation support and extended LED lifetimes. Their product philosophy emphasizes spectral agility (AM0 to AM1.5G replication) and modular scalability — important attributes for labs validating multi‑junction and perovskite architectures.
- Eternal Sun (Netherlands) — A leader in steady‑state LED and xenon flash solutions with strong traction in module IV‑testing. Their combined emphasis on temperature control and high‑class steady‑state fidelity positions them well for production acceptance workflows.
- Avalon ST (France) — Developer of large‑area, long‑pulse LED systems and, following its acquisition of PASAN SA in June 2025, now complements LED capability with xenon‑based metrology. The acquisition is a textbook example of strategic capability stacking to serve both R&D and large‑format module testing markets.
- Newport Corporation (Oriel), Solar Light Company, Abet Technologies, Sciencetech Inc. — Each brings differentiated strengths: broad standards compliance, specialized SPF and materials testing heritage, a wide SKU range, and the ability to deliver custom high‑flux systems. Notably, Sciencetech’s recent high‑flux installation demonstrates demand for bespoke, research‑grade assets.
These firms exemplify the dual-playbook that is emerging: (1) integrate measurement and spectral control with automation and data capture, and (2) monetize after-sales calibration and service as a stable recurring revenue stream. The market’s CR3 and CR5 metrics show room for strategic consolidation; acquirers should be selective in using M&A to fill capability gaps (e.g., xenon competence, calibration laboratories, software analytics) rather than simply scale.
Strategic imperatives for 2026 — what leaders must do now
- Prioritize product-platforms that map to validated use cases. For vendors, this means investing in modular architectures that serve both high‑accuracy R&D customers and high‑throughput production lines with differentiated firmware, spectral libraries, and automation interfaces.
- Monetize services and traceability. Develop accredited calibration and certification services as part of a bundled offering to capture lifetime value and reduce buyer procurement friction.
- Pursue targeted inorganic moves to complete capability stacks. The Avalon‑PASAN example underscores the strategic lift achieved when LED and xenon competencies are combined with precision metrology.
- De‑risk supply chains. Secure LED die supply, optics, and detector components through multi-source contracts and qualified second‑tier suppliers, and build inventory policies that balance working capital with service continuity.
- Standardize interfaces and data. Offer open APIs and compliance-ready reporting aligned to ASTM/IEC/JIS and lab accreditation expectations to accelerate buyer adoption and create lock‑in.
- Invest in go‑to‑market segmentation. Tailor sales motions to distinct buyer personas — R&D labs prioritize spectral fidelity and flexibility, manufacturing buyers prioritize throughput, uptime, and local support.
- Leverage calibration labs and test houses as channel partners. Strategic partnerships with accredited providers can extend geographic reach without capital‑intensive footprint expansion.
- Embed sustainability and lifecycle thinking. Highlight product energy efficiency (especially for LED‑based systems), end‑of‑life component recycling, and lower maintenance footprints as differentiators for enterprise customers.
Risks, unknowns, and what to watch in 2026
- Technology bifurcation — if a single light‑source architecture gains dominant validation for next‑gen PV cells, the installed base could re‑rate quickly, creating stranded R&D capital for non‑aligned suppliers.
- Standards evolution — shifts in ASTM/IEC test methods, or new regulatory push for traceability in aerospace or medical testing, could force rapid retrofits or validation cycles.
- Supply shocks — concentrated LED or optics suppliers could impose lead‑time volatility; firms that lack dual sourcing may face order cancellations or margin erosion.
- Consolidation dynamics — mid‑market M&A activity will accelerate; acquirers must balance scale benefits against integration risk, especially for calibration and software stacks.
How PW Consulting’s report supports 2026 decision-making
The report is designed as a practical decision tool for commercial planning, M&A diligence, product roadmaps, and operations. It combines a transparent, auditable market model with executable playbooks and vendor scorecards. For executives preparing budgets, the model translates projected module and aerospace testing demand into equipment, calibration, and service revenue streams — enabling scenario planning that aligns capital allocation with go‑to‑market timing.
We have deliberately presented the strategic narrative and headline macro figures here while preserving the report’s proprietary segment tables, regional dashboards, and supplier-level financial overlays for readers who require the complete intelligence package.
Next steps
If your organization is evaluating product investments, M&A targets, or a service expansion into calibration and lab partnership models, PW Consulting’s full Worldwide Sunlight Simulators Market report offers the granular datasets, vendor scorecards, and scenario models required to make confident 2026 decisions. For access to the full dataset, segmentation matrices, and downloadable models, please consult the official report release page referenced in the PW Consulting distribution channels.
Our team stands ready to support bespoke briefings, M&A diligence workshops, and implementation blueprints tailored to your strategic priorities for 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Sunlight Simulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com