

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Subsea Umbilical Service Market to Reach USD 2,015.7 Million by 2032, Expanding at a 4.82% CAGR (2026–2032)

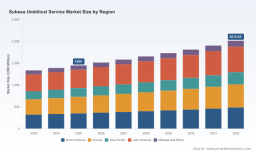
Subsea Umbilical Service Market 2026: Strategic Imperatives from PW Consulting’s New Industry Brief
Executive Summary
PW Consulting’s latest market brief on the Subsea Umbilical Service Market—anchored on a 2025 base year and covering historical performance from 2020–2025 with a forecast horizon of 2026–2032—delivers evidence-based guidance that c-suite leaders, project sponsors, and procurement strategists can put to work immediately. Our forecast models show the market expanding from an estimated USD 1,450.0 Million in 2025 to roughly USD 2,015.65 Million by 2032, corresponding to a compound annual growth rate (CAGR) of 4.82% across the 2026–2032 period. These headline figures are more than projection; they quantify the opportunity envelope within which companies must prioritize investments, partnerships, and capability-building in 2026.
Subsea Umbilical Service Market
Why This Brief Matters for 2026 Decisions
-
Timing of capital allocation: With steady mid-single-digit CAGR and a clear trajectory into 2032, operators and service providers must recalibrate CAPEX schedules and vendor selection frameworks now to capture growth windows in 2026–2028.
Subsea Umbilical Service Market -
Contracting strategy: The report’s scenario work identifies when medium- and long-lead procurements for umbilicals and associated SURF services should be initiated to mitigate supply-chain and manufacturing bottlenecks.
Subsea Umbilical Service Market -
Risk-adjusted bidding: Tender teams gain a forward-looking cost and schedule sensitivity analysis that helps structure technically robust yet commercially competitive bids under evolving raw-material and logistics pressures.
What’s Inside: Actionable Deliverables
Our brief is intentionally practical. It blends quantitative models with implementation guidance so that users can translate insight into action within weeks—not months. Key components include:
-
Proprietary forecasting engine: Scenario-based revenue trajectories for the market through 2032, allowing stakeholders to stress-test strategies under price, demand, and schedule shocks.
-
Commercial playbooks: Tailored contracting templates and sourcing routes for installation, inspection & monitoring, and maintenance & repair services that reflect current supplier behavior and project execution risk.
-
Supply-chain alpha map: A diagnostic of lead-time exposures, manufacturing capacity constraints, and procurement levers—designed to reduce time-to-deployment for umbilical systems.
-
CapEx/Opex sensitivity matrices: Trade-off analyses to inform build-vs-buy, life-extension, and refurbishment decisions that materially affect project NPV under different oil & gas commodity and service-price regimes.
-
Regulatory and qualification tracker: A consolidated view of offshore safety, environmental, and qualification requirements that accelerate vendor pre-qualification and reduce certification slippage.
-
Technology & materials horizon: A roadmap for specialized materials (advanced polymers, nickel alloys, titanium, composites) and developments in dynamic steel-tube designs that influence long-term TCO and operability.
-
Competitor capability matrix: A structured comparator that highlights where firms differentiate—manufacturing scale, service breadth, regional execution footprint, and lifecycle support offerings—enabling targeted partnership or competitive strategies.
Market Structure and Competitive Dynamics
The subsea umbilical services market remains moderately concentrated; our analysis places the top three players at a notable share of industry revenues, while the top five increase that concentration further—signalling that scale and integrated SURF capability continue to be strategic advantages. This market structure creates both barriers and levers for challengers: incumbents can defend margin through integrated project delivery, while nimble specialists can win by targeting lifecycle services and aftermarket maintenance niches.
Core participants profiled in the brief include JDR Cable Systems, TechnipFMC, Oceaneering International, Aker Solutions, Prysmian Group, OneSubsea (SLB), Subsea 7, Nexans, and Umbilicals International. For each, we analyze positioning across manufacturing footprint, service lifecycle coverage, technology differentiation, and commercial posture—highlighting where alliances, M&A, or capability investments would most change competitive balance.
Recent Signals from the Market (Implications for 2026)
-
JDR Cable Systems: Recent contract awards (including an April 2026 supply commitment for hydraulic control umbilicals for an East Coast project in Australia, and a 2025 testing contract in the Middle East) underscore JDR’s manufacturing cadence and its strategic use of regional facilities to secure multi-year delivery pipelines. For buyers, JDR’s actions indicate a reliable supplier for long-lead hydraulic control systems, but also a vendor with limited short-notice capacity during peak demand.
-
Subsea 7: The 2025 award for integrated engineering and offshore installation for flexible pipe, umbilicals, and subsea equipment reiterates the market premium placed on end-to-end SURF integrators capable of delivering complex offshore campaigns. Project sponsors evaluating fixed-price EPC options should weight Subsea 7-style propositions against provider risk appetites and execution track records.
-
Oceaneering International: The 2025 contract to supply a long-length electro-hydraulic steel tube dynamic umbilical for a Gulf of Mexico project demonstrates demand continuity for dynamic steel-tube solutions in deepwater environments and Oceaneering’s ability to mobilize manufacturing in North American facilities—an important consideration for clients prioritizing nearshore fabrication for logistics efficiency.
Sector Dynamics: Constraints and Tailwinds
Several cross-cutting trends define the operating environment:
-
Raw-material pressure: Rising prices for high-grade steel and advanced polymers, along with the use of specialty alloys and composites, are increasing CAPEX and elongating procurement lead times. The brief shows how material-cost volatility propagates into tender pricing and the optimal hedging approaches for large project sponsors.
-
Technical qualification burden: Stringent offshore safety and environmental standards raise up-front testing, certification, and qualification costs. Our regulatory tracker maps country- and project-level certification milestones so companies can pre-empt schedule slippage.
-
Deepwater expansion: Continued activity in deepwater developments and tie-back projects is a primary demand driver for umbilical services. The brief dissects how growth in deepwater tie-backs versus greenfield deepwater projects influences demand composition across installation, inspection, and lifecycle maintenance services.
Strategic Playbook for 2026
Based on the brief’s synthesis, we recommend a three-tiered strategic approach for companies seeking to convert 2026 market dynamics into sustained advantage:
-
Short-term (0–12 months): Lock in supply for long-lead items, execute risk-sharing contracts to manage raw-material cost exposure, and pre-qualify multiple manufacturing sources. Prioritize bidding on projects where integration and local delivery provide defensible margins.
-
Medium-term (12–36 months): Invest in aftermarket services and digital inspection platforms to capture higher-margin maintenance and monitoring revenue streams. Consolidate strategic partnerships with fabricators to expand capacity without onerous capex.
-
Long-term (36+ months): Build or acquire niche capabilities in advanced materials and dynamic umbilical systems, and pursue geographic diversification aligned with operators’ shifting project pipelines. Consider vertical integration selectively where lifecycle control yields measurable NPV uplift.
How PW Consulting’s Brief Enables Better Decision-Making
This report isn’t an academic exercise; it is the operational manual for executives making consequential 2026 choices. By combining robust market sizing (USD-denominated, with unit granularity), concentration metrics, supplier intelligence, and executable templates, the brief reduces time-to-insight and increases the probability of commercial success. Practical outputs—such as procurement playbooks, qualification timelines, and capex/opex trade-off models—translate forecast precision into executable boardroom decisions.
Next Steps: Where to Access the Full Intelligence
In keeping with our “preview” approach, this press summary surfaces the strategic observations and operational recommendations that PW Consulting stands behind, while reserving full segment-level tables, supplier scorecards, and the granular scenario models for the full report. Clients and decision-makers who require the detailed segmentation, vendor-level revenue estimates, and downloadable financial models should consult the full market study.
For procurement leaders, project managers, and strategy teams preparing their 2026 roadmaps: the full report contains the templates, timelines, and vendor comparators you will use to execute. Visit PW Consulting’s Subsea Umbilical Service Market page to license the complete study, obtain a tailored briefing, or request a client workshop to apply the models directly to your project pipeline.
For detailed analysis of this topic, please visit the official page: Subsea Umbilical Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com