

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Gluten-Free Baking Flour Market Tops USD 5,200 Million in 2025, Poised to Reach USD 9,116 Million by 2032 on 8.35% CAGR

PW Consulting: Strategic Brief — The Gluten-Free Baking Flour Market and What the 2026 Playbook Should Look Like
PW Consulting today publishes a strategic preview of our forthcoming Gluten-Free Baking Flour Market report (base year 2025, historical window 2020–2025, forecast 2026–2032). The quick thesis: gluten-free baking flours are transitioning from a niche, health-driven category to a structurally larger segment that demands distinct commercial playbooks across sourcing, manufacturing, and go-to-market models. Our analysis shows the addressable market reached approximately USD 5,200 Million in 2025 and is expected to grow at a compound annual growth rate of 8.35% through the 2026–2032 forecast horizon — putting long-term scale and margin opportunity squarely within reach of both ingredient suppliers and finished-goods players.
Gluten-Free Baking Flour Market
Why this matters for 2026 decisions
-
Scale is no longer a hypothetical: five years of elevated demand have transformed capacity and supplier dynamics. The market trajectory from 2020 to 2025 demonstrates durable consumer adoption and repeat-purchase behavior that justify near-term investments in supply continuity and product differentiation.
Gluten-Free Baking Flour Market -
Moderate concentration, material opportunity: competitive concentration metrics indicate a market where the top three firms capture roughly a third of value while the top five approach half — sufficient concentration to enable scale advantages, yet open enough for challengers to gain share through focused product, channel, or cost strategies.
Gluten-Free Baking Flour Market -
Raw-material exposure is a strategic lever and a vulnerability: rice and nut-based flours remain foundation ingredients for many blends. Volatility in rice or almond inputs (including the observed premium on blanched almond flour) can swing COGS and positioning. Procurement sophistication and alternative-source R&D will be differentiators in 2026.
-
Regulatory and operational compliance will be front-and-center: FDA labeling rules (gluten threshold under 20 ppm) remain the baseline, and ongoing regulatory activity — including extended comment periods on cross-contact prevention — will raise the bar for manufacturing controls and third-party auditing in 2026.
-
Recall risk is a real P&L and reputational event: recent voluntary recalls tied to undeclared allergens reinforce that gluten-free positioning does not by itself guarantee broad food-safety resilience. Companies must treat allergen-control as a board-level risk.
What PW Consulting’s full report delivers (practical, executable content)
The full report moves beyond market sizing to provide operational playbooks and decision-grade tools tailored for 2026 execution. Highlights include:
-
Proprietary forecasting models (scenario-based) for 2026–2032 that map demand by consumption driver and channel elasticity assumptions.
-
Go-to-market modules: SKU prioritization logic for retail, e-commerce, and foodservice; product-tier strategies (value, mainstream, premium); and private-label vs. branded margin analysis.
-
Supply-chain diagnostics and hedging frameworks: supplier concentration heatmaps, contract structuring templates, and cost-to-serve models for price-pass-through analysis.
-
Manufacturing and risk playbook: facility segregation decision tree for dedicated gluten-free lines, cross-contact prevention checklist aligned with current FDA guidance, and recall-response templates.
-
Innovation roadmaps and ingredient substitution matrices designed to preserve sensory quality while reducing input volatility and cost exposure.
-
Competitor benchmarking and M&A scouting: profiles, capability gaps, integration risk ratings, and a prioritized list of acquisition targets aligned to strategic intents.
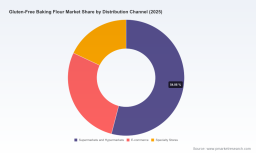
Because this release is a strategic preview, we have intentionally withheld full numerical segment splits (regional/source/channel shares) here — those datasets, plus interactive dashboards and model access, are available through the full PW Consulting report.
Competitive landscape — what to watch in 2026
The market comprises vertically integrated brands, ingredient giants, and specialty innovators. Each archetype has a different route to competitive advantage.
-
Specialty retail leaders (example profile): Brands that manufacture in dedicated gluten-free facilities and emphasize artisanal or heritage positioning are capitalizing on trust and sensory fidelity. Their advantage is brand equity and control over cross-contact risks.
-
Mainstream consumer-packaged-goods players: Large food companies bring scale in distribution, pricing, and promotional reach. Their play is to simplify gluten-free usage for mass bakers via 1:1 blends and co-branded mixes, leveraging mainstream retail footprint.
-
Ingredient suppliers and millers: Bulk suppliers and ingredient processors are targeting B2B opportunities by providing stabilized, tested flours and custom blends that remove formulation complexity for food manufacturers and private-label customers.
How these archetypes map to recognizable names:
-
Companies with dedicated gluten-free manufacturing and consumer trust: Organizations that emphasize certified dedicated facilities and broad multipurpose blends can command premium shelf placement and justify higher retail prices through claims and trusted production practices.
-
Mainstream and scale players: Large CPGs are aiming to own penetration at grocery and club formats by offering approachable, familiar SKUs that reduce friction for everyday baking.
-
Ingredient and bulk suppliers: Commodity and specialty flour suppliers are expanding into premixed solutions for co-manufacturers and industrial bakers — an area where procurement sophistication pays off.
We analyze the strategic postures of leading participants across the value chain and provide playbooks for how each should prioritize investments in 2026 to either defend market share or accelerate growth.
Market dynamics and short-term shocks to model in 2026
-
Raw material constraints: Rice flour remains a foundational base for many blends; separate market analysis shows significant scale in rice-derived baking inputs, and price or quality shifts will transmit rapidly into flour blends. Blanched almond flour commands a material premium versus natural almond flour — this premium is a key lever for premiumization strategies but a risk for margin erosion.
-
Regulatory tightening: Continued FDA focus on cross-contact and labeling creates both compliance costs and competitive advantage for companies that operationalize higher standards early.
-
Operational risk: Recent voluntary recalls tied to undeclared allergens highlight the need for robust supplier controls, lot-tracing capabilities, and crisis-response readiness.
Concrete recommendations for executives — a 90-day prioritization for 2026
-
Stabilize supply by design: Identify critical ingredient exposures and implement a two-tier procurement strategy: strategic long-term contracts for core inputs and a secondary, validated supplier pool for contingency. Prioritize supply-chain audits for facilities claiming dedicated gluten-free production.
-
Invest in verification now: Upgrade in-house testing and third-party certification programs for gluten and major allergens. Current regulatory developments make this a defensive necessity and a commercial differentiator.
-
Revisit portfolio economics: Re-segment SKUs into value, mainstream, and premium tiers and run rapid pilots in e-commerce where sell-through data will validate willingness-to-pay. Reduce low-velocity SKUs that consume capacity without commensurate margin.
-
Operationalize recall-readiness: Implement lot-level traceability for at-risk SKUs, run tabletop exercises, and pre-negotiate PR and legal playbooks to reduce time-to-response.
-
Pursue targeted partnerships: For players lacking milling capability, consider co-manufacturing with certified facilities to accelerate market entry while protecting brand integrity.
-
Use M&A and JV selectively: Seek bolt-on acquisitions that close sensory or capacity gaps rather than broad horizontal deals; prioritize firms with validated gluten-free facilities and established private-label revenue.
Final note — how PW Consulting can accelerate your 2026 plan
For executives preparing capital allocations, commercial plans, or M&A theses for 2026, PW Consulting’s full report provides the numerical granularity and operational templates required to move from strategy to execution. The preview above is designed to surface the strategic choices we expect to determine winners and losers next year: supply certainty, testable product claims, channel-tailored SKUs, and fortified manufacturing controls.
If you are evaluating new production investments, supplier contracts, or portfolio changes for 2026, our advisory team can provide an executive briefing, custom scenario runs from our forecast model, and a tailored 90–180 day implementation roadmap. Note: this public briefing omits detailed regional, source, and channel splits — the full datasets and interactive dashboards are included with the PW Consulting report and available via our client portal.
For detailed analysis of this topic, please visit the official page: Gluten-Free Baking Flour Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com