

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Metal Scavenging Agents Market to Expand at 6.85% CAGR Through 2032

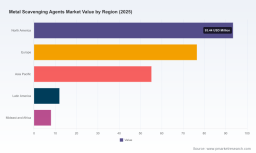
Worldwide Metal Scavenging Agents Market: Strategic Imperatives for 2026 — PW Consulting Report Preview
PW Consulting today releases a strategic preview of our forthcoming market research publication, Worldwide Metal Scavenging Agents Market (Base year: 2025). Designed as an executive decision-support tool for C-suite leaders, R&D heads, and corporate strategy teams, the full report combines primary interviews, manufacturing intelligence, and scenario modelling to inform high-stakes choices through 2032.
Worldwide Metal Scavenging Agents Market
Why this market matters in 2026
Metal scavenging agents — the materials and chemistries used to remove residual metals from process streams, products, and waste — are a quietly critical part of modern manufacturing quality and circularity. Our analysis shows the market expanding substantially in recent years, rising from roughly USD 178 million in 2020 to USD 245 million in 2025, with a projected year‑on‑year acceleration into 2026 and beyond. Over the forecast horizon (2026‑2032) we model a compound annual growth rate of 6.85%, driving the market toward an estimated USD 390 million by 2032.
Worldwide Metal Scavenging Agents Market
For 2026 specifically, several converging forces elevate the strategic importance of metal scavengers for enterprises: tightening regulatory scrutiny on metal impurities in pharmaceuticals and fine chemicals; increasing corporate commitments to resource recovery and circular manufacturing; technology shifts toward higher‑value, selective scavengers for precious metal recovery; and evolving supply‑chain risk profiles for specialty silica and polymer feedstocks. These dynamics make 2026 a critical planning year for capex, supplier strategy, product portfolio decisions, and M&A prioritization.
Worldwide Metal Scavenging Agents Market
What the PW Consulting report delivers — practical, transaction‑ready content
- Market sizing and validated historical performance (2020–2025) plus a detailed 2026–2032 forecast, with scenario and sensitivity analyses tailored to regulatory, commodity, and demand shocks.
- Demand drivers and end‑market mapping that link metal scavenger types to user pain points (e.g., trace Pd removal in small‑molecule pharma vs. bulk precious metal recovery in catalyst recycling).
- Competitive landscape diagnostics: vendor scorecards, manufacturing capacity maps, and a supplier risk heatmap calibrated to near‑term raw material pressures and geopolitical exposure.
- Commercial playbooks for three archetypes — global incumbents, regional specialists, and high‑growth niche innovators — including go‑to‑market, pricing and bundling recommendations, and play‑by‑play M&A targets.
- Operational benchmarks: typical cost structures, capex and scale thresholds for multi‑ton manufacturing, and QC/analytics investments required to support pharma GMP and advanced materials customers.
- Regulatory and quality matrix across major jurisdictions, with action lists for customers to demonstrate compliance and for suppliers to build defensible differentiation.
- Primary research appendices: anonymized buyer interviews, procurement RFP language examples, and a prioritized list of technical validation studies that accelerate commercial adoption.
Key, data‑driven market insights (trailer edition)
- Recovery and momentum: The market experienced a modest dip and stabilization in the early 2020s before accelerating into 2024–2025, reflecting recovering industrial throughput and renewed investment in purification capacity. The base‑year figure for 2025 is USD 245.0 million, and the model shows a meaningful step‑up in 2026 as several demand vectors re‑assert.
- Mid‑to‑long term growth: Our forecast CAGR of 6.85% for 2026–2032 embeds conservative and upside scenarios tied to regulatory tightening and expanded reuse/recovery use cases. Under our central case, the market approaches roughly USD 390 million by 2032.
- Concentration and competitive implications: Market concentration is meaningful but not prohibitive — the top three firms account for a sizeable share while the top five account for a majority. This structure creates durable advantages for scale players in manufacturing and distribution, while leaving distinct, addressable niches for specialized entrants and material innovators.
Competitive landscape: where incumbents and challengers stand
Our vendor analysis focuses on the leading technology providers and specialty chemical firms shaping the market. Below is a concise strategic read on the core players evaluated in the report:
- SiliCycle Inc. (Quebec City, Canada) — Strength: deep specialization in functionalized silica and multi‑ton manufacturing capability. Strategic priority: move from product sales toward service models that tie scavenger deployment to client process validation and precious‑metal recovery guarantees.
- Johnson Matthey (London, UK) — Strength: portfolio breadth (polymeric and silica offerings) and strong customer relationships in pharma & chemicals. Strategic priority: leverage scale to standardize higher‑margin, application‑specific kits and licensing for process validation workflows.
- Biotage (Uppsala, Sweden) — Strength: integrated toolkits and strong presence in small‑molecule pharma purification. Strategic priority: extend digital QC and analytics services to convert kit users into subscription customers.
- PhosphonicS (Abingdon, UK) — Strength: advanced functional materials and niche expertise in value recovery. Strategic priority: partner with recyclers and catalysts processors to monetize recovered metal streams at scale.
- BASF SE (Ludwigshafen, Germany) — Strength: global reach within a diversified chemical portfolio. Strategic priority: incubate specialized scavenging formulations within existing customer programs and offer integrated purification solutions.
- Merck KGaA / Sigma‑Aldrich (Darmstadt, Germany) — Strength: chemical distribution network and brand trust in pharma. Strategic priority: bundle scavengers with analytical reagents and validation services to capture higher wallet share in regulated segments.
- Fuji Silysia Chemical (Aichi, Japan) — Strength: silica material expertise with regional manufacturing strengths. Strategic priority: deepen partnerships with Asian pharmaceutical manufacturers and develop rapid‑deployment purification systems.
- United Chemical Technologies (UCT, Bristol, USA) — Strength: high‑purity silica products for analytical and pharma markets. Strategic priority: tighten supply assurances and develop GMP‑aligned product lines to migrate lab buyers into production accounts.
- Apollo Scientific (Stockport, UK) — Strength: high‑capacity, high‑loading scavengers and cross‑industry applicability. Strategic priority: pursue selective verticals (battery materials, electronics, refining) where large volumes justify dedicated formulations.
Each company brief in the full report pairs public and proprietary intelligence with an actionable SWOT and a short list of 90‑day moves to improve market position.
Strategic recommendations for 2026 decision‑makers
Based on the market dynamics and vendor intelligence captured in our study, PW Consulting recommends the following priority actions for companies making strategic commitments in 2026:
- Align product R&D to regulatory timelines. If serving pharma or fine chemicals, prioritize scavenger chemistries and qualification data that preempt stricter impurity limits announced or expected in core markets.
- Invest in circularity pilots. Run joint trials with catalyst processors and recyclers to recover precious metals from spent scavengers — projects that can convert waste streams into new revenue while de‑risking feedstock exposure.
- Pursue selective scale or partner play. Medium‑sized suppliers should choose between investing in multi‑ton capacity (to compete on unit economics) or forming strategic alliances to offer differentiated, application‑specific bundles (to capture margin).
- Strengthen supply assurance. For manufacturers, secure multi‑year supply agreements for critical silica and polymer inputs and map alternate feedstock sources to mitigate regional disruptions.
- Embed analytics and services. Differentiate on data — combine scavenger materials with on‑site or cloud‑based analytics and validation reporting to create higher retention and recurring revenue streams.
KPIs and decision milestones for a 2026 roadmap
- Short term (0‑6 months): complete supplier risk audit and run two targeted application validation studies that quantify metal removal, cycle life, and total cost of ownership.
- Medium term (6‑18 months): secure one strategic supply or offtake agreement and launch a joint piloting program for material recovery or process intensification.
- Long term (18+ months): hit defined ROI thresholds on capex investments (scale or analytics) and convert 25–40% of pilot customers into commercial accounts (benchmarked in the report by customer type).
How to use the full report — and what you won’t find in this preview
This preview is intentionally selective: it demonstrates the analytical depth and strategic orientation of the full PW Consulting study while withholding the granular segmentation tables, regional and application revenue splits, vendor scorecard scores, pricing curves, and the full set of primary interview excerpts — all of which are included in the paid report. Those detailed data and appendices are essential for transaction modeling, tender preparation, procurement negotiations, and M&A diligence.
For companies planning capital allocation, supplier consolidation, or M&A activity in 2026, the full report translates market forecasts and vendor diagnostics into a step‑by‑step playbook: validated market sizes by segment, mapped demand pathways by end‑use, unit economics and breakeven charts for scale investments, and a prioritized targets list for strategic partnerships and acquisitions.
Next steps
Contact PW Consulting to schedule an executive briefing and receive the full Worldwide Metal Scavenging Agents Market report package. Our advisory teams can also provide tailored workshops that convert the report’s insights into 90‑day implementation plans, procurement RFP templates, and investor‑grade diligence memos for potential M&A targets.
PW Consulting’s research is crafted to transform insight into action. In a market set to expand steadily through the next decade, using the right scavenger strategy in 2026 will determine who captures margin, who controls supply, and who turns spent materials into value.
For detailed analysis of this topic, please visit the official page: Worldwide Metal Scavenging Agents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com