

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
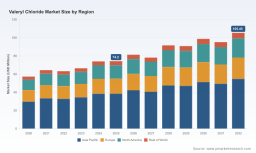
PW Consulting: Valeryl Chloride Market to Grow at 5.15% CAGR to USD 105.45 Million by 2032 as Asia‑Pacific Commands 38.5% Share

Worldwide Valeryl Chloride Market — Strategic Insights for 2026 Decision-Makers
PW Consulting’s latest market study on Valeryl Chloride (n-pentanoyl chloride) delivers a compact, decision-ready briefing for corporate leaders preparing 2026 strategies across procurement, manufacturing, regulatory compliance, and M&A. Drawing on five years of historical analysis (2020–2025) and a seven-year forecast horizon (2026–2032), the report combines quantitative market modelling with hands‑on operational playbooks. To preserve commercial value and guide direct engagement with our research portal, we present high‑fidelity directional findings here while withholding granular subsegment allocations and supplier-level metrics.
Worldwide Valeryl Chloride Market
Market snapshot: trajectory and momentum
-
Base year and forecast framework — The study uses 2025 as the base year and projects the market across 2026–2032. We model in USD (revenue reported in Million USD) and apply scenario analysis to stress-test demand under policy, raw-material and macroeconomic shocks.
Worldwide Valeryl Chloride Market -
Historical performance and near-term outlook — The market demonstrated recovery and expansion across 2020–2025, moving from a lower base in 2020 through cyclical volatility to a stronger 2025 position. Under our central forecast, the market grows at a compound annual growth rate (CAGR) of 5.15% through the 2026–2032 period.
Worldwide Valeryl Chloride Market -
End-of-horizon scale — In the base and forecast scenarios the market is expected to expand materially by 2032 compared with 2025. This creates a window for capacity investors and for buyers to lock favorable terms before mid-horizon pricing recalibrations occur.
What the report delivers — practical content for operators and strategists
-
Market sizing and methodology: transparent model, assumptions, and sensitivity runs so finance teams can import figures directly into corporate planning tools.
-
Scenario playbooks: three demand/policy/scarcity scenarios with trigger indicators and recommended actions by stakeholder (procurement, production, regulatory, commercial).
-
Supplier benchmarking: qualitative and quantitative scorecards covering capability, quality grades, geographic exposure, compliance posture, and contract flexibility (note: supplier-specific scorecards and exact rankings are available in the full report).
-
Price and cost drivers analysis: raw-material linkages, particularly sensitivity to pentanoic (valeric) acid supply and reagent availability, plus freight and packaging premium impacts.
-
Regulatory and EHS matrix: jurisdictional compliance milestones (e.g., European REACH implications), handling/packaging requirements and CAPEX implications for storage and containment.
-
Commercial playbooks: template RFPs, risk-adjusted contract clauses for purity grades, sample testing protocols, and logistics/packaging specifications for safe cross-border movement.
-
Opportunities & threats: a prioritized list of high-conviction strategic moves, from near-term procurement levers to longer-term capacity expansions or vertical integration choices.
Dynamics shaping 2026 decision-making
-
Raw‑material and reagent sensitivity — Production of Valeryl Chloride is fundamentally linked to feedstock availability and chlorination reagents. Industry practice relies predominantly on conversion routes from valeric (pentanoic) acid using chlorinating agents such as thionyl chloride or phosphorus trichloride. Volatility in feedstock markets or constraint on specialty reagents can compress margins quickly; tactical inventory and alternate-supply qualification are therefore high-priority levers.
-
Regulatory and EHS pressure — Valeryl Chloride is corrosive and flammable with a low flash point and a propensity to hydrolyse. Handling, storage and disposal fall under strict regulatory regimes in many jurisdictions (including but not limited to frameworks like REACH). Companies should anticipate rising compliance costs, mandated reporting, and potential restrictions on intermediates handling — all of which affect total landed cost and working-capital requirements.
-
Packaging and logistics constraints — Practical constraints (e.g., lined or fluorinated drums to mitigate corrosion and migration, stability testing for hydrolysis) add non-trivial premiums to small-batch and specialty shipments. Buyers that optimize packaging specifications to supplier capabilities can reduce wastage and transport risk.
-
Market concentration and negotiating dynamics — The market sits at a level of concentration where top suppliers command a meaningful share. This creates both counterparty risk for large buyers and potential arbitrage opportunities for entrants that can offer differentiated compliance, quality, or service features.
Competitor landscape — what strategic profiles mean for buyers and investors
Our competitive review highlights a mix of regional production leaders, specialty producers focused on high-purity grades, and contract manufacturers with custom-synthesis capabilities. Key strategic observations:
-
China-based scale players — Incumbent manufacturers in China have broad product portfolios, integrated supply chains for intermediates, and strong position in cost-sensitive volumes. Their playbook emphasizes volume production, domestic integration and export-led sales. Buyers should factor in lead-time variability and compliance documentation when engaging these suppliers.
-
Specialty North American producers — Specialty firms in the U.S. emphasize high-purity material, rigorous technical documentation (TDS, CoA) and supply formats tailored for regulated pharma synthesis. These suppliers are often preferred by customers who prioritize traceability, packaging for phosgene-derived routes, and familiarity with advanced quality systems.
-
Indian manufacturers and exporters — Indian suppliers offer a competitive balance of cost and tailored services, especially for research-grade and industrial intermediates. Their strengths are in fast order fulfillment for mid-size volumes and export readiness, but buyers should validate quality systems and regulatory documentation for critical applications.
-
Service differentiation — The competitive advantage increasingly resides in service: contract-manufacturing flexibility, custom synthesis capabilities, rapid quality release testing, and specialized packaging for stability. Our full report contains supplier scorecards and a recommended short‑list framework for qualification.
Strategic playbook for 2026 — recommended priorities
-
Procurement: implement a two‑tier sourcing strategy that combines a core roster of qualified, audited suppliers with a rotating secondary bench to manage price and supply shocks. Include contractual clauses for reagent pass‑throughs and force‑majeure scenarios tied to reagent scarcity.
-
Risk mitigation: develop a raw-material hedging and inventory policy sensitive to valeric acid—and related reagents—price swings. Run stress scenarios that incorporate a reagent shortage and a regulatory tightening event.
-
Compliance investment: accelerate capital allocation for storage containment, upgraded drum-lining and hydrolysis mitigation systems to reduce loss rates and regulatory non-compliance exposure.
-
Commercial structuring: negotiate purity‑linked pricing bands and quality acceptance testing windows to reduce disputes and expedite batch release, especially for pharmaceutical intermediates where cycle time affects downstream drug production.
-
M&A and partnerships: target acquisitions that offer either geographic proximity to strategic end markets or capabilities in custom synthesis and specialty packaging to capture margin uplift.
90‑day action plan — operationalizing the insight
-
Week 0–4: run a supplier health audit focused on documentation (CoA, TDS), packaging capability, and regulatory certifications. Prioritize suppliers by strategic exposure.
-
Week 4–8: deploy a scenario-based procurement RFP that includes clauses for reagent disruptions and packaging requirements; secure at least one back-up qualified source.
-
Week 8–12: finalize short-term capital works for storage/containment and update SOPs for handling corrosive intermediates; integrate supplier performance KPIs into the procurement dashboard.
Why PW Consulting’s report matters for 2026 strategy
In a market where feedstock volatility, regulatory tightening and concentrated supplier power intersect, our 2026-focused guidance translates technical market intelligence into executable steps. The report bridges the gap between high-level forecasts (driven by our 2026–2032 CAGR modelling) and the on-the-ground operational measures procurement, quality and operations teams must adopt immediately.
We have deliberately preserved confidential segmentation details and supplier-specific rankings to ensure clients who need the full analytical depth and scorecards visit our research portal or engage directly with our advisory team. That deeper layer contains the validated supplier scorecards, subsegment allocations by application and region, and transaction-ready benchmarking tables that support contract negotiations and M&A diligence.
Next steps / contact
If your 2026 planning cycle includes exposure to pharmaceutical intermediates, agrochemical synthesis chains, or specialty chemicals procurement, PW Consulting’s Worldwide Valeryl Chloride Market report provides the data, playbooks and supplier intelligence to turn uncertainty into advantage. Access to the full dataset, segmentation breakdowns and supplier-level analytics is available via our report portal, where you can also request a tailored briefing or an executive workshop to translate the findings into your 2026 operating plan.
Engage with PW Consulting to convert market foresight into contractual leverage, operational resilience and targeted growth moves in the Valeryl Chloride value chain.
For detailed analysis of this topic, please visit the official page: Worldwide Valeryl Chloride Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com