

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Polyester Coating Market Reaches USD 12,825.4 Million in 2025, Poised for Robust Expansion

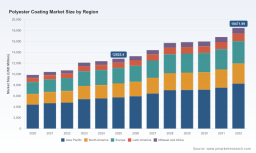
Worldwide Polyester Coating Market — Strategic Implications for 2026: A PW Consulting Executive Brief
As PW Consulting publishes its latest Worldwide Polyester Coating Market report, this executive brief surfaces the analysis executives need to orient strategic decisions for 2026. Drawing on a structured historical baseline (2020–2025), a clearly defined base year (2025), and a seven‑year forecast window (2026–2032), the full study quantifies a market that reached approximately USD 12,825.4 Million in 2025 and is projected to expand at a compound annual growth rate (CAGR) of 5.35% through 2032. By 2032 the market is modeled to approach the high‑teens (USD millions), reflecting a confluence of demand recovery in key end markets, incremental material- and process-driven innovation, and regulatory tailwinds toward low‑emission coating solutions.
Worldwide Polyester Coating Market
Why this report matters in 2026
-
Decision timing: 2026 is the year many capital projects, product launches, and procurement frameworks—initiated during the uneven recovery of 2021–2024—move from planning to execution. Our report bridges historical volatility with forward scenarios that materially affect investment sizing and timing.
Worldwide Polyester Coating Market -
Risk calibration: Raw material volatility and localized regulatory changes are altering cost structures and total landed costs for polyester resins and finished coatings. The study provides sensitivity models that translate PTA and other feedstock scenarios into margin impact across coated product families.
Worldwide Polyester Coating Market -
Competitive posture: The sector remains structurally fragmented at the global level, with the leading three and five suppliers accounting for a meaningful but not dominant share of the market. That fragmentation creates opportunities for targeted consolidation, capability-driven differentiation, and regional scale plays.
What the report delivers — practical, executable outputs
-
Market sizing & forward revenue scenarios: A 2025 baseline and a granular projection through 2032 under multiple macroeconomic and feedstock scenarios, enabling CFOs and strategy teams to stress‑test revenue and capex plans.
-
Segment playbooks (commercially designed): Prioritized go‑to‑market frameworks for powder, liquid, water‑borne, and UV/specialized polyester technologies—each with recommended channel strategies, OEM engagement tactics, and pricing levers. (Note: the public brief intentionally omits the proprietary breakdowns by region and end‑use that are provided in the paid report.)
-
Raw material sensitivity matrices: PTA pricing pathways and their modeled pass‑through to finished coating prices, margin compression thresholds, and hedging trigger points for procurement teams.
-
Regulatory impact maps: Jurisdictional summaries that correlate regulatory levers—such as low‑VOC mandates and surtax regimes—to demand shifts across coating types and substrate classes.
-
Competitive benchmarking and capability gaps: Side‑by‑side assessments of R&D pipelines, manufacturing footprints, and sustainability propositions to prioritize M&A targets and strategic partnerships.
-
Implementation tools: Template ROI models for capacity expansion, supplier risk heatmaps, and product roadmap prioritization sheets that accelerate decision cycles from months to weeks.
Macro drivers shaping 2026 strategy
-
Feedstock economics: Purified Terephthalic Acid (PTA) remains the dominant raw material driver for polyester coatings. The report models divergence in PTA price levels across regions and quantifies the margin sensitivity of common product platforms—information procurement and pricing teams need to determine when to hedge, pass costs through, or reengineer formulations.
-
Regulatory pressure and product substitution: Regulatory momentum—particularly in the EU—continues to favor powder and other low‑VOC systems over traditional solvent‑borne chemistries. That dynamic is accelerating R&D and commercial programs aimed at reformulation, testing, and certification.
-
Supply chain localization: The interplay of feedstock cost differentials, freight economics, and tariff/waiver developments (including specific surtax remission measures still in effect through 2026 in certain jurisdictions) is prompting manufacturers to consider localized resin production or nearer‑shore compounding lines to preserve margin and service levels.
-
End‑market recovery patterns: Appliance and consumer electronics, coil coatings, automotive components and construction markets are each rebounding on different rhythms. The report provides scenario mapping to show how shifts in capex, renovation cycles, and OEM sourcing decisions translate into polyester coating demand pockets.
Competitive landscape — strategic takeaways
The market’s leading suppliers combine broad technology portfolios, branded product suites, and regional manufacturing reach. Our competitive review concentrates on capability and intent rather than solely on revenue share, enabling a forward‑looking assessment of where competitive advantage will be established by 2028.
-
PPG Industries: Continues to play a leadership role in durable and weather‑resistant polyester systems while expanding sustainability credentials through product lines that incorporate recycled content. Recent product innovation signals a focus on both performance parity and lifecycle narratives that appeal to large OEMs and architects.
-
AkzoNobel: Maintains a global platform for powder and liquid polyester technologies with an emphasis on architectural and protective applications. Brand strength and channel access remain assets for rapid commercialization of low‑VOC solutions.
-
Axalta: Positioned for performance applications in industrial and refinish markets; strategic value for partners stems from application engineering and color management systems that lock in OEM relationships.
-
BASF: Investment into resin capacity and integrated feedstock strategies underscores a vertical approach—reducing feedstock exposure and enabling faster reformulation for evolving regulations.
-
The Sherwin‑Williams Company: Supply expansion and automation in coil lines highlight a play to lower unit costs and tighten lead times for industrial and architectural customers—important where speed and color consistency matter.
-
Arkema, Huntsman, Jotun, Nippon Paint, Allnex: Each of these players brings targeted strengths—resin innovation, specialty polyols, regional protection systems, Asia‑centric production scale, and specialized powder resin portfolios respectively. Collectively they create a competitive landscape where partnerships, co‑development and selective M&A will be decisive.
Recent corporate developments in 2025–2026 reinforce these themes: targeted new product launches incorporating recycled content; capacity expansions to support automotive and industrial demand; and strategic plant upgrades emphasizing automation and output efficiency. These are not isolated events but signals of a market entering a phase of capacity rationalization and technology differentiation.
How corporate leaders should act in 2026
-
Prioritize capex by scenario: Use the report’s scenario outputs to rank potential capacity investments against three topline scenarios (low, base, high). This avoids overcommitting ahead of feedstock normalization while preserving optionality for demand upside.
-
Hedge strategically: Procurement teams should adopt a rules‑based hedging calendar tied to PTA sensitivity thresholds identified in our models, rather than ad hoc spot reactions.
-
Reformulate for regulation: R&D leaders must fast‑track lower‑VOC powder and water‑borne alternatives in product families that face the strictest regulatory pressure—especially in key export corridors to the EU.
-
Lock in OEM relationships: Commercial teams should convert technical trials into long‑term supply agreements by coupling product guarantees with service commitments (color matching, lead time SLAs, testing certifications).
-
Screen targets for tuck‑ins and capability buys: The report identifies the types of assets and technology competencies that accelerate time‑to‑market—these should be prioritized over large bolt‑on buys that dilute focus.
The PW Consulting advantage — what you get in the full report
Our full report goes beyond high‑level commentary. It includes interactive models, proprietary supplier scorecards, an M&A hit‑list, and step‑by‑step playbooks to convert insight into action. We intentionally omit the detailed regional and application splits from this brief to preserve the integrity of the strategic intelligence reserved for subscribers and clients; these granular breakdowns are the core of valuation exercises, commercial targeting, and procurement restructuring.
For strategy teams preparing 2026 budgets and three‑year operating plans: this report supplies the decision‑grade inputs you need—market sizing by product family, scenarioed margin impacts from feedstock shocks, regulatory compliance cost ladders, and a ranked list of capability acquisitions that unlock near‑term revenue. For investors and M&A advisors: it identifies valuation levers tied to proprietary performance benchmarks and synergy capture opportunities.
Next steps
-
Download the full report to access the granular regional and application data and the downloadable financial models that underlie our scenario outputs.
-
Engage PW Consulting for a bespoke workshop to translate the report’s scenarios into a 90‑day action plan for procurement, R&D, and commercial teams.
-
Request the supplier heatmap and target list if you are evaluating strategic partnerships, technology licensing, or selective acquisitions in 2026.
In an industry where feedstock swings, regulation, and end‑market cycles intersect, 2026 will reward companies that combine disciplined capital allocation with rapid, application‑driven product adaptation. PW Consulting’s Worldwide Polyester Coating Market report gives leaders the analytical rigor and tactical toolkits to make those calls with confidence. For the full data set, segmented forecasts, and executable playbooks, visit our report page or contact our advisory team to schedule a strategy session.
For detailed analysis of this topic, please visit the official page: Worldwide Polyester Coating Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com