

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Aircraft Pressurisation Systems Market Poised for 6.32% CAGR During 2026–2032

Worldwide Aircraft Pressurisation Systems Market: Strategic Imperatives for 2026
Executive preview — why this matters for 2026 decision-making
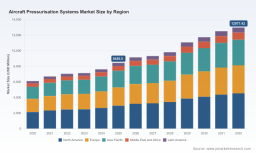
PW Consulting’s new market study on Worldwide Aircraft Pressurisation Systems synthesizes commercial, military and business aviation dynamics into an actionable roadmap for executives planning through 2026 and beyond. Built on a five‑year historical base (2020–2025) with 2025 as the base year and a detailed forecast window (2026–2032), the report quantifies the sector in USD Million and models market growth at a compound annual growth rate (CAGR) of 6.32% through the forecast period. The market reached an estimated USD 8,450.5 Million in 2025 and is projected to continue expanding into the second half of the decade — a trajectory driven by fleet renewal, retrofit activity, regulatory tightening and the gradual shift toward more‑electric architectures.
Worldwide Aircraft Pressurisation Systems Market
What this report delivers (practical, transaction‑ready deliverables)
- Market sizing and demand curves (historical 2020–2025; forecast 2026–2032) presented in USD Million with scenario sensitivity to fuel prices, OEM production plans and retrofit cycles.
- Systematic segmentation and go‑to‑market analysis across standard industry dimensions (geography, aircraft type, component systems, and service vs new‑build channels) — modelled to support target setting without disclosing granular segment tables in this summary.
- Competitive benchmarking and strategic profiles for leading OEMs and Tier‑1 suppliers, including product roadmaps, certification posture and after‑sales footprints.
- Regulatory and certification impact analysis (FAA/EASA) with timelines and critical path items for new system approvals and smoke/contamination mitigation requirements.
- Technology scenarios mapping — from incremental digital cabin pressure controllers to disruptive electric compressors and health‑monitored, software‑defined systems — with adoption curves and ROI templates for product managers.
- A practical M&A and partnership playbook including target archetypes, valuation sensitivity wedges, integration checklists and vendor due‑diligence templates.
- Actionable recommendations for procurement, aftermarket service strategy, retrofit market entry and capital allocation for 2026 planning cycles.
Market snapshot (concise, decision‑relevant numbers)
After steady recovery through the early 2020s, the pressurisation systems market reached approximately USD 8.45 billion in 2025. Our baseline scenarios project continued expansion with near‑term uplift as carriers accelerate retrofit programs and OEMs integrate more advanced, weight‑ and energy‑efficient solutions into new platform launches. The forecast (2026–2032) reflects a 6.32% CAGR, with the 2026 model year already showing a meaningful increase on 2025 levels under base assumptions. These topline trends should be read as directional signals for capital allocation, not as a substitute for the granular, region‑ and component‑level forecasts included in the full report.
Worldwide Aircraft Pressurisation Systems Market
Competitive landscape — concentration and strategic implications
The market demonstrates moderate‑to‑high concentration: our analysis of installed base and program wins shows that the top three players together control a majority share, while the top five command a significant incremental portion of market revenue. This structure creates both barriers and openings for challengers: scale and certification experience accelerate wins on large commercial platforms, while niche suppliers and innovators can capture aftermarket and advanced electric architecture opportunities.
Worldwide Aircraft Pressurisation Systems Market
- Honeywell Aerospace — advancing digital cabin pressure control with clear weight and reliability claims; its fourth‑generation DCPCS emphasizes brushless DC architectures and a 30% weight reduction narrative that materially alters aircraft-level tradeoffs between fuel burn and electrical load.
- Collins Aerospace (RTX) — positioning through integrated air management offerings and enhanced health‑monitoring for longer service intervals; its focus on retrofit friendliness is important for airlines seeking lower life‑cycle cost.
- Safran Group and Liebherr‑Aerospace — bring deep certification experience and test lab capabilities that reduce program risk on large transport platforms and military programs.
- ACE Thermal Systems (Signia) , Aeronamic and other emerging specialists — represent the innovation layer: automated scheduling, electric compressors and high‑speed e‑compressors aimed at more‑electric and zero‑bleed architectures.
- Moog and Parker Aerospace — focus on valves, actuators and the component ecosystem that remain strategically important to systems integrators and MROs.
Recent product activity underscores where competitive advantage is being established: Honeywell’s February 2025 DCPCS brochure refines a weight‑reduction and electrification narrative, while Collins’ May 2024 introduction of enhanced health‑monitoring systems signals a growing aftermarket and reliability‑led battleground. Suppliers investing in test capability, digital twin validation and retrofit kits are better positioned to capture near‑term upside.
Technology and regulatory dynamics shaping investment choices
- Transition to more‑electric architectures: Electric compressors and e‑CPS solutions reduce bleed‑air dependency, limiting contamination risks and enabling finer cabin‑altitude control. These technologies align with OEM goals to shrink environmental control system (ECS) weight and complexity but require new certification pathways and electrical power budgets.
- Digitalization & prognostics: Integrated cabin pressure controllers with health monitoring are extending service intervals and creating aftermarket differentiation. Systems with embedded prognostics enable outcome‑based maintenance contracts and predictable spares planning.
- Regulatory constraints and safety primacy: FAA and EASA standards (Part/CS‑25 and 14 CFR § 25.841) continue to enforce strict cabin altitude and relief‑valve redundancy requirements. Ongoing FAA research on bleed‑air contaminants elevates the compliance burden for bleed‑dependent systems and accelerates interest in non‑bleed solutions.
- Air quality and fume event mitigation: Operators and lessors are increasingly valuing designs that demonstrably reduce contamination risk or provide rapid isolation features — a trend that will influence procurement specifications and retrofit priorities in 2026 RFPs.
Practical implications by stakeholder for 2026 planning
- OEMs — Integrate electrification roadmaps with platform power budgets and certify early with regulators. Prioritize modular architectures that enable mixed fleets to adopt electric modules without extensive aircraft rework.
- Tier‑1 suppliers — Invest in digital diagnostics and certification capabilities; consider strategic partnerships with niche electric compressor innovators to accelerate platform‑ready offerings.
- Airlines & lessors — Target retrofit programs that maximize passenger perception (air quality) and operator economics (reduced maintenance and fuel tradeoffs). Demand supplier SLAs with prognostic data sharing for fleet‑level reliability modeling.
- MROs — Build competencies in electrical system maintenance and diagnostic software; retrofit service bundles will be a high‑margin growth area as operators seek lower life‑cycle costs.
- Investors & private equity — Seek targets with strong IRAD, test labs and certification track records. Favor assets that unlock recurring aftermarket revenue and those positioned for integration into more‑electric ecosystems.
Risks and mitigations for 2026
- Certification delays: Factor a 6–24 month certification risk premium into go‑to‑market timelines for electric compressors and major control system changes. Mitigate by parallel engagement with regulatory bodies and early test‑program commitments.
- Supply chain concentration: Diversify critical components and secure long‑lead items through multi‑sourcing or strategic inventory to avoid program slippage.
- Technology adoption uncertainty: Use staged investment linked to milestone gates (lab validation, flight test, certification) to manage R&D exposure.
- Regulatory shocks on bleed‑air: Model scenario contingencies for accelerated bleed‑air restrictions and identify retrofit paths for mixed fleets.
How to use this report in your 2026 planning cycle
- Set capital allocation priorities: use our ROI templates to compare retrofit vs new‑build investment cases across alternate technology scenarios.
- Refine supplier scorecards: apply the report’s vendor benchmarking to adjust procurement KPIs toward reliability, certification lead time and systems integration capacity.
- Identify quick wins: target aftermarket service bundles and retrofit kits for high‑utilization fleet types that can deliver near‑term cash flow enhancement.
- Plan M&A and partnerships: leverage the playbook to shortlist technical acquisition targets and evaluate integration risk using PW Consulting’s diligence checklist.
Conclusion & next steps
For executives preparing 2026 strategy, this sector is transitioning from component supply to system‑led offerings where software, prognostics and electrification are the primary differentiators. PW Consulting’s full report contains the granular regional and component forecasts, supplier share tables, and unit‑level economics that underpin the strategic recommendations summarized here. To access the complete dataset, proprietary supplier scorecards and the scenario model that produces the USD‑Million forecasts through 2032, please consult the PW Consulting report page or contact our advisory team for a tailored briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Pressurisation Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com