

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Rigid Thermoform Plastic Packaging Market to Expand at 5.01% CAGR, Reaching ~USD 76.85 Billion by 2032

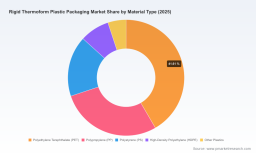
Worldwide Rigid Thermoform Plastic Packaging Market — Strategic Outlook for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Rigid Thermoform Plastic Packaging Market provides a practical, boardroom-ready intelligence package designed to influence capital allocation, commercial strategy, and regulatory response throughout 2026. Anchored on a 2025 base year and a robust forecasting framework through 2032, the analysis identifies where value will concentrate, how cost and regulatory dynamics will shift economics, and which competitive plays will unlock disproportionate returns. The headline: the global market, having expanded steadily in recent years, is forecast to continue growing at a compound annual growth rate (CAGR) of 5.01% across the 2026–2032 horizon—presenting both predictable runway and pockets of strategic disruption for investors and operators alike.
Worldwide Rigid Thermoform Plastic Packaging Market
Why this report matters in 2026
-
Decisive year for regulation and EPR implementation — With new rules coming into effect across major jurisdictions in 2026, packaging producers and brand owners must translate compliance obligations into operational targets and product roadmaps.
Worldwide Rigid Thermoform Plastic Packaging Market -
Input-cost volatility compresses margins — Feedstock and resin price fluctuations have reintroduced short-to-medium-term margin risk; commercial teams need granular cost models and indexed pricing strategies to protect profitability.
Worldwide Rigid Thermoform Plastic Packaging Market -
Fragmented supplier landscape — Market concentration metrics demonstrate a fragmented competitive set, which creates opportunities for roll-ups, strategic partnerships, and localized differentiation.
-
Acceleration of sustainable thermoforms — Innovations in recyclable APET, PET sheets for pharmaceutical use, and mono-material designs are reshaping product development and procurement criteria for major buyers.
Macro trajectory and practical implications
PW Consulting’s time-series model shows a clear upward trajectory from historical years into our forecast window. The market’s steady expansion, underpinned by foodservice demand, healthcare and medical packaging needs, and growing consumer convenience trends, creates a predictable top-line environment for 2026 planning. However, the headline growth masks actionable variability: regional regulatory timing, local recycling infrastructure, and raw material price swings will materially alter unit economics and sourcing choices.
For 2026, the practical implications are threefold: (1) procurement teams must build short-cycle hedging and supplier scorecards tied to resin indices; (2) R&D and product teams should prioritize designs that marry recyclability with cost parity; (3) corporate development should actively evaluate M&A targets to gain scale in high-growth subsegments or to access niche pharma/medical certifications.
Market dynamics shaping 2026 strategies
-
Regulatory inflection points — European packaging regulation changes, implemented in 2025 and phasing in through 2026, increase obligations for recyclability, minimum recycled content and extended producer responsibility (EPR). Parallel developments in North America see an expanding patchwork of state-level EPR schemes. These impose upstream financial responsibility on producers and will drive demand for validated recycled-content solutions and traceable material streams.
-
Raw material pressure — Resin market behavior in early 2026 is a critical near-term determinant of margin. Polypropylene and polystyrene pricing show regional dispersion and volatility, influencing material selection strategies and prompting investment in cost-to-serve analytics and alternative material trials.
-
Recycling and standards debates — Thermoformed PET items are under active policy review in several jurisdictions, including discussions on how they should be categorized within recycling lists. This regulatory uncertainty creates both risk and strategic opportunity for companies able to secure early recyclability certifications and chain-of-custody claims.
-
Customer and brand pressure — Major consumer brands continue to demand higher recycled content and improved end-of-life outcomes. Thermoform suppliers that can demonstrate validated circularity pathways will capture preferential sourcing relationships.
Competitive landscape: players, positioning, and strategic moves
The sector remains competitively diverse, with global leaders co-existing alongside specialized regional and niche players. Market concentration levels underscore a fragmented market: the top three and top five firms hold meaningful but limited shares, leaving ample room for differentiation and consolidation.
-
Global integrators — Firms with global footprint and broad product platforms are leveraging scale to invest in recycling technology, medical-grade qualification, and rollstock solutions. Recent product launches focused on APET and medical-grade rollstock signal a push toward higher-value, regulated segments.
-
Foodservice specialists — Established producers in foodservice packaging continue to optimize cost and manufacturing footprint, while selectively piloting sustainable alternatives and mono-material conversions to meet brand commitments.
-
Custom and niche thermoformers — Smaller manufacturers maintain competitive advantage through speed-to-market, customization, and specialized certifications for pharma and medical device packaging. These businesses are attractive targets for larger buyers seeking capability uplift.
Notable recent industry developments illustrate these themes. For example, a global packaging leader launched APET-based thermoformed trays and rollstock tailored for healthcare and pharmaceutical customers, emphasizing enhanced recyclability and cost efficiency. Separately, product expansions in PET sheet grades for pharmaceutical blister and unit-dose formats demonstrate how material innovation is responding to regulatory and clinical needs. These moves foreshadow where winning product strategies will sit in 2026: technically validated, regulation-aligned, and commercially scalable.
What PW Consulting’s report delivers — practical components for 2026 execution
This study was constructed for decision-makers who need executable insights, not academic theory. The report includes:
-
Executive strategic playbooks — Action checklists for procurement, product development, regulatory compliance, and commercial teams calibrated for 12–36 month horizons.
-
Scenario-driven financial models — Base, upside, and downside cases that translate resin cost swings, recycled-content mandates, and EPR fees into P&L and free-cash-flow outcomes.
-
CapEx and footprint optimization tools — Manufacturing line economics, return-on-investment calculators for conversion to recyclable substrates, and a heat-map to prioritize retrofit vs. new-build decisions.
-
Segment and application playbooks — Go-to-market templates for foodservice, healthcare, electronics, and personal care (note: detailed segment-level forecasts and regional splits are included in the full report; this release highlights strategic directions while preserving proprietary values to encourage direct access to the source).
-
Supply-chain stress tests — Supplier scorecards, dual-sourcing frameworks, and short-term hedging strategies that reduce exposure to resin price volatility.
-
M&A and partnership roadmaps — Target archetypes, valuation benchmarks, and integration playbooks for buyers seeking scale or specialization.
-
Regulatory compliance checklists — Jurisdiction-by-jurisdiction impact assessments and stepwise compliance timelines for EPR and packaging waste rules relevant to 2026.
How leaders should translate insight into decisions in 2026
-
Procurement: adopt index-linked contracts where available, implement short-cycle buy/sell analytics, and expand qualified supplier lists for recycled-content feedstocks.
-
R&D and product development: prioritize mono-material designs and validated recycled-content solutions that meet emerging certification requirements; accelerate qualification for pharma-grade PET sheets where demand is rising.
-
Commercial teams: reprice channels where cost-to-serve has changed materially; work with brand-customers to co-invest in validated recycling streams that reduce EPR exposure.
-
Corporate development: pursue tuck-ins that add certification capability or regional scale; use market fragmentation to secure attractive valuations for roll-up strategies.
Final perspective — a “trailer” that points to decisive detail
For 2026, the market offers a balance of steady growth and targeted disruption. The top-line trajectory is attractive and predictable, but the real value will accrue to companies that can operationalize recyclability, manage feedstock volatility, and navigate accelerating regulatory frameworks. PW Consulting’s report equips executives with the tactical playbooks, quantitative scenarios, and supplier-to-shelf tools needed to convert market dynamics into measurable advantage.
If your 2026 capital plans, product roadmaps or M&A pipeline are on the table this quarter, this study provides the evidence-based guidance you need to move from intent to action. The full report contains the complete set of segment-level forecasts, regional splits, proprietary pricing models, and downloadable implementation templates referenced above. Access to these proprietary exhibits is available on the report’s source webpage—our recommended next step for teams building a defensible 2026 plan.
For detailed analysis of this topic, please visit the official page: Worldwide Rigid Thermoform Plastic Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com