

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecasts Worldwide Over‑the‑Horizon Radar Market to Reach USD 1,753.6 Million by 2032, Expanding at a 6.5% CAGR

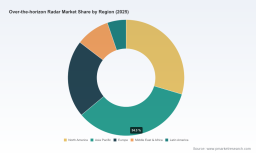
Worldwide Over-the-horizon Radar Market — Strategic Briefing for 2026 Decision‑Makers
Executive summary
PW Consulting’s new market study on the Worldwide Over‑the‑horizon (OTH) Radar Market delivers an evidence‑based, operationally oriented playbook for defense planners, prime contractors, and national procurement teams planning decisions in 2026. The global OTH radar market has expanded materially over the past half‑decade — growing from roughly USD 825 million in 2020 to an estimated USD 1,128 million (USD Million, base year 2025). Under the scenarios modeled in this report, the market resumes growth across the 2026–2032 forecast window at a compound annual growth rate (CAGR) of 6.5%, reaching roughly USD 1,754 million by 2032. That trajectory reflects a combination of defense modernization spending, new Arctic and Indo‑Pacific sensor deployments, and a wave of technology refresh and sustainment programs.
Worldwide Over-the-horizon Radar Market
Why this report matters for 2026
-
Timing: The coming 12–24 months are decisive. Several national programs are transitioning from concept and environmental review into procurement and construction phases; decisions taken in 2026 will lock in supplier ecosystems and platform architectures for a decade.
Worldwide Over-the-horizon Radar Market -
Investment focus: Governments are prioritizing long‑range, passive and active HF solutions to close gaps in northern approaches, maritime domain awareness, and strategic ballistic‑missile early warning. These programs translate into capital procurement, long‑term operations & maintenance (O&M) contracts and recurring upgrade budgets.
Worldwide Over-the-horizon Radar Market -
Technology inflection: Advances in digital beamforming, software‑defined radar, AI‑assisted signal processing, and modular open systems are changing the cost profile and upgrade cadence of OTH capabilities. Firms that align product roadmaps with these trends will capture higher lifecycle value.
Market dynamics driving demand
-
Geopolitical drivers: Renewed emphasis on continental and maritime approaches—particularly in Arctic and Indo‑Pacific theaters—has accelerated program planning by key NATO members and Pacific partners. Multinational technology transfer and partnership models (including cross‑government licensing of proven OTH architectures) are becoming the norm for rapid capability delivery.
-
Modernization and sustainment: Legacy networks are receiving a dual mandate—extend life through hardware upgrades while introducing software‑defined features that enable multi‑mission sensing, data fusion, and cyber‑resilience. This creates balanced demand across new system procurements and high‑value O&M workstreams.
-
Infrastructure and regulatory constraints: Site selection, environmental reviews, and spectrum coordination are material gating items. Several programs anticipated to move from planning to construction will require integrated project management capabilities that combine civil works, RF engineering, and stakeholder engagement.
-
Operational doctrine: Doctrine shifts toward integrated sensor networks and all‑domain awareness increase the premium on interoperability, common data models, and secure high‑bandwidth links between OTH assets and national command networks.
Competitive landscape — what procurement teams should read into it
The competitive structure of the OTH radar market is moderately concentrated: the top three incumbents control a substantial share of the market, while the top five capture a solid majority. That concentration favors established primes with systems integration track records, long histories of lifecycle support, and full‑stack capabilities (antennas, transmit subsystems, signal processing, and long‑duration O&M). Key industry actors include RTX Corporation (Raytheon), Lockheed Martin, Northrop Grumman, BAE Systems, Thales, Leonardo, Saab, Israel Aerospace Industries, and Aselsan.
-
Prime integrators: Firms with decades of OTH experience continue to win sustainment and upgrade work because they combine fielded test data, integrated logistics, and field operations teams. Their offers increasingly emphasize software upgradability and modular transmit/receive blocks to speed deployed improvements.
-
Regional system suppliers: European and regional suppliers are positioning specialized software, control systems, and HF surface‑wave elements as complementary offerings—particularly where sovereign supply chains or local content requirements drive procurement choices.
-
New suppliers and subsystems: Specialist suppliers are capitalizing on transmit‑subsystem and high‑power amplifier contracts associated with homeland defense programs. Contracting activity in early 2026 demonstrates a healthy market for subsystem builders as much as for full systems integrators.
Notable program and policy developments (contextual highlights)
-
High‑profile national programs are advancing from planning to execution, including Arctic and homeland defense OTH initiatives that explicitly reference technology partnerships and previously proven architectures. These programs are shaping demand signals for construction, transmit hardware, and long‑term sustainment.
-
Recent award activity in early 2026 shows both large O&M contracts and significant transmit‑subsystem procurements moving through defense acquisition pipelines—an indicator that both new builds and refresh cycles will contribute to market growth.
-
Regulatory timelines—environmental reviews, spectrum allocation, and construction approvals—are critical program dependencies. Procurement schedules that underestimate these steps risk schedule slippage and cost escalation.
Strategic imperatives for 2026 decision‑makers
Our research translates into eight practical priorities that should guide boardrooms and procurement offices this year:
-
Adopt lifecycle cost thinking: Evaluate proposals not only on acquisition price, but on 20‑ to 30‑year sustainment cost, software upgrade paths, and obsolescence risk. OTH systems deliver value through decades of operation—O&M terms are often where contracts create or destroy value.
-
Prioritize modular, software‑defined architectures: Insist on open‑architecture baselines and clear upgrade interfaces. This reduces vendor lock‑in and accelerates insertion of AI‑assisted signal processing and spectral management capabilities.
-
Lock in interoperability early: Define data and interface standards during RFP development. Programs that delay data standardization pay integration penalties during fielding and cross‑domain operations.
-
Factor environmental and permitting risk into schedule and cost: Build contingency for multiyear environmental reviews and community engagement in remote locations, particularly in Arctic and coastal sites.
-
Design for sovereign industrial participation: If domestic industrial benefits are required, structure contracts to phase capability handover and partner training, reducing risk while growing local sustainment capacity.
-
Stress‑test supply chains: High‑power RF components and civil works are potential chokepoints. Early vendor qualification and multi‑source strategies reduce schedule risk.
-
Plan for integrated resilience: Include cyber, EMI/EMCON, and anti‑spoofing requirements as part of the procurement baseline; secure command and control links are as critical as the radar apertures.
-
Use scenario‑based procurement: Procure with scenarios in mind (e.g., Arctic persistent surveillance, ballistic missile early warning, dark‑water maritime detection). Tailor acceptance tests to operationally relevant cases rather than lab metrics alone.
What PW Consulting’s report delivers (practical contents)
This study is designed to be prescriptive, enabling buyers and suppliers to act in 2026 with greater confidence. Core deliverables include:
-
A calibrated market model covering historical (2020–2025) performance and scenario‑based forecasts for 2026–2032 with sensitivity testing under alternative geopolitical and budgetary assumptions.
-
Vendor ecosystem maps and capability heatmaps that profile system integrators, specialty subsystem suppliers, and regional partners—scored against lifecycle support, modularity, and interoperability metrics.
-
A procurement playbook and RFP checklist that embeds requirements for open architecture, sustainment metrics, spectrum coordination, environmental compliance, and local‑industry participation.
-
Operational acceptance templates and test‑case libraries keyed to coastal surveillance, long‑range air surveillance, and early missile‑warning missions.
-
A contract‑readiness toolkit for governments and primes (including O&M contracting approaches, warranty structures, and handover schedules) to reduce delivery risk and cost overruns.
-
Scenario briefs and decision trees for planners evaluating when to procure, upgrade, or retain legacy OTH assets versus investing in alternative long‑range sensing architectures.
Concluding perspective
For organizations making allocation decisions in 2026, the OTH radar market presents both continuity and change. Continuity comes from sustained defense demand for long‑range awareness and the enduring value of fielded systems. Change comes from a confluence of geopolitics, modular software platforms, and a stronger emphasis on lifecycle sustainment and interoperability. PW Consulting’s study converts these dynamics into operational guidance: a quantified market view, procurement tools, vendor diagnostics, and practical decision frameworks to support executable plans.
Next steps
PW Consulting is publishing an executive briefing and an extended dataset that include full segmentation, detailed company profiles, and the interactive forecast model. The public summary above is intended to equip 2026 decision‑makers with the strategic context they need; the full report contains the granular inputs, supplier scorecards, and scenario models necessary to finalize procurements and supplier strategies. Visit our report page to access the complete deliverables and to request tailored advisory support for your program timeline.
For detailed analysis of this topic, please visit the official page: Worldwide Over-the-horizon Radar Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com