

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
Radiation Shielding Textile Market: Why 5.1% CAGR and Asia Pacific’s 32% Share Redefine Growth
By pmarketresearch, 2026-09-21
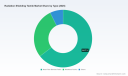
Radiation Shielding Textile Market: Strategic Trends & Commercial Opportunities (2026–2032)
Market Landscape & Core Challenges
The global market for radiation shielding textiles is navigating a phased expansion, with revenue scaling from approximately $70 million in 2020 toward a $130 million horizon by 2032. This trajectory reflects a compound annual growth rate of roughly 5.1% across the 2026–2032 forecasting window, signaling steady rather than explosive momentum. The market’s maturation is less about raw volume growth and more about structural refinement: demand is shifting from generic protective coveralls toward engineered, application-specific textiles that balance shielding performance, ergonomics, and compliance readiness.
Worldwide Anti Radiation Clothing Market
Several structural challenges complicate this progression. First, the tension between shielding effectiveness and wearable practicality remains unresolved for many end-use scenarios. High-attenuation materials often carry weight, stiffness, or thermal discomfort penalties that limit adoption in prolonged-contact applications, particularly in healthcare and specialized industrial settings. Second, regulatory complexity is accelerating material substitution cycles. Restrictions on certain chemical substances in textiles, combined with tightening requirements for personal protective equipment certification, are forcing manufacturers to validate not only shielding performance but also chemical safety and durability under repeated use. Third, input cost volatility is reshaping margin architectures. Fluctuations in base metals and specialty concentrates feed directly into the cost structures of metallized and blended shielding fabrics, while trade policy shifts have introduced new friction into cross-border sourcing and finished-goods distribution.
For decision-makers, the immediate implication is clear: the market is moving from a commodity-adjacent phase toward a performance-differentiated phase. Companies that treat shielding textiles as a spec-driven engineering problem rather than a volume play will capture disproportionate value as procurement teams standardize on verified durability, certification status, and lifecycle cost.
Key Drivers Reshaping the Market
Materials Innovation and Functional Differentiation
Material architecture is the most visible lever of competitive differentiation. Metal fiber blended fabrics continue to anchor a significant share of the market because they offer an established balance of conductivity, washability, and manufacturability. Metallised fabrics, particularly silver-plated and metal-coated variants, remain central for electromagnetic shielding in technical textiles and electromagnetic compatibility applications. At the same time, lead-free and lightweight shielding approaches are gaining strategic relevance, especially where ionizing radiation protection intersects with ergonomics and repeated occupational exposure. The commercial appeal of these innovations is not merely technical; it is operational. Textiles that maintain shielding integrity through repeated flexing, laundering, and environmental exposure reduce replacement frequency and simplify compliance documentation, which matters increasingly in regulated procurement environments.
Regulatory and Certification Pressures as a Market Filter
Regulation is functioning as both a constraint and a competitive filter. In the European market, restrictions on certain substances in clothing, textiles, and footwear have raised the bar for chemical compliance in shielded products, while broader chemical action plans are extending scrutiny toward technical textiles and associated surface treatments. Parallel certification requirements for personal protective equipment are pushing manufacturers to substantiate claims with reproducibility data rather than laboratory benchmarks alone. This dynamic favors firms that can assemble a credible documentation package—material composition, durability evidence, and application-specific validation—because procurement and risk functions increasingly treat certification as a gatekeeping criterion rather than a back-office detail.
Demand-Side Shifts in Occupational and Medical Settings
Demand patterns are being reshaped by how protective textiles are used day to day. In medical environments, there is growing emphasis on localized shielding solutions that reduce dose exposure without imposing the burden of full-body garments for every procedure. This has encouraged development of targeted protection devices and modular textile systems that can be deployed where exposure risk is concentrated. Beyond healthcare, industrial users continue to seek shielding materials that integrate into existing workflows without disrupting dexterity, ventilation, or maintenance routines. At the consumer-adjacent end, interest in maternity and general anti-radiation apparel has expanded awareness of shielding textiles, though commercial scale in that segment depends heavily on perceived benefit, affordability, and repeat-purchase dynamics. Across these settings, the common thread is a preference for solutions that marry protection with usability.
Supply Chain Economics and Input Cost Exposure
Cost structure is becoming a strategic variable rather than a background condition. Stabilized pricing across lead markets has provided some predictability for traditional shielding inputs, but that stability does not extend uniformly to all materials. Sharp increases in tungsten concentrate pricing illustrate how quickly input economics can shift for alternative high-density shielding paths, affecting the feasibility of specific formulations and pushing teams to reassess blending ratios, sourcing diversification, and inventory planning. At the same time, tariff escalations on textiles and related imports in major markets have raised the effective cost of cross-border supply chains, prompting manufacturers to reconsider where value-added processing occurs and how finished goods are routed. The result is a market in which resilient sourcing strategies and regional production flexibility are becoming part of the competitive advantage set.
Competitive Landscape & Leading Strategies
The competitive field is moderately concentrated, with the largest players collectively accounting for a meaningful but not suffocating share of revenue. That structure leaves room for specialized innovators while rewarding established manufacturers that can scale certification, consistency, and application engineering. A few strategic positions stand out.
- Swiss Shield AG has built its position around high-tech yarns and cotton/polyester fabric systems designed for high-frequency electromagnetic radiation shielding, with product lines spanning garments, home textiles, and industrial applications. Its strategic emphasis appears to be on embedding shielding capability into familiar textile substrates, which can simplify integration for downstream manufacturers and reduce adoption friction.
- Shieldex focuses on metallized silver-plated fabrics and conductive textiles available in woven, knitted, and nonwoven forms, targeting technical textiles and electromagnetic compatibility applications. This breadth of fabric construction supports customization for different performance and handling requirements, which is valuable in application-driven procurement.
- Radiation Shield Technologies (RST) occupies a distinctive niche as the sole producer of a lead-free, lightweight radiation protection fabric designed for ionizing radiation shielding in full-body suits, blankets, vests, and tents. Its differentiation rests on material uniqueness and the ability to offer an alternative to conventional heavy shielding approaches, which can be compelling where weight, comfort, and portability influence adoption.
- Texray AB has positioned itself around textile-based radiation protection devices for medical professionals, supported by regulatory certifications and recent durability validation. Independent scientific study results have highlighted resistance to high numbers of flex cycles and substantial additional dose reduction in medical applications, reinforcing a value proposition centered on long-service performance rather than single-use protection logic.
- Joyncleon addresses lightweight maternity and general anti-radiation apparel using high-performance fabrics, illustrating how shielding textiles can extend into consumer-facing apparel categories where comfort, style, and accessibility shape purchase decisions.
- Metal Textiles contributes metal-coated and metallized fabric capabilities for radiation and electromagnetic shielding, reinforcing the broader ecosystem of metallization-based solutions that serve industrial and technical use cases.
The strategic throughline across these players is differentiation through either material architecture, application specialization, or validation depth. Companies that compete mainly on specification sheets are vulnerable to those that can demonstrate durable field performance and maintain compliance readiness across jurisdictions. One notable recent development underscores this direction: Texray AB’s 2025 certification-related progress, including study-confirmed durability against extensive flex cycling and up to 97% additional dose reduction in medical applications, signals how performance evidence can strengthen positioning in regulated, high-stakes settings.
Looking ahead, the competitive landscape is likely to evolve along two tracks. On one hand, consolidation may accelerate among manufacturers that can combine material expertise with compliance, distribution, and application support. On the other, new entrants may emerge around targeted niches—localized medical shielding, lightweight alternatives for specific occupational tasks, or specialized electromagnetic shielding for technical textiles—where incumbents are less optimized. The dividing line will be whether a company can offer a repeatable, verifiable solution that fits into a procurement process, not merely a promising material concept.
Outlook & Emerging Opportunities, 2026–2032
The next several years are likely to be defined by three interlocking trends.
1. From shielding presence to shielding performance. Demand will increasingly center on textiles that prove durable under real use conditions, not just on initial attenuation numbers. Products that can demonstrate repeated flex endurance, wash stability, and consistent performance after deployment will command stronger preference in medical, industrial, and military-adjacent settings. The commercial opportunity lies in building product narratives around lifecycle value: fewer replacements, more predictable protection, and simpler audit trails for compliance teams.
2. Material substitution and formulation arbitrage. As regulatory expectations tighten and input costs move unevenly across metals and concentrates, manufacturers that can adjust formulations without sacrificing core performance will gain flexibility. This creates opportunities for blended systems, alternative metal choices, and lead-free options where they can meet shielding and usability thresholds. The flip side is supply-chain risk: pricing swings in key inputs can quickly alter cost competitiveness, so scenario planning and multi-source sourcing will matter more than in a stable-commodity environment.
PW Consulting Health Care Research Center
3. Application-led segmentation rather than blanket categories. Buyers are likely to adopt more granular purchasing logic, selecting textiles by end-use rather than by broad category. Medical localized protection, industrial electromagnetic compatibility, and lightweight occupational shielding each present different engineering and certification requirements. Companies that organize product lines around these use cases—and support them with relevant documentation and integration guidance—are better positioned to capture share in higher-value segments.
Potential risks and uncertainties should be factored into planning. Certification pathways can shift, especially where chemical restrictions and PPE requirements evolve. Trade policy volatility can alter landed costs and redirect sourcing strategies, particularly for manufacturers dependent on cross-border material flows or finished-goods distribution. Durability claims, if not substantiated consistently, can become a liability in regulated procurement. Finally, where consumer-facing shielding products rely heavily on perceived rather than measured benefit, adoption may be sensitive to competitive alternatives and price expectations.
Worldwide Fibers and Electromagnetic Shielding Market
Strategic Implications for Decision-Makers
For manufacturers, the priority is to align product development with verifiable durability and compliance readiness. Engineering effort should be directed toward formulations and fabric constructions that hold up under repeated flex, laundering, and operational stress, because those attributes increasingly influence purchasing decisions in regulated settings. It is equally important to prepare documentation that supports certification and procurement review, since the ability to demonstrate reproducible performance can be as valuable as the raw shielding specification. Diversification of input sourcing and regional manufacturing flexibility will help manage cost and trade-related disruptions.
For investors, attention should focus on companies with defensible differentiation in either material architecture, application specialization, or validation depth. Business models that depend on undifferentiated volume in a moderately concentrated market face more competition and thinner margins, while those tied to certified, application-specific solutions have stronger moats. Due diligence should assess input cost exposure, regulatory preparedness, and the credibility of durability claims, because these variables will shape profitability as the market moves from early expansion toward more performance-driven competition.
For procurement and end-user organizations, the practical move is to define shielding requirements by application and to evaluate suppliers against a broader scorecard that includes durability evidence, certification status, chemical compliance, and total cost of ownership. Selecting textiles on the basis of initial attenuation alone can leave exposure to premature degradation, replacement costs, and compliance gaps. Establishing internal acceptance criteria for field performance and documentation will improve consistency across purchases and reduce downstream risk.
As the radiation shielding textile market continues to refine its value proposition around performance, compliance, and application fit, the companies and buyers that act on those priorities early are best positioned to capture the upside of the forecast period. For teams that need a deeper, segment-level view of sizing, competitive positioning, regional dynamics, and material-cost exposure to guide planning, the full PW Consulting market report provides the detailed data foundation and tailored strategic options to support those decisions.
For detailed analysis of this topic, please visit the official page: Radiation Shielding Textile Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Laminated Tubes Market Beyond the 6.5% CAGR: Key Drivers Shaping 2032 Growth
By pmarketresearch, 2026-09-21
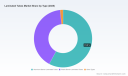
Strategic Shifts and Commercial Opportunities in the Laminated Tubes Market
The global laminated tubes market has demonstrated steady, compounding growth over the past five years, with revenue expanding from $1,345.0 million in 2020 to $1,810.0 million in 2025. Forward projections indicate this trajectory will continue through the forecast period of 2026-2032, reaching $2,800.0 million by the end of the decade. The implied compound annual growth rate of 6.5% reflects more than baseline demographic expansion; it signals a structural transition where laminated tubes are increasingly evaluated not merely as dispensing packages, but as functional components within product performance, regulatory compliance, and sustainability narratives.
Leadership teams across personal care, oral care, pharmaceuticals, and food and beverage sectors are navigating a landscape where packaging decisions directly influence formulation integrity, brand positioning, and supply chain risk exposure. The market's expansion is not uniform. It is concentrated around innovation cycles, regulatory inflection points, and geographic rebalancing that reward manufacturers and brand owners who align capacity investments with material science breakthroughs. Understanding where growth concentrates, what constraints will harden, and which competitive moves are gaining traction is essential for strategic planning in the near to medium term.
Market Landscape and Emerging Pressure Points
The laminated tubes market operates with moderate concentration, where the top three players capture approximately 26.8% of revenue and the top five reach about 32.6%. This structure indicates a competitive environment with a stable core of established manufacturers and sufficient space for regional specialists and technology-driven entrants to differentiate. Growth has been consistent year over year, with 2024 revenue reaching $1,701.4 million and 2025 closing at $1,810.0 million. The momentum continues into 2026 at $1,955.44 million, reflecting sustained demand across core application categories and incremental gains from higher-value barrier solutions.
Several structural tensions are defining the current phase of market development. First, the cost architecture of laminated tubes remains inherently higher than conventional single-material alternatives. Multilayer construction, specialty adhesives, and barrier films such as aluminum foil or engineered resins create a production cost premium typically 15-20% above standard polyethylene tubes. When resin prices experienced 30-40% spikes between 2021 and 2023 due to supply chain bottlenecks, the margin pressure on laminated tube manufacturers intensified, forcing a sharper focus on value engineering, procurement discipline, and pricing strategies that justify premium positioning through performance and compliance.
Second, regulatory momentum is reshaping design assumptions. Packaging legislation in major markets is moving from voluntary guidelines toward enforceable standards that link material composition, recyclability, and recycled content to market access. This shift places laminated tube manufacturers and brand owners under pressure to reconcile barrier performance with end-of-life compatibility, particularly in regions where existing recycling infrastructure is calibrated for simpler polymer streams.
Third, the market is encountering a capability gap between high-volume standard production and the growing demand for customized, high-resolution printed, and functionally specialized tubes. As brands seek packaging that supports premium positioning, tamper evidence, anti-counterfeiting, and differentiated dispensing experiences, manufacturers that can deliver consistent quality at scale while accommodating shorter runs and tailored specifications are gaining strategic relevance.
Drivers Reshaping Market Trajectory
Material Innovation and Barrier Performance
Technology advancement remains the most direct engine of market growth. Laminated tube value is increasingly derived from the ability to combine barrier protection, lightweighting, and recyclability in a single structure. High-barrier aluminum-based laminate tubes continue to command significant share because they protect oxygen-sensitive and moisture-sensitive formulations, but innovation is expanding the functional envelope of plastic barrier solutions as well. Recent product launches demonstrate that barrier performance is no longer treated as a fixed attribute; it is being re-engineered for compatibility with recycling streams while retaining the protective characteristics demanded by oral care, cosmetics, and pharmaceutical applications.
Examples include the introduction of recyclable high-barrier laminate tubes designed for oral care and cosmetics, the debut of mono-material recyclable barrier tubes with sensory and aesthetic differentiation, and the integration of anti-counterfeiting features directly into multilayer tube structures through holographic films. These developments matter commercially because they allow brand owners to defend formulation quality and consumer trust without defaulting to conventional aluminum structures that may face recyclability friction in certain jurisdictions. For manufacturers, the ability to offer differentiated barrier solutions is increasingly a revenue driver rather than a compliance checkbox.
Regulatory and Policy Dynamics
Policy environments are accelerating design transitions. In Europe, packaging regulation is moving toward enforceable recycled content thresholds and harmonized recyclability grading. Flexible packaging is subject to mandates requiring at least 35% recycled plastic content by 2030, which compels laminated tube producers and their customers to adapt structures for recyclability in existing polyethylene streams. Enforcement of single-use plastics requirements since mid-2024 has reinforced expectations around tethered closures and mono-material orientation, further accelerating the shift away from complex multi-layer laminates where recycling compatibility is limited.
Laminate Tube Packaging Market
By 2026, technical implementing acts are expected to impose harmonized recyclability grades, creating a more predictable but stricter evaluation framework. Manufacturers that rely on laminated films incompatible with existing recycling systems face increased redesign exposure, while those with mono-material or certified recyclable platforms gain a compliance advantage. This regulatory trajectory is not solely a European phenomenon; it influences global supply chains as multinational brand owners standardize packaging architectures across regions to reduce complexity and risk. The strategic implication is clear: regulatory readiness is becoming a market entry and retention factor, especially in premium personal care and pharmaceutical segments.
Demand-Side Evolution in Consumer and B2B Behavior
Consumer and enterprise demand is pulling laminated tube markets in two complementary directions. On the consumer side, expectations around sustainability, authenticity, and premium experience are influencing purchasing decisions in oral care and cosmetics. Tubes are no longer invisible carriers; they communicate brand values through finish, dispensing feel, and perceived environmental responsibility. On the B2B side, pharmaceutical and personal care manufacturers are seeking packaging that supports product integrity, regulatory documentation, and supply reliability. High-barrier laminated tubes serve these needs by protecting active ingredients, enabling stable shelf life, and providing a platform for controlled dispensing.
This dual demand pattern is expanding the commercial relevance of specialized tube formats. Oral care remains a particularly strong application category, benefiting from high usage frequency, brand loyalty, and format familiarity. Cosmetics and personal care continue to drive demand for customizable prints, premium tactile qualities, and functional closures. Pharmaceuticals and healthcare-related applications contribute steady demand where barrier protection and compliance documentation are critical. The underlying trend is that laminated tubes are being selected for a wider set of performance criteria, which raises the stakes for manufacturers that cannot deliver consistent quality, traceability, and specialized features.
Supply Chain Economics and Cost Structure Realignment
Cost dynamics are a persistent determinant of competitive positioning. Laminated tube economics are shaped by resin pricing, aluminum foil costs, adhesives, and multilayer processing complexity. The resin price volatility experienced during 2021-2023 illustrated how quickly input cost swings can compress margins, particularly for producers with limited ability to pass through costs or re-engineer structures for efficiency. As markets stabilize, the strategic focus is shifting toward cost resilience rather than short-term price hedging alone.
Capacity expansion is one response. Investments in automated production lines in key manufacturing hubs are increasing throughput and reducing per-unit labor intensity, which helps offset structural cost premiums. At the same time, manufacturers are pursuing lightweighting, material optimization, and hybrid technologies that preserve barrier performance while reducing overall material usage. These moves are not only about margin protection; they are increasingly tied to sustainability messaging and recyclability performance, creating a link between cost efficiency and market acceptance.
Competitive Landscape and Strategic Positioning
The competitive environment is defined by a mix of global manufacturers with broad application coverage and regional specialists with strong customization or cost advantages. A handful of scaled players set the pace on innovation and capacity, while a wider field competes through regional service, printing quality, pharmaceutical compliance capabilities, and application-specific expertise. Strategic differentiation is increasingly tied to three dimensions: recyclable barrier technology, capacity scale with automation, and the ability to support premium branding through high-resolution graphics and custom formats.
Several leaders illustrate how these dimensions are being pursued. Essel Propack Limited has built a broad manufacturing footprint with facilities across multiple countries and a focus on high-volume aluminum and plastic barrier tubes spanning oral care, cosmetics, food, and pharmaceutical products. Its recent investment of approximately $35 million in automated production lines reflects a strategy centered on capacity growth and operational efficiency in a major manufacturing region. Albea S.A. has positioned itself around recyclable tube platforms with advanced barrier technologies, including high-barrier recyclable laminate solutions intended for oral care and cosmetics. This emphasis on recyclability and barrier performance aligns with the regulatory and consumer pressures shaping European and global markets.
Amcor Limited has emphasized ultra-lightweight and post-consumer resin-based laminated tubes for personal care and pharmaceutical use, with a stronger narrative around circular packaging models and targeted market launches in Europe. Huhtamaki Oyj has moved into paper-based bio-barrier laminated tubes for personal care and cosmetics, supported by recyclability certifications, signaling a bet on alternative material pathways that reduce dependence on conventional plastics and aluminum in specific applications. Berry Global Group, Inc. has invested in patented hybrid technology designed to support high-resolution, premium graphic laminated tubes for cosmetic and pharmaceutical applications, reinforcing a premiumization and visual differentiation angle. Hoffmann Neopac AG has focused on recyclable mono-material barrier tubes with pharmaceutical-grade manufacturing standards, expanding capacity in North America and introducing sensory-oriented recyclable barrier options for cosmetics.
Beyond these global players, regional manufacturers play an important role in the market's architecture. Asian producers frequently serve cosmetics, skincare, and personal care demand with custom aluminum and plastic barrier tubes and strong printing capabilities, while North American and European specialists often compete on pharmaceutical compliance, documentation support, and premium healthcare-oriented formats. This diversity means that competitive advantage is not simply a function of scale. It is increasingly determined by the ability to match the right material platform, regulatory posture, and service model to the application.
The market structure suggests continued differentiation rather than rapid consolidation. The top firms maintain a meaningful but not dominant share, enabling niche leaders to thrive where they offer clear functional or compliance advantages. At the same time, the pace of technology introduction and regulatory change is raising the bar for new entrants and smaller players. Manufacturers without recyclable platforms, reliable barrier performance, or scaling automation may find it harder to compete in premium segments, while those able to deliver specialized print quality, anti-counterfeiting features, or pharmaceutical documentation may capture value in higher-margin niches.
Forward Outlook: Trends Shaping the Next Three to Five Years
The next phase of laminated tube market development is likely to be shaped by the interaction of recyclability mandates, premiumization, and manufacturing efficiency. Three trends stand out.
Recyclable barrier architectures will become a baseline expectation in key markets. As harmonized recyclability grading and recycled content requirements take hold, the market will increasingly reward tube structures that balance protection with compatibility in existing recycling streams. This will intensify redesign activity for multi-layer laminates and create durable demand for mono-material and certified recyclable solutions. The commercial opportunity is not limited to compliance; recyclable barrier tubes can support brand narratives and procurement requirements that are becoming standard in multinational purchasing decisions.
Laminated Steel Market
Premium differentiation will expand through graphics, sensory design, and security features. High-resolution printing, hybrid graphic technologies, and integrated anti-counterfeiting features are moving from specialty projects to broader commercial relevance. Brands in cosmetics and oral care are using packaging to reinforce premium positioning and consumer trust, while pharmaceutical and personal care buyers are looking for solutions that reduce risk and support product authenticity. Manufacturers that can deliver these features consistently at scale will capture higher-value demand.
Capacity growth will concentrate where automation and material access align. Investments in automated lines and regional production expansion are likely to continue, particularly in markets that combine cost efficiency with strong application demand. This will improve throughput and cost resilience but will also raise the operational standard for competitiveness. Suppliers that remain dependent on labor-intensive processes or lack material and printing specialization may face margin compression and reduced access to premium programs.
These trends carry uncertainty. Regulatory timelines and enforcement intensity may vary by region, affecting how quickly recyclable structures become commercially mandatory. Resin and aluminum pricing can still disrupt margins if supply constraints re-emerge. In addition, alternative packaging formats and refill systems may influence demand patterns in certain categories, particularly where brand owners pursue circularity through reusable or reduced-packaging models. The net effect is that growth will persist, but the allocation of that growth will increasingly favor players who can integrate material science, regulatory readiness, and premium execution.
Strategic Actions for Decision Makers
For manufacturers and packaging suppliers: Prioritize recyclable barrier platforms and mono-material pathways that align with regulated markets and multinational buyer expectations. Invest in automation and line flexibility to reduce unit costs while accommodating custom formats, high-resolution graphics, and shorter runs. Strengthen capabilities in anti-counterfeiting, sensory differentiation, and documentation support for pharmaceutical and healthcare applications, where compliance and traceability command premium value.
PW Consulting
For investors evaluating exposure to laminated tube value chains: Focus on companies with credible recyclable technology roadmaps, diversified application coverage, and capacity expansion tied to automation rather than purely incremental volume. Monitor regulatory milestones that affect recyclability grading and recycled content thresholds, since these will influence which product architectures gain or lose market access. Assess regional manufacturing footprints for cost resilience, material access, and proximity to high-growth application demand.
For brand owners, procurement teams, and R&D leaders: Treat laminated tube selection as a strategic variable rather than a procurement commodity. Align packaging architecture with formulation sensitivity, shelf-life requirements, brand positioning, and regional compliance obligations. Engage suppliers that can demonstrate recyclable design compatibility, consistent barrier performance, and the ability to support premium graphics or security features where relevant. Build sourcing strategies that balance cost, compliance, and differentiation, recognizing that premium packaging value is increasingly tied to sustainability credibility and product protection.
Detailed segment-level data, regional demand patterns, and company-specific capability comparisons can materially sharpen these decisions. Access to comprehensive research and customized insights helps leadership teams validate assumptions, size opportunities more precisely, and anticipate regulatory or competitive shifts before they affect sourcing or investment choices. For organizations seeking a fuller picture of the laminated tubes market, deeper analysis and tailored recommendations are available through the complete research report.
For detailed analysis of this topic, please visit the official page: Laminated Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Zinc Sulfate Market: How the 6.8% CAGR and Asia Pacific Growth Redefine Strategy
By pmarketresearch, 2026-09-21
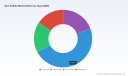
The Zinc Sulfate Market at a Crossroads: Strategic Trends and Commercial Opportunities
The global zinc sulfate market is entering a phase of structural expansion, driven by converging demand across agriculture, life sciences, and industrial applications. With revenues reaching approximately 1,780 million in 2025 and a projected compound annual growth rate of 6.8 percent through 2032, the sector is moving beyond cyclical commodity fluctuations into a period defined by geographic rebalancing, product specialization, and regulatory tightening. Asia Pacific now anchors the majority of volume, while Europe and North America maintain higher value-share positions tied to pharmaceutical-grade and food-safety specifications. The market is not uniformly expanding; growth is concentrating in segments where purity, traceability, and supply reliability command premium pricing. For executives and investors, the opportunity lies in understanding where value is shifting and which operational capabilities will separate winners from commoditized suppliers.
The market structure reflects moderate concentration, with the top three players capturing just over forty percent of revenue and the top five approaching fifty-three percent. This leaves meaningful room for regional specialists, contract manufacturers, and new entrants that can align product grades with regulatory pathways and end-user certification requirements. The balance between scale and specialization will define competitive outcomes over the next several years. Companies that treat zinc sulfate as a single commodity are increasingly exposed to margin compression, while those that segment by application, hydration state, and quality assurance are building defensible positions in higher-margin channels.
Market Landscape and Core Challenges
A Market Defined by Volume Growth and Specification Differentiation
The revenue trajectory from 2020 through 2025 shows steady expansion, with a notable acceleration in 2024 before stabilizing at a higher base in 2025. The forward curve suggests continued growth, but the path is uneven across hydration states and end-use channels. Monohydrate forms the largest share of revenue, reflecting its broad industrial and specialty use, while anhydrous and hydrated variants serve more application-specific roles. The agrochemical channel remains the largest demand pool, drawing on zinc sulfate as a micronutrient supplement and soil amendment, while pharmaceuticals, water treatment, and animal nutrition contribute smaller but strategically important revenue streams that often carry stricter quality and documentation requirements.
This mix matters because growth in one channel does not automatically translate into margin expansion. Agrochemical volume can be price-sensitive and logistics-driven, while pharmaceutical and food-adjacent applications reward consistency, certification, and testing capability. The market’s center of gravity is therefore shifting not only by geography but by the economic value attached to specification control. Suppliers that can reliably bridge bulk demand and high-purity demand are positioned to capture more of the value chain.
Key Challenges and Turning Points
Three structural challenges are reshaping strategic planning across the sector.
-
Raw material and energy cost volatility. Sulfuric acid is a core input for zinc sulfate production, and regional disruptions have periodically pushed input costs higher for sulfate-based trace minerals and related chemical lines. When feedstock costs rise faster than contractual pass-through mechanisms, producers face margin pressure unless they have secured long-term agreements, optimized process efficiency, or shifted toward higher-specification grades that better absorb cost increases. This dynamic is especially relevant for producers operating in regions exposed to Middle East supply instability and for manufacturers that rely on imported acid or upstream zinc intermediates.
-
Regulatory compliance as a barrier and a differentiator. Matched to evolving safety data sheet requirements, registration dossier maintenance, and food-safety database inclusion, compliance is no longer a back-office function. It is increasingly a commercial prerequisite. Producers serving export markets must navigate REACH-related documentation, quality-assurance databases, and testing protocols that differ by destination. A company’s ability to maintain current documentation and demonstrate traceability can determine whether it wins or loses regulated tenders. In practical terms, regulatory readiness is becoming a source of competitive advantage rather than a baseline cost.
-
Supply continuity and operational resilience. Force majeure events, plant maintenance, and logistics bottlenecks can interrupt supply faster than demand adjusts. Recent operational restarts at major European sites illustrate how quickly availability can be restored after disruptions, but they also underline the importance of contingency planning for customers that depend on steady grades and reliable delivery. For buyers, this creates a premium on dual sourcing, inventory strategy, and supplier transparency. For producers, it reinforces the need for robust maintenance planning, clear communication during outages, and alternative routing for key customers.
Together, these challenges push the market toward a more differentiated operating environment. The winners will be those who convert compliance, continuity, and cost discipline into trust-based customer relationships rather than treating them as isolated risk management tasks.
Core Drivers Shaping the Market
Technology and Process Innovation
Innovation in zinc sulfate production is less about radical chemistry and more about precision, efficiency, and grade control. Higher-purity monohydrate and heptahydrate offerings depend on tighter processing controls, consistent crystallization, and reliable analytical verification. In a market where end-users increasingly compare suppliers on documented purity and batch-to-batch consistency, testing capability becomes a strategic asset. Laboratories that achieve recognized accreditation for chemical testing strengthen their ability to support pharmaceutical, food-safety, and high-purity industrial applications. This is not simply a quality function; it is a market-access enabler.
Process improvements that reduce variability, lower energy intensity, and improve yield also matter because they directly affect cost structure and the ability to compete in regulated segments. Where producers can demonstrate both consistent output and credible test documentation, they can defend pricing in channels where specification risk is costly to the buyer. In effect, technology is becoming a commercial signal as much as an operational one.
Policy and Regulatory Environment
Regulatory dynamics are tightening the practical definition of market participation. Safety data sheet updates aligned with REACH obligations, active registration dossier monitoring, and food-safety database registrations all contribute to a landscape where documentation is part of the product. For exporters and multinational buyers, this means that compliance maturity varies by supplier and by region, and those variations influence sourcing decisions.
The regulatory environment also shapes the pace at which new capacity can be commercialized and how easily suppliers can enter specific channels. Registration, notification, and certification pathways differ across pharmaceutical, food, and industrial applications, and the cost of navigating them can be substantial. Companies that invest early in maintaining current filings and transparent documentation can shorten sales cycles in regulated markets and reduce the risk of disqualification during procurement reviews.
Demand-Side Shifts in Agriculture and Life Sciences
Demand is being shaped by two distinct but important dynamics. In agriculture, zinc deficiency management and crop nutrition strategies continue to support demand for zinc sulfate as a micronutrient source, but purchasing behavior is increasingly informed by formulation compatibility, solubility, and application reliability. In life sciences and animal nutrition, demand is growing more slowly in volume terms but more decisively in value terms, because these channels require higher-grade material and stronger documentation. The rise of certified API-oriented supply chains and specialized pharmaceutical-grade sourcing has created a separate demand layer in which compliance and traceability matter as much as price.
This divergence means that aggregate demand growth can mask very different commercial realities. Volume-led buyers may focus on logistics and cost, while specification-led buyers focus on certification, purity, and supply continuity. Suppliers that understand this split can avoid the trap of competing on a single metric and instead design product lines, service models, and commercial terms around the needs of each channel.
Supply Chain and Cost Structure Evolution
The cost structure of zinc sulfate is sensitive to sulfuric acid prices, zinc feedstock availability, energy costs, and freight dynamics. Regional instability in the Middle East has periodically lifted sulfuric acid prices, raising production costs for zinc sulfate and related sulfate-based trace minerals. This is not a temporary inconvenience; it is a reminder that sulfate chemistry remains exposed to upstream volatility. Companies with diversified sourcing, long-term feedstock contracts, or integrated operations have a structural edge when input markets tighten.
At the same time, the supply chain is becoming more regionalized in practice. While Asia Pacific remains a major volume center, buyers in Europe and North America often prioritize proximity, reduced transit risk, and established regulatory documentation. That creates opportunities for producers with manufacturing footprints in or near key markets, as well as for exporters that can demonstrate reliable logistics and full regulatory alignment. Supply chain strategy is increasingly a market-access strategy.
Competitive Landscape and Leading Strategies
Strategic Positioning Among Core Players
The market features a mix of large-scale European producers, specialized U.S. suppliers, and India-based manufacturers serving pharmaceutical, industrial, and export channels. This diversity matters because each group competes on a different set of strengths.
-
Europe’s scale producers emphasize large-volume capability, broad application coverage, and food-safety and quality-assurance positioning. Their strategic advantage lies in scale, established customer relationships, and the ability to supply multiple hydration states and industrial grades. Recent operational restarts at major sites show how quickly scale producers can recover supply and reaffirm market position after disruptions, reinforcing their role as reliability anchors for industrial and specialty buyers.
-
U.S.-based specialty suppliers compete through grade specificity and application alignment. High-purity testing accreditation and product forms suited to pharmaceuticals, food, and high-purity industrial use allow these players to serve channels where specification matters more than bulk price. Their value proposition is increasingly tied to documented quality, responsive service, and the ability to support regulated procurement requirements.
-
Middle East and export-oriented suppliers combine manufacturing access with export reach, often bridging European or other production bases with distribution into international markets. Their strategic relevance comes from logistics flexibility and the ability to serve buyers seeking geographic diversification or alternative sourcing pathways.
-
India-based pharmaceutical and API-linked manufacturers are positioned around regulatory filings, international certifications, and export-ready compliance documentation. Their differentiation often rests on certifications that support pharmaceutical and regulated industrial sales, enabling them to participate in channels where documentation and audit readiness are essential.
The common thread across these groups is that scale alone is no longer enough. The most resilient players combine capacity with specification control, regulatory readiness, and the ability to maintain supply during disruptions. Where those capabilities align, suppliers can move up the value chain into channels that reward reliability and documentation.
PW Consulting
Market Structure Evolution: Consolidation, Fragmentation, and New Entry
The market is not consolidating in a simple, uniform way. Concentration is moderate, which means a few major players hold meaningful share, but the long tail of regional and specialized suppliers remains commercially relevant. Over time, the structure is likely to evolve along two tracks. In bulk and price-sensitive channels, scale, logistics efficiency, and feedstock cost management will push toward consolidation among the most efficient producers. In regulated and high-purity channels, fragmentation may persist or even deepen, because access depends on certification, testing, and documentation rather than volume alone.
Sodium Sulfate Market
New entry will be most viable where suppliers can bring a clear regulatory or specification advantage, a regional logistics benefit, or a process advantage that reduces variability and cost. Pure commodity entry without differentiation is harder to sustain, especially when input costs fluctuate and buyers increasingly screen suppliers on compliance and continuity. The more interesting opportunities lie in targeted entry into pharmaceutical-grade, food-adjacent, or specialty industrial niches where the purchase decision is shaped by risk reduction rather than lowest unit price.
Future Trends and Commercial Implications
Trend One: Specification and Compliance as Market Moats
Over the next three to five years, the practical cost of entering regulated channels will remain high, and the value of proven documentation will increase. Suppliers that maintain current safety data sheet alignment, keep registration dossiers active, and hold recognized test accreditation will find it easier to secure contracts in pharmaceutical, food-safety, and specialty industrial applications. The commercial implication is clear: documentation and testing capability will increasingly function as a market moat. Companies that treat these capabilities as strategic assets can expect stronger customer retention, better pricing resilience, and broader access to higher-margin demand.
Trend Two: Regional Rebalancing and Supply-Side Diversification
Demand will continue to grow, but the geography of value capture will shift as buyers prioritize supply continuity, regulatory alignment, and freight reliability. Asia Pacific will remain a volume anchor, but European and North American demand may increasingly favor suppliers with regional production, strong logistics, and established regulatory standing. For manufacturers, this creates pressure to decide whether to compete primarily on volume, on proximity, or on specification. For buyers, it creates an incentive to diversify sourcing rather than depend on a single region or a single supplier profile. The broader implication is that resilience will be priced into sourcing decisions more explicitly than in the past.
Trend Three: Input Volatility Will Reward Integrated and Contract-Secured Producers
Sulfuric acid and upstream zinc economics will continue to influence margins, especially when geopolitical instability affects feedstock prices. Producers with long-term sourcing, integrated operations, or flexible cost-pass-through structures will be better positioned to maintain profitability during input shocks. The commercial opportunity here is not simply cost reduction; it is the ability to offer reliable pricing and consistent availability when competitors are distracted by cost volatility. In uncertain input markets, predictability becomes a selling point.
Risks and Uncertainties to Watch
Several uncertainties could alter the trajectory. Regulatory requirements may tighten further in specific end-use channels, raising the compliance burden for exporters and smaller producers. Input cost swings could compress margins for suppliers without contract protection or process efficiency. Demand in agriculture may be sensitive to crop economics, weather patterns, and fertilizer price cycles, introducing volatility into the largest volume channel. Finally, operational disruptions at major sites can temporarily reshape regional availability, rewarding suppliers with backup capacity and transparent communication. These risks are manageable, but they require proactive planning rather than reactive adjustment.
Actionable Guidance for Decision Makers
For Manufacturers and Producers
-
Align product portfolios with the economic logic of each channel. Maintain bulk-grade capability for volume demand, but invest in the documentation, testing, and grade control needed to serve pharmaceutical, food-safety, and specialty industrial buyers. The highest-margin growth is often in segments where specification reduces customer risk.
-
Treat regulatory readiness as a commercial function. Keep safety data sheets, registration filings, and quality-assurance records current and accessible. Buyers increasingly screen for compliance during sourcing decisions, and documentation gaps can become lost sales even when price and capacity look attractive.
-
Build input resilience into operations and commercial terms. Where possible, secure feedstock arrangements, improve process efficiency, and design pricing mechanisms that can withstand periodic sulfuric acid volatility without eroding customer trust.
For Investors and Strategic Buyers
-
Assess suppliers on more than capacity. The most durable value often sits with companies that combine reliable output with recognized testing, regulatory alignment, and the ability to maintain supply through disruptions. In regulated channels, these attributes can matter more than headline volume.
-
Look for structural advantages in specification control and certification. Producers with strong documentation and accreditation are better positioned to expand into higher-margin demand and to retain customers when input costs or supply conditions become turbulent.
-
Monitor regional diversification as a sourcing signal. In a market where availability can shift quickly, suppliers with multiple production bases, export flexibility, or strong logistics footprints offer more predictable access than single-point dependencies.
For Procurement and Supply Chain Leaders
-
Diversify by specification and region, not only by supplier name. Separate bulk-grade sourcing from high-purity or regulated-grade sourcing so that supply strategy matches end-use risk. A single sourcing model rarely fits both agrochemical volume and pharmaceutical-grade requirements.
-
Incorporate compliance and continuity into supplier evaluation. Review documentation currency, testing accreditation, and operational resilience alongside price. In practice, the cheapest option can become expensive if it fails a regulatory check or disrupts production.
-
Plan for input-driven price variability. Use contract structures, inventory buffers, or dual sourcing to reduce exposure to sulfuric acid volatility and regional logistics shocks. Predictable availability can be worth a premium when production continuity is at stake.
Why Deeper Intelligence Matters Now
The zinc sulfate market is growing, but growth is not uniform, and the value of that growth depends on where a company sits in the value chain. The most important decisions in the next few years will concern specification strategy, regulatory readiness, feedstock resilience, and sourcing diversification. Aggregate market size and CAGR tell part of the story, but they do not reveal which hydration states, applications, regions, or compliance pathways will generate the strongest returns for a particular business model.
For decision makers who need to move from broad market direction to actionable targeting, the next step is to examine the segmentation detail, competitive benchmarking, and scenario-based supply analysis that sit beneath the headline trends. A more granular view of regional demand patterns, product-grade economics, and supplier capability gaps can clarify where to invest, where to source, and where to defend position. Access to the full research report enables that level of precision, providing the detailed breakdowns and customization needed to translate strategic insight into operational decisions.
Magnesium Sulfate Market
For detailed analysis of this topic, please visit the official page: Zinc Sulfate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Interior Design Market: Why 6.5% CAGR and $331B by 2032 Changes Everything
By pmarketresearch, 2026-09-21
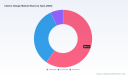
The Interior Design Market at an Inflection Point: Strategic Trends and Commercial Opportunities (2025–2032)
1. Market Context and Structural Challenges
The global interior design market has maintained a steady upward trajectory over the past half-decade, with total revenue expanding from approximately USD 157.5 billion in 2020 to an estimated USD 211.5 billion in 2025. The forward outlook points to continued expansion through 2032, supported by a projected compound annual growth rate of 6.5 percent. While the headline figures convey resilience, the underlying composition tells a more nuanced story. Residential-driven demand accounts for the largest share of value, commercial and institutional segments together form a substantial second pillar, and regional activity spans mature markets in North America and Europe alongside fast-growing corridors across Asia Pacific, Latin America, and the Middle East and Africa. This breadth provides a foundation of diversified demand, but it also masks pockets of volatility that are reshaping how firms plan capacity, pricing, and channel strategy.
The first structural challenge is cost volatility across materials and labor. Escalating input prices and tariff-driven distortions have placed margin pressure on manufacturers and contractors alike, while also complicating budgeting for end clients. Professional bodies have flagged rising material costs and widespread tariffs as factors that are directly reshaping demand for interior design services and product pricing, with independent analysis of recent trade actions estimating a meaningful per-home cost impact for builders that ripples through furnishing supply chains. At the same time, labor market tightness—paired with elevated housing prices in several regions—has made it harder for practices to scale project delivery without compressing fees or stretching timelines. For executives, the operational question is no longer whether costs will fluctuate, but how to build pricing architecture, sourcing flexibility, and service models that can absorb shocks without eroding client trust.
The second challenge is the shifting regulatory and credentialing landscape. Interest in formalizing the profession has accelerated, with a growing number of states considering legislation related to licensing or registration of interior design practitioners, and one state reaching a milestone as the thirtieth to regulate the profession following a sunset review. These developments affect liability exposure, permissible scope of work, and competitive differentiation across jurisdictions. Firms that rely on unlicensed staff or cross-border service delivery must anticipate uneven rule sets, while brands that invest in credentialed talent can turn compliance into a trust signal. The practical implication is that market access, insurance requirements, and partnership structures are becoming more localized and more consequential than in prior cycles.
The third challenge is fragmentation in how value is captured. Despite the presence of category-leading companies, the top three operators account for roughly 18 percent of revenue and the top five for about 22 percent, indicating a broadly distributed market with room for consolidation as well as for niche specialization. That dispersion creates both opportunity and risk: it allows agile entrants to win in specific use cases or geographies, but it also means that price competition, channel conflict, and brand dilution can emerge quickly when demand softens. Leaders that convert scale into service depth, proprietary product systems, and integrated delivery tend to outperform in mixed cycles, while undifferentiated players face margin erosion.
Together, these dynamics create a market that is growing in aggregate yet demanding more discipline at the micro level. Executives should read the growth trajectory not as an invitation to expand indiscriminately, but as a reason to prioritize resilience, credentialing readiness, and strategic focus in the segments where they can sustain advantage.
2. Core Drivers Reshaping Demand and Supply
Technology and Digital Enablement
Digital workflows are moving from support functions to core value drivers. Generative design, parametric specification tools, and integrated visualization platforms are compressing the time from concept to approval, which is particularly valuable in residential and commercial projects where client decision cycles can be protracted. More importantly, these tools are enabling firms to standardize repeatable elements while customizing high-impact spaces, improving both margin and client satisfaction. The same technologies support better inventory synchronization for product suppliers by aligning design intent with manufacturable options, reducing rework and last-minute substitutions. The practical takeaway is that technology investment is increasingly a margin and speed story: the firms that can deliver fast, high-fidelity options and keep specification accuracy high are winning a larger share of wallet in complex projects.
Policy and Regulatory Dynamics
Policy is becoming a more direct lever on demand and operating costs. Trade actions and material tariffs have altered the economics of building and furnishing products, pushing some procurement teams to re-evaluate sourcing footprints and specs. Regulatory attention to professional credentials is also changing the playing field, raising the stakes for firms that deliver design services under varying legal regimes. Rather than treating these as external noise, leading organizations are incorporating policy scenarios into their planning: they diversify supplier bases to reduce concentration risk, align service offerings with recognized credentials where regulation is tightening, and prepare documentation and compliance processes that can be scaled across jurisdictions. In short, policy predictability is now an asset to be managed, and the firms that institutionalize scenario planning around it are better positioned to protect margins when rules shift.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user priorities are evolving in ways that favor service-led value over transactional transactions. In residential contexts, homeowners and developers increasingly seek cohesive design systems that balance aesthetics, durability, and lifecycle cost, particularly as housing affordability pressures shape renovation versus move-up decisions. In commercial and institutional settings, organizations are recalibrating spaces for hybrid work, wellness, accessibility, and brand experience, which expands the scope of interior work beyond fit-out to include adaptive reuse and spatial programming. Awards, trade shows, and curated showcases continue to influence taste formation and accelerate the adoption of new styles, materials, and crafts; the steady cadence of global events across North America, Europe, and Asia underscores how quickly preference cycles can move and how important timely exposure is for brands aiming to stay relevant. For operators, the implication is that design value must be demonstrated through outcomes—usability, durability, speed, and emotional resonance—rather than through decoration alone.
Supply Chain and Cost Structure Realignment
The cost structure of interior products and services is being rebalanced by a combination of input volatility, logistics constraints, and labor economics. Builders and suppliers are absorbing higher baseline costs on key inputs, which cascades into product pricing and project budgets, while shortages of skilled labor raise the cost of execution and extend delivery windows. In response, many organizations are shifting toward regionalized sourcing, modular product platforms, and pre-configured systems that simplify installation and reduce on-site variability. Vertical integration is gaining renewed attention in certain categories because it can tighten quality control and improve lead-time reliability, though it also requires capital discipline and careful capacity planning. The strategic signal is clear: resilience and repeatability are becoming as important as design novelty, and supply chain choices are increasingly a competitive differentiator.
3. Competitive Landscape and Leading Strategies
Strategic Positioning of Key Participants
Several established players illustrate distinct routes to advantage in a fragmented market. Legacy-oriented product houses have leaned into brand portfolios that span heritage and contemporary aesthetics, allowing them to serve multiple price tiers while preserving prestige equity. Their strategic edge lies in breadth of offering—wallpapers, fabrics, ancillary interior products, and coordinated collections—that simplifies specification for designers and trade partners, and in the ability to refresh lines without abandoning recognizable franchises. Luxury lifestyle retailers, by contrast, compete on curation, service, and aspirational positioning, extending across furniture, textiles, lighting, bathware, and décor through multiple brand channels. Their advantage is the integration of high-end product with design advice and an experiential retail environment that supports higher price points and deeper client relationships. Vertically integrated furniture manufacturers combine custom-crafted production with design services and North American manufacturing, using that model to control lead times, quality, and cost-to-serve while offering complimentary design support that raises switching costs for customers. Large-scale flooring and interior panel producers anchor broad application coverage across furniture, cabinetry, and residential and commercial use, leveraging scale in materials and manufacturing to compete on specification frequency, consistency, and supply reliability.
Differentiation and Scope Decisions
Across these models, differentiation tends to emerge from a few recurring choices. The first is the depth of integration between product and service. Companies that pair specification-grade products with design assistance, installation guidance, or project coordination capture more of the project value and reduce the likelihood of substitution. The second is the balance between breadth and focus. Broad portfolios enable cross-selling and specifier convenience, but focused systems can command stronger loyalty in key segments if they solve a clear problem—durability, maintenance, speed of installation, or style cohesion. The third is the degree of vertical control. In an environment of cost and labor pressure, manufacturers with direct oversight of critical steps can protect quality and timing, while more decentralized players must invest in supplier governance and transparent communication to achieve similar outcomes. The practical lesson is that advantage rarely comes from a single attribute; it comes from a coherent system that aligns brand promise, product capability, service model, and supply discipline.
Evolution of the Market Structure
The competitive map is evolving along three lines. Consolidation is plausible where scale improves purchasing power, speeds innovation cycles, and expands distribution reach, particularly if larger players can integrate design services or channel access that smaller firms cannot easily replicate. Differentiation is intensifying in parallel, as segments such as sustainable interiors, wellness-focused spaces, and regionally specific aesthetics create demand for specialized expertise and materials, opening space for firms that can credibly claim depth in a niche. New entrants and adjacent players continue to test the boundaries of the market, using digital storefronts, direct-to-consumer channels, and subscription-style services to reach customers outside traditional trade paths. These movements do not point to a single end state; rather, they suggest a market in which the center will hold for broad-line players with strong systems, while edges will become more dynamic as specialists and digital-native models gain traction. Executives should therefore plan for a landscape that remains contested, with advantage determined by the clarity of positioning and the reliability of execution.
PW Consulting Information & Electronics Research Center
4. Forward Outlook: Trends and Commercial Implications (Next 3–5 Years)
Service-Integrated Product Systems Will Gain Share
Over the next few years, demand is likely to tilt toward offerings that combine repeatable product platforms with embedded design and specification support. Clients in both residential and commercial settings are seeking speed, certainty, and coherence, and they are willing to pay a premium when a solution reduces coordination risk and installation variability. Brands that can present curated systems—complete with sample libraries, digital specification tools, and clear installation sequences—will be better placed to capture project budgets and to defend margins against commoditization. The commercial opportunity lies in packaging: creating modular, specifiable systems that scale across use cases while retaining enough flexibility to meet local preferences. The risk is execution complexity, because systems that are too rigid can alienate designers, while systems that are too loose fail to deliver the promised consistency.
Credentialing and Compliance as Competitive Filters
The regulatory momentum around professional licensing and registration is expected to continue shaping how services are delivered and how firms are evaluated. As more jurisdictions formalize requirements, credentialed practitioners and organizations will gain an advantage in projects where liability, safety, and code interaction matter, and will be better positioned to partner with architects, contractors, and public-sector clients. This trend creates an opportunity for firms to use compliance as a trust asset, particularly in institutional and commercial work. The uncertainty is uneven adoption: if rules vary widely across regions, multi-market operators will need to maintain flexible staffing and documentation practices, and smaller firms may face higher relative compliance burdens. Executives should treat credentialing strategy as part of market access planning rather than as a back-office concern.
Industrial Design Market
Sustainability and Lifecycle Value Move From Messaging to Specification
Sustainability is becoming a practical filter in procurement, driven by a combination of client expectations, event-led trend diffusion, and a growing appetite for transparency in materials and processes. Dedicated showcases and trade events that emphasize sustainable interiors, alongside broader industry gatherings, indicate that eco-conscious design is moving from a marketing theme to a specification criterion, especially in commercial and institutional projects where operating costs and reputational risk are salient. The commercial implication is that firms able to provide clear, verifiable information on material sourcing, durability, maintenance, and end-of-life options can win preference in selection processes and reduce perceived risk for buyers. The caveat is that credibility matters: claims that cannot be substantiated may erode trust quickly, and the cost of verification can be a barrier for smaller suppliers unless they align with recognized standards or partner with testing and certification bodies.
5. Strategic Implications for Decision-Makers
For manufacturers and product suppliers, the priority is to reduce variability and increase specifiability. That means investing in modular platforms and coordinated collections that simplify selection for designers, expanding digital tools that connect design intent to manufacturable options, and hardening supplier governance to manage input volatility and lead-time risk. Where vertical integration is feasible, it should be pursued with clear attention to capital efficiency and capacity utilization; where it is not, stronger transparency and contingency planning with upstream partners become essential. The goal is to make it easier for the market to choose your products repeatedly, which in turn supports more predictable demand and better pricing power.
For investors, the most attractive exposure is likely to be found where service depth, credentialing readiness, and supply resilience compound rather than where growth is pursued through breadth alone. Categories and platforms that can demonstrate repeat specification, high switching costs through design services, and credible sustainability credentials are better positioned to sustain margins across cycles. Due diligence should focus on the operating model behind the headline momentum: how pricing responds to input shocks, how lead times are controlled, and how the firm plans for a more fragmented regulatory environment. Capital that supports operational discipline and credible differentiation is more likely to outperform than capital that simply chases segment tailwinds.
Worldwide Marine Interiors Market
For procurement and design leadership, the strategic task is to convert volatility into a negotiation advantage by diversifying sourcing, favoring specifiable systems that reduce rework, and aligning project timelines with realistic labor and material availability. Building internal criteria that reward durability, maintenance ease, and verifiable sustainability can lower total cost of ownership and reduce the risk of reactive substitutions. At the same time, keeping a close watch on regulatory changes in relevant jurisdictions will help avoid eligibility or liability surprises as projects scale across regions.
Keeping pace with a market that is both expanding and fragmenting requires current, granular visibility into how segments, regions, and company strategies are evolving together. Detailed segmentation data, competitive benchmarks, and tailored scenario planning can turn broad trends into concrete choices about where to invest, what to standardize, and which risks to hedge. Readers seeking a fuller picture of the subsegments, regional nuances, and company-level dynamics underpinning this analysis can access the complete research report for deeper data and customized recommendations.
For detailed analysis of this topic, please visit the official page: Interior Design Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Passenger Boarding Bridge Market: How Asia Pacific Drives 6.98% CAGR to $3.22B
By pmarketresearch, 2026-09-21
Navigating the Passenger Boarding Bridge Market: Strategic Trends and Commercial Opportunities for 2026–2032
The passenger boarding bridge market is experiencing a period of structured expansion, driven by sustained airport infrastructure investment and gradual technological upgrades across terminals worldwide. Valued at approximately USD 2,030 million in 2025, the market has grown from around USD 1,400 million in 2020, reflecting a compound annual growth rate of 6.98 percent through the forecast horizon of 2032. By the end of the projection period, market size is expected to approach USD 3,224 million, indicating a shift from cyclical replacement cycles toward smarter, more integrated gate equipment. This trajectory is not merely about capacity addition; it reflects evolving ground-handling philosophies, fleet modernization, and a growing emphasis on operational reliability under tighter regulatory and sustainability expectations. For manufacturers, airport operators, and investors, the market presents a landscape where historical performance patterns intersect with structural changes in technology, procurement policy, and design preferences.
The Asia Pacific region continues to represent the largest revenue pool, supported by high-volume terminal expansion, new hub development, and intense competition to improve passenger throughput and turnaround efficiency. Europe and North America remain significant contributors, with growth increasingly shaped by modernization programs, fleet optimization, and the replacement of aging bridge inventories rather than pure volume expansion. Movable boarding bridges continue to hold a substantial share of market activity, reflecting their flexibility in dynamic gate configurations and their suitability for airports managing mixed aircraft fleets and variable operational layouts. In parallel, apron-drive configurations have maintained a strong presence, while nose-loader, over-the-wing, T-bridge, and commuter variants serve more specialized deployment scenarios where aircraft geometry, terminal spacing, or regional operational constraints dictate equipment selection. On the technology side, electro-mechanical systems have been steadily displacing hydraulic alternatives, driven by lower energy consumption, reduced maintenance burdens, and improved alignment with long-term operational efficiency goals.
Alongside these structural dynamics, three challenges are shaping strategic decision-making across the value chain. First, airports are balancing capital expenditure constraints with the need to modernize aging gate equipment that must handle larger aircraft, higher passenger volumes, and more frequent service cycles. Second, procurement policy is becoming more complex, particularly in markets where regulatory frameworks, local content expectations, and grant-linked requirements influence sourcing decisions and supplier eligibility. Third, the transition toward more energy-efficient and digitally integrated bridge systems is creating pressure on suppliers to demonstrate total cost of ownership advantages rather than relying solely on upfront price competitiveness. These factors are not isolated; they interact with each other and with regional demand patterns, making it increasingly important for participants to align product roadmaps with operational realities and procurement environments.
Core Drivers Reshaping the Market
Technology innovation is one of the most visible forces altering buyer expectations and supplier positioning. Electro-mechanical boarding bridges are gaining traction over hydraulic designs because they offer measurable reductions in energy use and long-term maintenance intensity. This shift is not simply a preference for newer architectures; it reflects a broader operational logic in which airports and ground handlers are evaluating lifecycle costs more carefully, especially where energy prices, labor availability, and service intervals affect total operating economics. Automated docking features, improved safety systems, and more responsive control interfaces are also becoming differentiators, allowing operators to reduce manual intervention, improve turnaround predictability, and support higher gate utilization. As these capabilities mature, the market is gradually rewarding suppliers that can integrate mechanical reliability with system-level intelligence rather than selling bridge hardware in isolation.
Policy and regulatory environments are acting as another important catalyst. Public funding programs and airport infrastructure grants are channeling capital into bridge replacement and installation projects, particularly in markets where aging gate infrastructure has become a constraint on capacity and service quality. In the United States, for example, substantial grant allocations have been directed toward airport improvement programs that include passenger boarding bridge replacements and installations across a broad set of airports. This type of support can accelerate project timelines and broaden the pool of funded modernization activity. At the same time, procurement rules are introducing additional layers of complexity. Project-specific Buy American waivers issued in 2025 and 2026 for certain boarding bridge projects illustrate how regulatory compliance and sourcing flexibility can intersect, creating both opportunities and eligibility constraints for suppliers. The practical implication is that policy support is expanding demand in specific segments, but it also requires participants to navigate funding conditions, documentation requirements, and local content expectations with precision.
Demand-side behavior is changing as well, shaped by airport capacity strategies and passenger experience priorities. Commercial airports remain the dominant application setting because they handle the highest traffic volumes and the broadest mix of aircraft types, making boarding bridge performance a direct factor in gate throughput and passenger flow. Airports are increasingly treating boarding bridges not as passive connectors between terminal and aircraft, but as active components of the gate ecosystem, where reliability, turnaround speed, and compatibility with evolving aircraft interiors influence customer satisfaction and operational planning. Regional airports, by contrast, tend to prioritize simpler deployment economics, durability, and maintainability, often favoring solutions that can serve limited gate configurations without excessive complexity. These differing demand profiles mean that product positioning, service offerings, and financing approaches must be tailored to the operational realities of each airport segment rather than applied uniformly.
PW Consulting Automotive & Machinery Research Center
Supply chain and cost structures are adding further nuance to market dynamics. Steel-walled designs have retained a strong share of sales due to their ruggedness, lower initial cost, and compatibility with a wide range of climatic and operational conditions. This preference underscores a pragmatic approach among many buyers, especially where durability and first-cost control remain decisive. At the same time, the broader shift toward electro-mechanical platforms is gradually reshaping component sourcing, maintenance planning, and service models. Suppliers that can manage raw material exposure, standardize high-demand configurations, and provide predictable lifecycle support are better positioned to navigate cost pressure while preserving margin stability. The market is therefore rewarding a blend of engineering robustness and operational predictability, particularly in environments where project timelines, installation complexity, and long-term service commitments influence winning bids.
Competitive Landscape and the Evolution of Winning Strategies
The competitive field includes a mix of established global suppliers and specialized operators with distinct regional footprints and product emphases. Several companies have built their positioning around integrated gate infrastructure capabilities, combining boarding bridge systems with automated docking, ground support equipment, or broader terminal interface solutions. Others differentiate by focusing on refurbed equipment, component-level innovation, or airport-specific delivery track records that emphasize installation reliability and after-sales support. The strategic common thread among stronger players is a move toward solution-oriented value propositions: rather than competing primarily on unit price, leading suppliers are aligning their offerings with gate performance, maintenance efficiency, compatibility with aircraft mixes, and the ability to support both new installations and lifecycle refurbishment.
A notable aspect of the current landscape is the way recent project activity and exhibition presence reinforce market positioning. Suppliers that maintain visible engagement with airport operators through project deliveries and industry events are better able to demonstrate execution capability and keep their product roadmaps aligned with procurement realities. For instance, the delivery and installation of multiple passenger boarding bridges at a major terminal expansion project illustrates how targeted installations can validate a supplier’s ability to support capacity growth while meeting airport-specific integration requirements. Similarly, continued participation in major airport trade events allows suppliers to showcase complete bridge systems alongside individual components, signaling both system-level competence and flexibility for partial upgrades or component replacement. These activities matter because airport procurement is often influenced by demonstrated project experience, local installation capability, and the supplier’s ability to support the asset over its service life.
Market concentration remains relatively high, indicating that a limited number of participants command a significant share of revenue. This concentration creates a competitive environment where scale, global installation experience, product breadth, and service networks can serve as meaningful barriers. At the same time, the market is not closed to focused entrants or specialists that can address specific airport needs, such as refurbishment, component innovation, sustainability-oriented upgrades, or regional deployment expertise. As a result, the landscape is evolving through a combination of consolidation among larger players and targeted competition from firms with differentiated technical or commercial approaches. Suppliers that can combine engineering consistency with strong service execution, and that can adapt to regulatory and funding conditions in key markets, are likely to strengthen their position over the forecast period.
Worldwide Military Floating Bridge Market
Looking Ahead: Trends That Will Shape the Next Three to Five Years
One of the clearest forward-looking trends is the continued migration from hydraulic to electro-mechanical boarding bridges as operators prioritize energy efficiency and reduced maintenance exposure. This transition is likely to accelerate where airports face pressure to manage operating costs, improve sustainability performance, and standardize equipment across multiple gates. The commercial opportunity lies not only in new installations but also in retrofit and upgrade pathways that allow airports to modernize existing assets without full replacement. Suppliers that can offer credible conversion strategies, predictable service outcomes, and compatible control architectures will be well placed to capture demand across both new builds and refurbishment cycles.
A second trend is the growing importance of automated docking, safety systems, and gate-level integration as airports seek more predictable turnaround performance and reduced manual handling risk. As these capabilities become more standardized, differentiation may shift toward reliability under high utilization, interoperability with airport operating systems, and the ability to support mixed aircraft configurations without sacrificing deployment speed. This creates opportunities for suppliers that can package mechanical performance with digital control features in a way that aligns with airport operational planning. The risk, however, is that over-engineering or complexity could raise installation costs and maintenance burdens, particularly for regional airports that value simplicity and durability over advanced automation.
A third trend concerns the influence of funding mechanisms and procurement policy on project visibility and supplier eligibility. Infrastructure grants and airport improvement programs are expected to keep replacement and modernization activity active in several key markets, but the rules attached to such funding can vary by project and location. Where local content expectations or Buy American-type conditions apply, suppliers may need to demonstrate supply chain compliance, domestic sourcing pathways, or partner-based delivery models to remain competitive. This dynamic creates both opportunity and uncertainty. It can open doors for suppliers with the right compliance posture and installation footprint, while simultaneously constraining participation for firms that cannot meet localized procurement requirements. Participants should therefore treat policy and funding environments as strategic variables, not background conditions, and build procurement readiness into their commercial planning.
Strategic Actions for Decision-Makers
For manufacturers and equipment suppliers, the priority is to strengthen total-cost positioning rather than compete solely on initial price. This means investing in electro-mechanical architectures where they are gaining acceptance, standardizing high-demand configurations such as steel-walled designs that continue to dominate sales for practical reasons, and building service models that support both new installations and refurbishment. Suppliers should also map their compliance and sourcing capabilities against the funding and procurement rules that shape key airport projects, since eligibility can be as important as technical performance in winning bids. Differentiation is increasingly tied to demonstrated installation execution, component reliability, and the ability to support airports through the full asset lifecycle.
For investors, the market offers a profile of steady growth with selective opportunities in modernization, automation, and refurbishment-driven demand. The most attractive exposure is likely to come from participants that can balance scale with segment-specific relevance, maintain strong service and installation capabilities, and adapt product offerings to shifting technology preferences. Investors should pay close attention to how suppliers position themselves against regulatory and funding conditions, because project-level policy changes can influence order timing, market access, and margin dynamics. Monitoring which companies are strengthening their presence through project deliveries, trade engagement, and component-level innovation can provide early signals about competitive momentum.
For airport operators and procurement teams, the strategic focus should be on aligning bridge selection with operational priorities and lifecycle economics. Where gate utilization, turnaround consistency, and energy cost matter most, electro-mechanical solutions with automated docking and improved safety features may deliver value beyond upfront price. Where durability, simplicity, and first-cost control are paramount, steel-walled configurations and proven mechanical designs remain compelling. Procurement planning should also account for installation complexity, local service availability, and any funding-related eligibility requirements that may affect supplier selection. A structured evaluation framework that integrates technical performance, maintenance expectations, and regulatory conditions will support more resilient purchasing decisions.
For decision-makers seeking more detailed segmentation data, regional considerations, and project-level dynamics, deeper intelligence can provide the granularity needed to translate these trends into concrete plans. The Passenger Boarding Bridge Market Landscape 2026–2032 and related PW Consulting research materials are available for teams that require more detailed breakdowns across type, model, technology, structure, application, and regional demand patterns, along with customized guidance for specific market or procurement scenarios.
Worldwide Airport Furniture Market
For detailed analysis of this topic, please visit the official page: Passenger Boarding Bridge Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Steam Dryer Market 2026: How Asia Pacific's 5.9% CAGR Reshapes Global Growth
By pmarketresearch, 2026-09-21
Steam Dryer Market: Strategic Trends and Commercial Opportunities Through 2032
The steam dryer market has entered a phase of measured expansion, with global revenue projected to grow from approximately $5.28 billion in 2025 to $7.19 billion by 2032, reflecting a compound annual growth rate of 5.9 percent. This trajectory is neither explosive nor stagnant; it signals a maturing industrial ecosystem where capital discipline, energy economics, and process innovation intersect. For executives and investors evaluating exposure to thermal processing equipment, the market offers steady returns but demands sharper segmentation, regional nuance, and a clear view of where competitive advantage is being rebuilt.
Underlying the headline numbers is a sector shaped by continuous drying demands across food, chemical, pharmaceutical, and bulk material applications. The revenue base has expanded consistently over the past five years, yet growth rates vary by geography, equipment type, and end-use segment. What matters now is not simply that the market is growing, but how the growth is being distributed and what structural forces are reallocating value among participants.
PW Consulting
Market Landscape and Core Challenges
At a macro level, the steam dryer market is characterized by moderate consolidation and a wide dispersion of equipment formats. The top three players account for roughly 47 percent of revenue, while the top five capture just over half. This concentration indicates a competitive environment where scale, application coverage, and service integration matter, but it also leaves substantial room for specialized suppliers and regional challengers to compete on customization, lead times, and local support.
One of the most pressing challenges is the tension between operational efficiency and input cost volatility. Industrial dryer manufacturing relies heavily on steel-intensive components, and hot rolled coil prices for dryer components hovered in the $904 to $940 per ton range in March 2025, with upward pressure linked to demand and raw material costs. Even as operators seek energy-efficient drying solutions, OEMs face margin compression if they cannot pass through material costs without sacrificing order momentum. This dynamic is reshaping pricing strategies, contract structures, and the economics of customization versus standardization.
Food Dryer Market
A second challenge lies in the skilled labor constraint affecting specialized engineering and assembly roles. Complex steam drying systems require precision fabrication, integrated controls, and commissioning expertise. Persistent shortages in these functions extend lead times and raise execution risk, particularly for large-scale or custom installations. For buyers, this translates into longer project cycles and greater dependency on supplier capacity; for manufacturers, it raises the stakes around workforce planning, modular design, and remote support capabilities.
A third inflection point is arriving through regulatory and standards-driven change. In the United States, federal energy efficiency standards for consumer clothes dryers now incorporate performance measures under Appendix D1, with updates effective after 2024. While this change primarily affects consumer equipment, it reflects a broader policy momentum around energy performance, lifecycle efficiency, and verifiable process outcomes. Industrial steam dryer buyers are increasingly exposed to similar expectations through corporate sustainability targets, utility incentives, and procurement standards that reward demonstrable energy recovery and lower thermal waste.
The practical implication is that market growth alone does not guarantee profitable growth. Companies that succeed will be those that can align equipment design with total cost of ownership, manage input cost exposure, and navigate a landscape where efficiency expectations are rising faster than in prior cycles.
Key Drivers Reshaping the Market
Technology Innovation and Breakthroughs
The most strategically important driver is the shift toward higher-efficiency steam drying architectures. Leading OEMs are investing in next-generation steam dryer platforms featuring advanced heat exchanger geometries and self-cleaning tube bundles. These improvements are not incremental cosmetics; they directly affect throughput, maintenance frequency, and energy utilization in continuous drying processes. Self-cleaning designs reduce fouling-related downtime, while refined heat exchange surfaces improve heat transfer consistency across varying load conditions.
Superheated steam drying is another area gaining traction, particularly where moisture removal, product quality, and sterilization must be managed together. The interest in this approach is reinforced by collaborative research efforts, including Valmet Corporation’s participation in the SteamDry research project for superheated steam drying technology in the paper industry. Such initiatives signal a transition from standalone equipment sales toward system-level solutions where drying, heat recovery, and condensate management are integrated.
Perhaps the most visible endorsement of scale and engineering maturity is Tsukishima Kikai Co., Ltd.’s delivery of the largest steam tube dryer to date in November 2025. Large-format units matter because they expand the feasible envelope for high-throughput applications and can improve unit economics in volume-intensive processes. At the same time, they raise the bar for installation logistics, structural support, and after-sales service, reinforcing the differentiation between suppliers that can execute complex projects and those positioned for smaller, more standardized orders.
For decision-makers, the message is clear: technology competition is moving from basic drying capability to integrated performance, reliability, and energy recovery. Procurement teams should evaluate not only drying capacity but also downtime sensitivity, cleaning cycles, and the extent to which steam condensate and waste heat can be recovered within the broader plantutility system.
Policy and Regulatory Environment
Policy dynamics are becoming a more explicit factor in demand patterns and vendor selection. Energy-related standards and efficiency expectations are no longer confined to consumer appliances; they are increasingly shaping procurement criteria in industrial contexts as well. In practical terms, buyers are looking for equipment that supports measurable efficiency gains, whether through reduced steam consumption, improved heat recovery, or process designs that lower the carbon intensity of drying operations.
At the same time, regulatory scrutiny can create both compliance burdens and differentiation opportunities. Suppliers that can document performance, provide transparent energy metrics, and align with regional standards are better positioned in tenders where efficiency is a scoring criterion. This is especially relevant in sectors such as food and pharmaceuticals, where process integrity and hygiene add further layers of specification. The regulatory environment is therefore not simply a constraint; it is a filter that rewards suppliers with robust technical documentation, application-specific validation, and lifecycle thinking.
Demand-Side Shifts in Consumer and Business Behavior
Demand is being shaped by broader industrial priorities rather than by a single sectoral surge. Food processing continues to be a major application area, driven by the need for consistent drying, shelf-life management, and scale. Chemical applications remain significant where thermal separation and moisture control are core to product specifications. Pharmaceutical and related sterile-processing environments contribute demand where drying must align with contamination control and process asepsis.
What ties these segments together is a growing emphasis on reliability and operating cost over pure purchase price. In many industrial settings, the economic case for a steam dryer is increasingly evaluated across energy consumption, maintenance intervals, cleaning requirements, and integration with existing steam and condensate systems. This is pushing buyers toward suppliers that can offer application engineering, commissioning support, and measurable performance guarantees.
Demand is also being influenced by regional industrialization patterns and the location of processing capacity. As production footprints adjust in response to logistics, labor, and market access, new drying capacity is being planned in diverse geographies. This does not automatically translate into uniform growth, but it does suggest that local service capability, parts availability, and application knowledge are becoming more valuable than in an era when equipment purchases were more centralized.
Supply Chain and Cost Structure Dynamics
The cost structure of steam dryer manufacturing is being tested by material price movement and labor availability. Steel-based components remain a core cost driver, and the recent range in hot rolled coil prices points to continued exposure for fabrication-intensive equipment. In response, some manufacturers are exploring more standardized module designs, improved procurement hedging, and design choices that reduce weight or material intensity without compromising performance.
Steam Water Heater Market
Labor shortages in specialized engineering and assembly roles add another layer of complexity. Where skilled capacity is constrained, projects can face scheduling risk, and the value of repeatable designs and remote diagnostics increases. A supply chain that can deliver consistent quality, predictable lead times, and responsive field support is becoming a competitive asset in its own right. This is particularly important for large installations and for customers operating in regions where local technical support is limited.
For commercial strategy, these dynamics suggest that cost leadership alone is increasingly difficult to sustain unless it is paired with process efficiency and service reliability. Suppliers that can manage material exposure, streamline assembly, and reduce dependency on scarce specialized labor are better placed to protect margins while maintaining competitive pricing.
Competitive Landscape and Leading Strategies
The competitive field blends global engineering groups, application-focused specialists, and regional manufacturers with strong local presence. The strategic question is not simply who is largest, but where each participant derives defensible advantage and how that advantage is likely to translate into share over the next several years.
Andritz AG operates from a position of broad process integration, offering rotary steam tube dryers, fluidized bed systems, and superheated steam dryers for pulp, paper, food processing, biomass, and bulk chemicals. Its emphasis on high-throughput continuous drying and energy recovery positions it as a solution provider for large industrial flows rather than a narrow equipment vendor. The strategic advantage here is the ability to connect drying performance with upstream and downstream process needs, which can be compelling in complex installations where overall plant efficiency matters.
GEA Group AG brings strength in spray drying and heat recovery, including aseptic-oriented systems for pharmaceutical and food applications. Its focus on aseptic sterilization and energy efficiency in steam-based processes aligns well with demand in sectors where hygiene and process control carry high value. In competitive terms, this creates a clear niche where reliability, validation, and specialized servicing can support premium positioning.
Valmet Corporation specializes in pulp drying machines, airborne dryers, and steam recovery systems with high-capacity designs and integrated steam-condensate management. Its participation in research on superheated steam drying indicates a willingness to shape emerging process directions rather than merely respond to them. For paper and adjacent industrial drying contexts, that combination of capacity leadership and technology exploration can be a durable source of relevance.
Alfa Laval AB focuses on heat transfer and condensation through plate heat exchangers and vacuum dryers for food, dairy, and industrial applications. Its orientation toward energy-efficient steam recovery and condensation gives it a distinct angle in markets where thermal efficiency and compactness are priorities. Rather than competing purely on dryer size or throughput, Alfa Laval’s value proposition often centers on how effectively steam energy is managed within the system.
In the United States, Louisville Dryer Company and Williams, White & Company illustrate the continued importance of custom and application-tailored engineering. Louisville Dryer Company manufactures custom rotary steam tube dryers and ASME Division I certified systems for bulk materials and high-volume thermal processing. Williams, White & Company provides Davenport Dryers rotary steam tube dryers and water tube coolers for ethanol, biomass, food processing, and industrial bulk materials, with a long-term efficiency focus. These firms compete by serving specialized requirements, often where standard packages are insufficient and where engineering flexibility, certification, and service continuity matter.
Tsukishima Kikai Co., Ltd. stands out for large-scale steam tube dryer capability, including the largest units manufactured and supplied globally. Recent delivery of the largest steam tube dryer to date underscores its position in high-capacity applications and its ability to execute demanding projects. This scale advantage is most relevant where volume processing justifies large equipment footprints and where supplier execution capability is a decisive factor.
In parallel, region-specific players such as Jiangsu Chuandao Washing Machinery Technology Co., Ltd. in China and Ace Industries in India illustrate how local manufacturing and application focus can support growth in laundry, commercial processing, and batch-oriented pharmaceutical, food, and chemical applications. Their relevance often lies in responsiveness, cost-appropriate engineering, and proximity to local end-users, rather than in competing directly on global scale.
The broader pattern is one of differentiation rather than uniform convergence. Some suppliers compete on integration and large continuous processes, others on hygiene-sensitive applications, and others on customization and regional service. Market evolution is likely to remain fragmented at the application level while consolidating where scale, engineering intensity, and service networks create clear cost and performance advantages. New entry will probably be most viable where a supplier can address a specific application gap, offer a compelling efficiency story, or serve an underserved geography with credible local support.
Forward Outlook: Trends and Commercial Opportunities
Over the next three to five years, three trends are likely to shape the market's commercial center of gravity.
The first is the widening premium on efficiency-enabled drying systems. As energy costs, sustainability commitments, and procurement standards become more demanding, equipment that delivers better heat recovery, lower steam intensity, and reduced maintenance burden will gain preference. The opportunity lies not only in selling dryers, but in positioning drying as part of an integrated thermal management solution. Suppliers and buyers alike will benefit from clearer comparisons of total operating cost rather than upfront price alone.
The second trend is continued segmentation by application intensity. High-throughput continuous drying, hygiene-critical batch processing, and specialized bulk material handling will not compete on identical criteria. This creates room for targeted strategies: large-scale engineering for volume applications, aseptic and validated solutions for pharmaceutical and food uses, and flexible customized systems for niche industrial needs. Companies that align their product portfolios and service models to these distinct demand profiles are more likely to defend margins than those pursuing a one-size approach.
The third trend is the growing importance of execution capability. Large-scale equipment deliveries, complex installations, and specialized labor constraints will reward suppliers that can manage project risk, standardize where possible, and provide dependable field support. For buyers, this means that vendor selection should incorporate installation logistics, commissioning support, spare parts availability, and response time alongside technical specifications.
These trends also carry uncertainty. Material cost volatility can compress margins if pricing power is limited. Labor constraints may slow project execution and increase reliance on modular or more standardized designs. Regulatory expectations may shift faster in some regions than others, altering the relative attractiveness of efficiency-led investments. And while superheated steam and advanced heat exchange designs show promise, their adoption will depend on real-world validation, maintenance requirements, and the willingness of end-users to commit to new process configurations.
Even with these caveats, the commercial opportunity is tangible for players who treat efficiency, application fit, and service reliability as core competitive variables rather than supporting features.
Strategic Implications for Decision-Makers
The following actions are most relevant depending on the reader's role in the market.
For Manufacturers and Equipment Suppliers
Design strategies should increasingly balance customization with modular repeatability. Where specialized engineering is required, the cost of bespoke execution is rising, and suppliers that can standardize core subassemblies while retaining application flexibility will be better positioned to manage labor constraints and material exposure. Efficiency claims should be supported by verifiable performance metrics and integrated into the broader value proposition, including steam recovery, cleaning intervals, and downtime sensitivity.
Service and project execution are becoming strategic differentiators. The ability to deliver large or complex installations on schedule, provide local technical support, and maintain spare parts availability can matter as much as hardware specifications in competitive bids. Suppliers should also evaluate where partnerships, channel models, or regional assembly can reduce lead times and improve responsiveness.
For Investors and Corporate Development Teams
Investment judgment should focus on business models that can convert efficiency trends into recurring value. This may include suppliers with strong application engineering, service-intensive revenue streams, or exposure to sectors where hygiene, validation, and continuous processing command higher willingness to pay. Scale leaders with integration capabilities and specialized providers with defensible niches can both be attractive, but for different reasons and with different risk profiles.
It is also important to monitor where consolidation is likely to be driven by service networks and project execution rather than by product overlap alone. In a market where the top three hold roughly 47 percent and the top five just over half, there is still meaningful fragmentation, but share shifts will probably come from differentiation in application coverage, regional reach, and reliability rather than from price competition in commoditized segments.
For Procurement and Operations Leaders
Buying decisions should weigh total cost of ownership more heavily than initial equipment price. Key evaluation areas include steam consumption patterns, heat recovery potential, cleaning and fouling behavior, commissioning complexity, and the supplier's capacity to support the installation over time. For large or specialized projects, the execution track record of the supplier is especially important given ongoing labor and supply chain constraints.
Procurement teams should also consider how drying equipment interacts with plant-level steam and condensate systems. A dryer that performs well in isolation may underdeliver if it is not aligned with site utility infrastructure or if energy recovery opportunities are overlooked. In that sense, the most valuable purchases are those that reduce operating risk and improve integration, not merely those that meet a nominal capacity requirement.
Closing Perspective
The steam dryer market through 2032 is best understood as a steadily expanding but increasingly discriminating arena. Growth is real, but value creation will depend on how well participants navigate material costs, skilled labor limits, efficiency expectations, and application-specific demand. The leaders who stand out will be those that combine technical credibility with execution discipline and a clear view of where efficiency, reliability, and integration matter most to end-users.
For organizations that need a more granular view of segmentation dynamics, regional revenue distribution, and competitive positioning across specific end-use categories, the full PW Consulting report provides detailed breakdowns and tailored scenario analysis to support planning decisions.
For detailed analysis of this topic, please visit the official page: Steam Dryer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
DIP Switches Market 2026: Why Asia Pacific's 175M$ Lead & 3.6% CAGR Redefine Strategy
By pmarketresearch, 2026-09-21
The DIP Switches Market: Strategic Shifts and Commercial Opportunities in a Mature Landscape
Market Overview: A Resilient but Evolving Landscape
The DIP switches market has demonstrated steady, disciplined growth over the past half-decade, reflecting its entrenched role as a reliable interface component across a broad spectrum of electronic systems. From 2020 through 2025, global revenue expanded at a measured pace, moving from approximately 350 million USD to 425 million USD. This trajectory underscores a market that is neither in rapid expansion nor in structural decline, but rather in a phase of incremental maturation where value creation depends on differentiation, supply chain resilience, and targeted application penetration. Looking ahead, the forecast period through 2032 points to continued growth, with a compound annual growth rate of 3.6 percent, suggesting that demand will remain anchored by legacy industrial, consumer, and automotive applications while gradually integrating into newer electronics architectures.
Several structural realities shape this outlook. First, the market operates with notably high concentration among established manufacturers, which creates both barriers to entry and opportunities for incumbents to leverage scale, certification portfolios, and long-standing customer relationships. Second, the product mix is distributed across multiple mechanical configurations, each serving distinct actuation, packaging, and environmental requirements. This diversity means that no single form factor dominates the entire value chain; rather, success depends on matching switch characteristics to application constraints. Third, regional demand is spread across mature and emerging markets, with Asia Pacific representing the largest share of revenue, followed by Europe and North America. This geographic dispersion reflects both manufacturing footprints and end-market consumption patterns, but it also introduces complexity in navigating trade policies, logistics, and localization requirements.
Against this backdrop, the DIP switches market faces a set of interconnected challenges that will define competitive positioning over the next several years. These are not existential threats, but they are meaningful inflection points that require deliberate strategic responses.
RF Switches Market
Key Challenges and Inflection Points
The first challenge is the tension between mature demand profiles and the need for continuous product evolution. DIP switches remain valuable for configuration, calibration, and manual control functions, but many end markets are simultaneously adopting digital alternatives, firmware-based settings, and software-configurable interfaces. This does not eliminate demand for electromechanical switches, but it does shift the battleground toward applications where tactile feedback, field serviceability, safety certification, or fail-safe behavior justify a physical switching solution. Manufacturers that treat DIP switches as commodity components risk margin compression, while those that frame them as reliability-critical interface elements can defend pricing and deepen customer lock-in.
A second challenge arises from cost and sourcing pressures that ripple through the electromechanical supply chain. Input cost inflation, extended lead times for critical components, and an increasingly layered tariff environment have altered the economics of procurement and production planning. For DIP switches, which depend on materials such as copper-based contacts, plastics, and precision machining, these dynamics affect both manufacturing cost and inventory strategy. Buyers are increasingly weighing total cost of ownership against unit price, and suppliers are being asked to demonstrate consistency, certification readiness, and contingency capabilities rather than simply offering the lowest quotation.
A third challenge is the broadening expectation that even small components meet rigorous quality, environmental, and traceability standards. In automotive, medical, industrial control, and defense-related applications, switch selections are often gated by qualification requirements and long validation cycles. The practical implication is that time-to-value becomes as important as technical performance. Suppliers that can navigate certification frameworks, provide documented reliability data, and support customer engineering processes gain a structural advantage. Those that cannot may find themselves restricted to less demanding segments where competition is more price-driven and switching costs are lower.
Core Drivers Reshaping the DIP Switches Market
Market evolution in this segment is being propelled by a combination of technological, regulatory, demand-side, and supply chain forces. These drivers interact in ways that create both risk and opportunity, and they help explain why the market continues to expand even as it matures.
Technological Innovation and Product Differentiation
Innovation in DIP switches is less about radical redesign and more about refining mechanical reliability, packaging efficiency, and application-specific performance. Manufacturers are expanding product families with variations in actuation style, position count, terminal materials, and environmental protection. This matters because the value of a DIP switch often lies in how well it fits a specific use case: a device that must withstand vibration, temperature extremes, or extended cycling will require different engineering than one intended for benign consumer environments. The result is a market where portfolio breadth and specification clarity increasingly determine win rates.
Recent product activity illustrates this trajectory. In mid-2026, one manufacturer expanded its DIP switch range by adding over 100 new items to distributors, with a noticeable emphasis on industrial control and automation applications. This kind of expansion signals a strategic focus on coverage, availability, and segment relevance rather than a single breakthrough product. It also reflects the broader reality that distributors and design engineers often value accessible documentation, standardized packaging, and well-defined specifications as much as the underlying mechanical performance. In the same period, updated datasheets for established through-hole DIP switch series were released, reinforcing the importance of maintaining current technical information for recurring designs.
For businesses, the practical takeaway is that technical differentiation in DIP switches is often achieved through incremental enhancements that accumulate into meaningful competitive separation. Low-profile designs, dustproof or waterproof options, stackable configurations, and three-stage or normally open/closed variants all address real engineering constraints. Suppliers that align these features with clearly defined application narratives can command more stable demand than those competing primarily on generic part numbers.
Policy, Regulation, and Trade Policy Dynamics
The regulatory and trade environment has become a more prominent factor in component sourcing and production planning. Tariff adjustments on certain imported goods, including electronics-related categories, have raised input costs across multiple manufacturing sectors. Alongside this, duties on semi-finished copper products have added another layer of cost pressure for suppliers dependent on metal-intensive components. These changes do not fundamentally alter the demand for DIP switches, but they do influence where and how components are sourced, stocked, and priced.
Rotary DIP Switches Market
Trade policy uncertainty also affects the calculus of regional sourcing. Companies that rely heavily on single-country procurement are increasingly examining alternative manufacturing locations, buffer inventory strategies, and qualification of secondary sources. For DIP switch suppliers, this environment creates an opening for manufacturers that can demonstrate geographic flexibility, transparent cost structures, and consistent compliance support. Buyers are not simply looking for the cheapest part; they are looking for a sourcing partner that reduces exposure to disruption and helps them navigate an unpredictable trade landscape.
In practical terms, the policy environment is pushing both suppliers and buyers toward more disciplined supply chain design. That means stronger emphasis on documentation, regional stock strategies, and multi-source qualification. It also means that regulatory and tariff-aware sourcing decisions are becoming part of the commercial evaluation, not just an afterthought.
Demand-Side Shifts in Consumer, Industrial, and Automotive Segments
Demand for DIP switches is shaped by a mix of enduring and evolving application needs. Consumer electronics continue to represent the largest application share, reflecting the broad use of switches in devices that still benefit from physical configuration controls. Industrial applications form a substantial second pillar, where switches are used in control panels, equipment calibration, and field-serviceable settings. Automotive and telecommunications segments contribute meaningful demand as well, though they often impose more stringent quality and reliability expectations.
PW Consulting Health Care Research Center
What makes this demand environment strategically interesting is that the switching behavior is not uniform across segments. In consumer products, cost sensitivity and design compactness can dominate. In industrial and automotive settings, durability, vibration resistance, temperature tolerance, and certification credentials often carry more weight than absolute unit cost. This segmentation creates an opportunity for suppliers to build reputation-based positions in higher-value niches, even if they do not lead in total volume. It also explains why some manufacturers emphasize automotive-quality certifications, environmental management standards, and extended-cycle durability in their product narratives.
At the same time, demand-side behavior is being influenced by equipment manufacturers’ need to reduce lifecycle risk. In many cases, a DIP switch is selected not because it is the most advanced interface option, but because it offers a straightforward, serviceable, and verifiable method of configuration. This endurance is a competitive strength, but only if suppliers can support it with consistent quality and dependable availability. The most successful players are those that treat demand as application-specific rather than generic, tailoring their messaging and product breadth accordingly.
Supply Chain and Cost Structure Pressures
Cost structure changes are reshaping how DIP switches are produced, stored, and delivered. Raw material price increases have affected manufacturing inputs, with average increases observed in 2025 and continued pressure projected into 2026. These costs intersect with longer lead times for critical components, which have been reported in manufacturer supply chains with extensions averaging several weeks. The combined effect is a stronger incentive for planning discipline: suppliers and buyers alike are managing inventories with more caution, and the cost of disruption is being priced into sourcing decisions.
For DIP switch manufacturers, the supply chain environment rewards scalability, packaging efficiency, and reliability in delivery. Tape-and-reel formats, stackable designs, and standardized through-hole packaging can reduce handling complexity and improve integration into automated assembly processes. For buyers, the emphasis shifts toward suppliers that can maintain consistent lead times, communicate availability clearly, and reduce the risk of line-down scenarios. In this context, operational reliability becomes a commercial differentiator.
The broader implication is that cost pressure does not simply compress margins; it also accelerates consolidation around suppliers that can absorb variability without sacrificing service levels. Companies that can demonstrate stable input planning, efficient logistics, and transparent communication are better positioned to retain high-value customers, especially in segments where downtime or re-qualification costs are significant.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The DIP switches market features a mix of long-established global suppliers, regional specialists, and volume-oriented manufacturers. Competitive positioning often depends on the intersection of product breadth, certification capability, distribution reach, and segment focus. Rather than a single dominant business model, the market supports multiple viable strategies, each with its own risks and value drivers.
How Leading Players Differentiate
One common differentiation path is application-led specialization. Some manufacturers emphasize precision rotary designs for demanding environments such as medical devices, military electronics, and industrial control, where reliability and consistent performance are paramount. Others build their identity around broad mechanical variety, offering multiple actuation styles, mounting configurations, and terminal options to serve a wide range of electronics applications. This breadth can be attractive to design engineers who prefer to source from a supplier that can cover many requirements without fragmenting the bill of materials across too many vendors.
A second differentiation path centers on certification and qualification portfolios. In segments where customers must satisfy automotive, environmental, or quality management standards, suppliers that hold relevant certifications and can document process control gain a meaningful advantage. This is particularly important in markets where validation cycles are long and switching costs are high. Manufacturers that highlight vibration resistance, temperature tolerance, and extended cycle life are effectively positioning their products for environments where failure is costly.
A third path is distribution-led availability and catalog expansion. Some manufacturers have focused on increasing the number of items accessible through distributors, adding new series with detailed specifications, and improving the ease with which design engineers can evaluate and procure parts. This approach does not always depend on producing the most technically advanced switch; instead, it aims to reduce friction in sourcing and shorten the path from specification to purchase. In mature component markets, availability and information clarity can be as influential as raw performance.
A fourth path is price and volume orientation, often associated with through-hole standard products and commodity-focused production. This model can win in cost-sensitive applications, but it typically operates in a more competitive and less differentiated space. The strategic challenge for volume-oriented players is to maintain efficiency while avoiding races to the bottom that erode profitability. For buyers, the challenge is to ensure that lower unit prices do not introduce unacceptable risk in quality, delivery, or lifecycle support.
Market Structure and Evolution Trends
The competitive landscape is evolving along several axes. First, consolidation pressure remains relevant in mature component markets, where larger players can leverage scale, certification infrastructure, and global distribution. This does not mean that smaller or regional manufacturers are disadvantaged in every scenario; many compete effectively by focusing on specific applications, serving regional demand with shorter response times, or providing specialized configurations that larger portfolios may not prioritize.
Second, new-entry dynamics are shaped less by brand recognition than by supply chain access and qualification readiness. A manufacturer may have a technically capable product, but if it cannot meet the documentation, certification, or delivery expectations of target customers, its growth will be limited. This practical reality favors suppliers that invest early in the operational capabilities that high-value segments require.
Third, the market is likely to see continued segmentation rather than homogenization. Some product lines will compete as reliable standards in high-volume consumer and industrial applications, while others will be positioned as qualified solutions for automotive, medical, or defense-adjacent use cases. The most resilient companies are those that understand which segment they are serving and do not blur the distinction between commodity competitiveness and reliability-led differentiation.
For businesses evaluating the competitive field, a useful lens is whether a supplier competes on convenience, certification, application fit, or cost leadership. Each model can succeed, but the strategic requirements differ. Convenience-led players must excel in catalog completeness, distributor relationships, and specification clarity. Certification-led players must manage process control and qualification overhead efficiently. Application-fit players must maintain engineering relevance and segment-specific credibility. Cost leaders must protect margins through scale, process efficiency, and disciplined sourcing.
Future Outlook: Trends Shaping the Next Three to Five Years
Looking forward, the DIP switches market is likely to be shaped by a small number of reinforcing trends. These trends do not point to dramatic disruption, but they do indicate where value will migrate and where strategic attention will be rewarded.
Trend 1: Reliability as a Value Driver, Not Just a Feature
As electronics systems become more integrated into critical workflows, the perceived value of dependable manual interface components is likely to increase in select segments. DIP switches will not replace digital configuration everywhere, but they remain useful where physical feedback, field serviceability, and independent operation matter. Over the next few years, suppliers that can demonstrate consistent reliability, document performance across environmental conditions, and reduce the risk of failure in demanding applications will be better positioned to retain and expand share in higher-value niches.
The commercial opportunity here is not simply to sell switches, but to position them as risk-reduction elements in larger system designs. That can support more stable demand, stronger customer relationships, and greater tolerance for justified pricing. The risk is that suppliers overpromise on reliability without backing it with disciplined manufacturing and documentation, which can quickly erode trust in qualification-heavy segments.
Trend 2: Supply Chain Resilience Becomes a Core Purchasing Criterion
Tariff volatility, input cost variation, and lead time extensions are likely to keep supply chain resilience high on the procurement agenda. Buyers will continue to evaluate suppliers not only on unit price, but also on availability, geographic sourcing flexibility, and the ability to maintain continuity during disruptions. This favors manufacturers that can offer predictable delivery, clear communication, and alternative sourcing options.
For the market overall, this trend may encourage more deliberate inventory planning and broader qualification of secondary sources. It may also increase the importance of distributor networks as buffer and accessibility points. Companies that treat supply chain dependability as a strategic capability rather than an operational detail will have an advantage in retaining customers who cannot afford disruption.
Trend 3: Application-Focused Portfolio Strategy Will Outperform Generic Breadth
As the market matures, the most effective portfolio strategies are likely to be those that align product breadth with application needs rather than simply expanding part numbers. This means building credible positions in segments such as industrial control, automotive-adjacent electronics, medical devices, and consumer products, each with its own specification priorities and qualification expectations. Suppliers that understand these differences can tailor their messaging, packaging, and support to the customers they actually want to serve.
The opportunity lies in using application focus to reduce competitive noise. When a supplier is known for serving a specific segment credibly, it becomes easier to win design-in discussions and maintain repeat business. The risk is spreading too widely and becoming indistinguishable in a crowded field. In a market with high concentration and many established players, clarity of positioning is a meaningful advantage.
Strategic Recommendations for Decision Makers
The DIP switches market rewards disciplined strategy because it is mature, application-diverse, and sensitive to both cost and reliability considerations. The following actions can help different stakeholders navigate the landscape with greater confidence.
For Manufacturers and Brand Owners
- Clarify segment positioning before expanding product breadth. A wider catalog is only valuable if it reinforces a credible application narrative or distribution advantage.
- Invest in documentation, packaging, and specification clarity. In mature component markets, accessible technical information and standardized formats can accelerate design-in and reduce sales friction.
- Manage sourcing and input cost exposure proactively. Where tariffs and material inflation are relevant, transparent cost planning and alternative sourcing options can protect both margins and customer trust.
- Use certification and reliability messaging carefully and accurately. Claims carry weight in high-value segments, but they must be supported by consistent process control and real product performance.
For Investors and Strategic Planners
- Focus on durable differentiation rather than volume growth alone. In a market growing at a moderate pace, value creation often comes from segment strength, repeat demand, and customer stickiness.
- Assess exposure to trade and input-cost volatility. Companies with flexible sourcing, geographically diversified production, or strong distributor reach may be better positioned to absorb disruption.
- Look for evidence of application-led strategy. Suppliers that serve specific high-reliability or high-value segments with clear qualification support are often more resilient than undifferentiated commodity players.
- Track portfolio and catalog activity as a leading indicator of commercial intent. New item releases, datasheet updates, and distributor availability can signal where a company is trying to build future demand.
For Procurement and Engineering Leaders
- Evaluate total cost of ownership, not just unit price. In applications where re-qualification, downtime, or field service matter, delivery reliability and documentation can outweigh marginal price differences.
- Qualify secondary sources for critical switch functions. Supply chain uncertainty makes it prudent to maintain alternatives for parts that are difficult to substitute once designs are locked.
- Align switch selection with actual environmental and service requirements. Over-specifying can increase cost unnecessarily, while under-specifying can create reliability risk in demanding environments.
- Keep specifications and sourcing documentation current. Updated datasheets and clear part parameters reduce engineering friction and support smoother lifecycle management.
Closing Perspective
The DIP switches market is not defined by rapid transformation, but by the steady accumulation of application-specific value, supply chain discipline, and competitive positioning. Growth is expected to continue at a moderate pace, supported by enduring demand across consumer, industrial, automotive, and telecommunications applications. Yet the real strategic question is not whether the market will expand, but how companies will navigate concentration, cost pressure, certification expectations, and shifting sourcing realities.
Businesses that succeed in this environment tend to treat DIP switches as more than simple electromechanical parts. They align product portfolios with real application constraints, maintain credible quality and documentation practices, and build sourcing resilience into their operating model. For readers seeking a deeper dive into segment-level revenue structures, regional dynamics, company-level positioning, and customized strategic scenarios, the full PW Consulting industry report provides a more granular view of the market and its forward trajectory.
For detailed analysis of this topic, please visit the official page: DIP Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Trichloroisocyanuric Acid Market 2026: Why 6.5% CAGR Alone Misses the Real Growth Drivers
By pmarketresearch, 2026-09-21
Trichloroisocyanuric Acid Market: Strategic Trends and Commercial Opportunities Through 2032
The trichloroisocyanuric acid market has entered a phase of steady expansion, driven by persistent demand for reliable disinfection solutions and industrial water management. Valued at approximately 226.4 million USD in 2025, the market has grown consistently from 185.5 million USD in 2020, reflecting a compound annual growth rate of 6.5 percent. Projections indicate the market will reach 347.3 million USD by 2032, underscoring a structural shift rather than a temporary cycle. This growth trajectory is supported by expanding applications across sanitation, water treatment, and bleaching sectors, alongside evolving regulatory landscapes that are reshaping supply chains and competitive dynamics.
For decision-makers, the critical question is no longer whether demand will grow, but how to navigate the structural complexities that accompany this expansion. Regional demand concentration, shifting trade policies, and raw material volatility are redefining value creation opportunities. Companies that align their strategies with these macro trends while preparing for regulatory and supply chain disruptions will capture disproportionate market share.
Worldwide Chlorinated Isocyanurates Market
Market Landscape and Core Challenges
The market's growth is not uniform across geographies or application segments. Asia Pacific continues to represent the largest share of revenue, followed by North America and Europe, while Latin America and the Middle East and Africa contribute smaller but growing portions. Form-wise, granular products dominate the market, reflecting preferences for ease of handling and dosing control in commercial and municipal applications. Powder and tablet formats serve more specialized use cases, often tied to specific regulatory approvals or end-user operational requirements. In terms of application, disinfection and sanitation remains the largest segment, absorbing the majority of production output, while bleaching and water treatment applications provide complementary demand streams.
PW Consulting
Despite the positive growth outlook, three structural challenges are reshaping how companies operate and compete.
Raw Material Volatility and Cost Structure Pressures
Production economics for trichloroisocyanuric acid are tightly linked to the pricing of cyanuric acid and chlorine derivatives. In 2024, cyanuric acid prices rose by 9.6 percent and chlorine prices increased by 6.2 percent, driven by supply chain disruptions and environmental regulatory caps in China. These cost pressures compress margins for manufacturers that lack diversified sourcing strategies or integrated production capabilities. The volatility also creates pricing uncertainty for downstream buyers, complicating long-term procurement planning and prompting some end-users to explore alternative disinfectants.
Regulatory Fragmentation and Trade Barrier Risks
Compliance requirements are diverging across major markets, creating a fragmented regulatory environment that penalizes companies without robust certification strategies. The EU Commission Implementing Regulation (EU) 2025/2216 imposed definitive anti-dumping duties on imports of trichloroisocyanuric acid originating in China following a partial interim review. Simultaneously, the US Department of Commerce and International Trade Commission maintained countervailing duty orders on chlorinated isocyanurates from China. These measures, alongside broader export controls, introduce supply chain concentration risks for EU and US markets that rely heavily on Chinese production capacity.
For manufacturers, navigating these duties requires either diversifying sourcing origins, investing in localized production, or securing regulatory approvals that can mitigate trade barriers. The cost of non-compliance or delayed certification is significant, as market access can be restricted or rendered unprofitable by duty structures.
Competitive Concentration and the Need for Differentiation
The market remains highly concentrated, with the top three players capturing approximately 68.5 percent of revenue and the top five accounting for 85.2 percent. This concentration reflects the capital intensity of scale production, the importance of regulatory approvals, and the value of established customer relationships in sanitation and water treatment sectors. While concentration provides stability for leading players, it also raises the barrier for new entrants and intensifies competition among incumbents to defend share through product differentiation, certification leadership, and supply chain reliability.
Companies that compete solely on price face margin erosion, particularly as raw material costs and compliance expenses rise. Sustainable advantage increasingly depends on operational efficiency, regulatory foresight, and the ability to offer tailored formulations or service support that aligns with specific end-user requirements.
Key Drivers Shaping Market Trajectory
Technical Innovation in Product Formulations and Application Efficiency
Innovation in trichloroisocyanuric acid products is shifting from basic commodity production toward performance optimization and application-specific solutions. Manufacturers are investing in granules with controlled dissolution rates, tablets with improved handling safety, and formulations that reduce byproduct formation or improve stability under varying storage conditions. These improvements address end-user concerns around dosing precision, safety, and operational efficiency, particularly in swimming pool sanitation and municipal water treatment where consistency and compliance are critical.
Recent certification milestones illustrate how regulatory compliance and technical validation are becoming competitive differentiators. EPA conditional reregistration issued for trichloroisocyanuric acid (TCCA 90) product registration in April 2025, and EU BPR approvals received by multiple manufacturers including Ercros S.A. and representatives from the IIAHC member network in November 2025, signal that regulatory clearance is increasingly a prerequisite for sustained market access in developed regions. Companies that secure and maintain these approvals can command premium positioning and reduce the risk of market disruption from compliance changes.
Policy and Regulatory Environment as Both Constraint and Catalyst
Regulatory dynamics are reshaping where and how value is created. Anti-dumping duties and countervailing measures on Chinese-origin trichloroisocyanuric acid have redirected trade flows and incentivized non-Chinese producers to expand capacity or strengthen their certifications. For the EU and US markets, this environment creates both risk and opportunity. Import-dependent buyers face supply chain concentration risks, while compliant manufacturers with diversified origins or local production capabilities can capture displaced demand.
At the same time, environmental and safety regulations are pushing manufacturers toward more transparent sourcing, improved handling standards, and documentation that supports downstream compliance. Companies that treat regulatory compliance as a strategic capability rather than a cost center are better positioned to expand into higher-value segments and maintain continuity in the face of policy shifts.
Demand-Side Shifts in Sanitation, Water Treatment, and Industrial Use
Demand growth is being sustained by several structural factors. Public and commercial sanitation requirements remain elevated as facilities prioritize reliable disinfection protocols. Swimming pool and recreational facility operators continue to rely on trichloroisocyanuric acid for its efficacy and ease of use, particularly in granular and tablet formats that support controlled application. Water treatment applications, both municipal and industrial, are expanding as regions invest in infrastructure upgrades and stricter water quality standards. Bleaching applications provide additional demand, especially in textile and paper sectors where chlorinated isocyanurates offer effective whitening and disinfection properties.
The demand pattern is also shifting toward buyers who value supply reliability and certification assurance over lowest-cost procurement. This is particularly evident in regulated markets where compliance documentation and product consistency are non-negotiable. Manufacturers that can demonstrate stable supply, validated product quality, and responsive technical support are gaining preference in these segments.
Supply Chain Reconfiguration and Capacity Expansion
Capacity expansion is a central theme in the market's evolution. Production facility expansions of approximately 20,000 metric tons annually have been reported in 2024 and 2025, aimed at meeting export demand and strengthening supply resilience. These expansions reflect the expectation of continued volume growth and the strategic importance of securing sufficient capacity to serve key export markets.
At the same time, supply chain diversification is becoming a priority for buyers and manufacturers alike. The combination of raw material price volatility, trade duties, and regulatory approvals is pushing companies to evaluate multi-sourcing strategies, regional production footprints, and inventory management practices that can buffer against disruptions. For exporters, this means that capacity alone is insufficient; competitiveness increasingly depends on the ability to deliver compliant products with predictable lead times and transparent documentation.
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of established Chinese manufacturers, European branded producers, and specialized Indian and Japanese players. Hebei-based manufacturers such as Hebei Kaihong Chemical Co., Ltd. and Hebei Xingfei Chemical Co., Ltd. maintain strong positions in granular, tablet, and powder formats for pool sanitation, water treatment, and disinfection. Heze Huayi Chemical Co., Ltd. and Zhucheng Taisheng Chemical Co., Ltd. extend the Chinese manufacturing base with additional capacity focused on industrial and water treatment applications, while Shandong Lantian Disinfection Technology Co., Ltd. and Puyang Cleanway Chemicals, Ltd. serve as active suppliers in powder and granular segments. Zhengzhou Mahaco Industrial Co., Ltd. and Taian Huatian Chemical Co., Ltd. round out the Chinese export-oriented landscape, emphasizing water treatment and pool use cases.
In Europe, Ercros S.A. stands out with its Delsa and Bluei branded products targeting swimming pools and recreational facilities, combining regional brand recognition with regulatory alignment. In India, Bodal Chemicals Ltd. positions itself as the country's first and only manufacturer of TCCA 90 for water purification and disinfection, leveraging local production to serve domestic demand and potentially regional exports. In Japan, Nippon Soda Co., Ltd. and Sikoku Chemicals Corporation focus on industrial water treatment and disinfection applications, benefiting from technical credibility and proximity to regulated end markets.
Strategic Positioning and Differentiation
Leading players are differentiating along several dimensions. Scale and capacity expansion allow exporters to meet large-volume demand and reduce per-unit costs, but this advantage is only sustainable when paired with reliable compliance and logistics. Regulatory certification leadership provides access to premium segments and reduces the risk of trade barriers or market access restrictions. Brand building, particularly in European and recreational facility markets, supports customer loyalty and price resilience. Product form specialization, such as controlled-release granules or safety-oriented tablets, addresses specific application needs and can justify differentiated pricing.
Companies that combine multiple advantages—such as capacity, certification, and application-focused product design—are best positioned to defend share and expand into higher-value segments. Those that rely on a single strength, such as low-cost production without compliance depth, face greater exposure to margin pressure and regulatory risk.
Market Evolution Trends
The market is likely to see consolidation among smaller producers who struggle with certification costs, raw material volatility, and trade barriers, while larger and well-capitalized players expand capacity and strengthen their compliance portfolios. At the same time, there is room for niche differentiation, particularly in specialized applications or regions where local production and regulatory alignment create barriers for generic commodity suppliers. New entrants will find it challenging to compete on scale alone; success will depend on securing regulatory approvals early, building reliable supply chains, and targeting segments where product performance and documentation matter more than price.
Export-oriented manufacturers will increasingly need to navigate a dual reality: strong demand growth in many regions, but also a complex web of duties, approvals, and sourcing expectations. Those that can balance capacity expansion with regulatory readiness and supply chain diversification will be most resilient.
Future Trends and Commercial Opportunities (2026–2032)
Continued Capacity Expansion with a Compliance-First Posture
Over the next three to five years, capacity expansion is expected to continue, particularly in regions that can support export growth while managing regulatory requirements. The 6.5 percent CAGR projected through 2032 implies that demand will grow by more than 100 million USD in cumulative value over the forecast period. Suppliers that add capacity with integrated compliance strategies—securing relevant certifications, aligning with destination-market regulations, and ensuring documentation readiness—will be able to capture displaced demand from trade barriers and benefit from the overall market uptrend.
For buyers, this trend creates an opportunity to diversify supply sources and reduce dependence on any single origin. Procurement strategies that combine multiple certified suppliers, regional inventory buffers, and long-term agreements with compliance assurances will be more resilient to duty changes and raw material shocks.
Premiumization and Application-Specific Solutions
As the market matures, differentiation through product performance and application support will become more valuable. Granular formats are likely to maintain dominance due to ease of use, but there is room for innovation in dissolution profiles, packaging safety, and formulation stability that reduce handling risks and improve operational outcomes. Tablet and powder segments may see targeted growth in specialized disinfection and industrial use cases where precise dosing or specific handling requirements justify a premium.
Manufacturers that invest in technical service, application guidance, and consistent quality documentation can shift the competitive basis from price to value. This is especially relevant for water treatment and municipal sanitation buyers who prioritize reliability and compliance over marginal cost savings. The opportunity lies in building repeatable, application-focused offerings that reduce total cost of ownership for end-users, even if unit prices are higher.
Cyanuric Acid Market
Supply Chain Regionalization and Risk Mitigation as a Competitive Edge
Regulatory duties and raw material volatility are accelerating interest in regionalized supply chains. EU and US buyers are increasingly aware of concentration risks from reliance on Chinese-origin imports, and the imposition of definitive anti-dumping duties and continued countervailing orders reinforces the incentive to diversify. This does not necessarily mean a full exit from Chinese sourcing, but it does favor multi-region strategies that balance cost with compliance and continuity.
Commercial opportunities will emerge for suppliers that can offer transparent origin documentation, certified product quality, and flexible logistics that adapt to changing duty structures. Manufacturers with production footprints or partnerships in multiple regions can position themselves as lower-risk options for procurement teams seeking to stabilize supply. At the same time, buyers that invest early in qualifying alternative sources will be better prepared to switch or blend suppliers without disruption when trade policies shift.
Risks and Uncertainties to Monitor
Several uncertainties could alter the trajectory. Raw material price spikes may recur if environmental caps tighten or supply chain disruptions emerge, compressing margins and destabilizing pricing. Regulatory reviews could expand or intensify, affecting not only Chinese-origin products but also the broader competitive balance if duties are extended or if certification requirements become more stringent. Demand growth could slow in specific segments if alternative disinfectants gain traction or if economic constraints reduce discretionary spending on pool and recreational facility maintenance. Finally, capacity expansions could outpace demand in certain sub-segments, leading to localized oversupply and price competition.
Monitoring these risks requires continuous attention to raw material markets, regulatory announcements, and end-user adoption trends. Companies that build scenario planning into their procurement, production, and sales strategies will be better equipped to respond quickly when conditions change.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
Prioritize certification and regulatory readiness as core capabilities rather than administrative tasks. Securing and maintaining EPA, EU BPR, and other relevant approvals is increasingly a determinant of market access and customer trust. Pair capacity expansion with compliance depth so that new volume can be commercially absorbed in regulated markets. Diversify raw material sourcing where feasible to reduce exposure to price spikes, and consider integrated or strategic partnerships that improve cost predictability.
Differentiate through application-focused product design and technical support. Controlled-release granules, safer tablet formats, and consistent quality documentation can justify premium positioning and reduce the risk of pure price competition. Build customer-facing capabilities that help end-users meet their own compliance and operational requirements, turning product sales into longer-term service relationships.
For Investors and Capital Allocators
Focus on companies that combine scale with regulatory resilience and supply chain flexibility. Capacity expansion alone is not a sufficient investment thesis; the more durable opportunities lie in producers that can navigate trade duties, maintain certifications, and serve multiple regions or applications without over-concentration. Evaluate exposure to raw material volatility and the company's mitigation strategies, including sourcing diversity, pricing mechanisms, and inventory management.
Watch for consolidation opportunities as smaller producers face certification costs and compliance complexity. Well-capitalized players with established approvals and diversified customer bases are likely to be both defensive and acquisitive, creating potential for value creation through share gains and selective integration. At the same time, assess end-market demand durability in sanitation, water treatment, and industrial segments to ensure that growth assumptions are grounded in structural trends rather than short-term cycles.
For Procurement and Supply Chain Leaders
Treat supply resilience as a strategic priority, not just a cost optimization exercise. Diversify approved suppliers across regions and product forms to mitigate concentration risk from duties and raw material volatility. Establish qualification processes that prioritize certification status, documentation reliability, and consistent product quality alongside price. Consider long-term agreements with suppliers that can demonstrate compliance readiness and flexible logistics, and maintain contingency options for rapid supplier transitions if trade policies change.
Engage early with suppliers on application requirements and compliance expectations. Aligning on product specifications, handling safety, and documentation needs reduces the risk of disruptions and improves total cost outcomes over time. Where possible, build inventory buffers for critical applications and monitor raw material price trends to time procurement decisions more effectively.
Navigating the Next Phase
The trichloroisocyanuric acid market is positioned for sustained growth, but the value creation opportunities are increasingly tied to regulatory agility, supply chain resilience, and application-focused differentiation. The combination of a 6.5 percent CAGR through 2032, evolving trade duties, and ongoing capacity expansion creates a complex but navigable environment for companies that plan strategically.
Decision-makers who understand where concentration risks lie, which certifications matter most in their target markets, and how raw material dynamics affect cost structures will be better prepared to capture growth while managing downside exposure. Detailed segmentation data, company-level profiling, and region-specific regulatory tracking can sharpen these decisions further, enabling more precise planning for capacity, sourcing, and market entry.
For a deeper dive into the market's segmentation dynamics, competitive benchmarking, and region-specific regulatory outlook, the full market research report provides comprehensive data and tailored scenarios to support strategic planning across manufacturing, investment, and procurement functions.
For detailed analysis of this topic, please visit the official page: Trichloroisocyanuric Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com